Why You Actually Need to Care About Economics
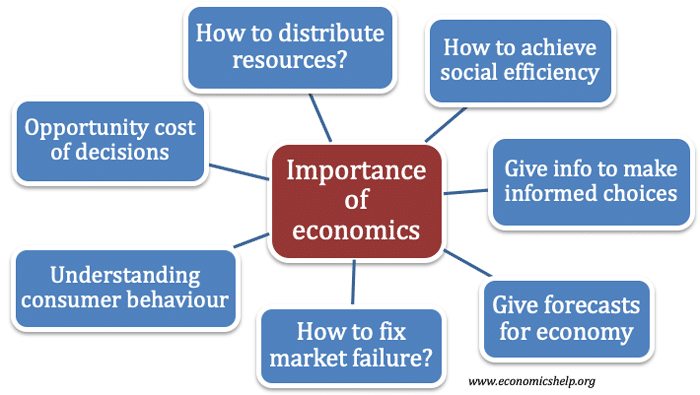
I used to roll my eyes when people talked about learning economics like it was going to change their life. Then I spent five years working in financial planning, watching good people make terrible money decisions because they understood basic math but not basic incentives. It got old fast. Economics isn't just graphs and supply curves. It's the study of how people make choices when resources are limited, which means it's everywhere you look. Here is what actually matters when you understand it well enough to use it. Understanding personal finance decisions is probably the most immediate payoff. When you know concepts like opportunity cost and marginal utility, you stop wasting money on things that sound good but don't actually move the needle for your situation. I had a client who insisted on paying off his mortgage early instead of investing, and once we mapped out the actual tax implications and compound growth over twenty years, he changed his mind. He saved about forty thousand dollars that way.
It shapes how you vote and engage with policy. A lot of political debates are just economics wrapped in emotion. Carbon taxes, universal basic income, minimum wage changes -- these are all economic mechanisms. If you can read them correctly, you stop getting manipulated by half-baked slogans. I remember getting into an argument at a dinner party with someone who was dead set on a rent control policy because "landlords are greedy." Once I walked him through how rent control reduces housing supply over time, his whole position unraveled pretty quickly. It's not about greed, it's about incentives. Business decisions run on economics whether owners admit it or not. Pricing strategy, inventory management, hiring -- it's all there. The classic beginner mistake is confusing revenue with profit. You can double your sales and still lose money if your cost structure is misaligned. I consulted for a small manufacturing company that was growing at thirty percent year over year and bleeding cash. Their gross margins were positive but their operating expenses scaled faster than revenue because they hadn't accounted for diminishing returns on their sales team. We restructured their commission model and the company stopped hemorrhaging money within two quarters. Inflation literacy protects your purchasing power. People don't think about inflation until it eats them alive. If you keep your savings in a regular checking account earning point one percent while inflation runs at four, you are losing ground every single year without noticing it. That's why understanding real versus nominal returns matters so much. It sounds like a basic concept but most people never actually apply it to their own money.
Global supply chains make sense when you understand comparative advantage. The reason your phone is assembled in China with parts from twelve different countries and sold in Ohio is not an accident. It's economics playing out at scale. I spent a few years watching a local retail chain try to bring its supply chain domestic during the pandemic. Cost went up thirty-five percent and they had to raise prices across the board. Customers noticed. The business model couldn't survive the switch. That was a textbook case of ignoring comparative advantage at your own risk. It improves your ability to negotiate. Whether it's a salary discussion, a vendor contract, or buying a house, negotiation is fundamentally about information asymmetry and leverage. Economics teaches you how to identify where your leverage actually is instead of guessing. I've seen people walk away from a five thousand dollar raise because they didn't understand their market value. The data was there, they just didn't know how to read it. Market failures are real and they matter. Externalities, public goods, asymmetric information -- these are not academic terms. They describe situations where the market produces outcomes that are clearly bad for society and no individual actor has the incentive to fix it. Air pollution is the classic example. Nobody owning the atmosphere has a reason to clean it up. That's why regulation exists, and understanding why it exists is different from just knowing it exists.
Get the Full Details

Economics changes how you interpret news. When a headline says "unemployment drops to lowest level in decades," the trained response is to ask what the labor force participation rate looks like and whether the jobs are full-time or part-time. Most people see the headline and feel either hopeful or panicked depending on their mood. The data rarely supports simple emotions. I read a lot of economic journalism and honestly half of it is wrong or misleading because the writers don't understand what they're looking at. It's easier than you'd think to spot when someone is misusing statistics. It helps you manage risk. Risk and return are linked in ways that pop psychology finance advice completely misses. Diversification isn't a platitude, it's a mathematical consequence of correlation. The people who understand covariance and standard deviation make better investment decisions than the ones who follow twitter threads about which stocks are hot. This is the part where I say that most retail investors outperform very few professionals when you measure properly over long time horizons, but they do it by accident, not by skill. Trying to beat the market is usually a losing game unless you have information or timing advantages that regular people simply don't have. Long-term thinking becomes second nature. Discount rates, net present value, compound growth -- these concepts rewire how you evaluate decisions. A dollar today is worth more than a dollar tomorrow, and that changes everything about how you plan. Retirement savings, education investments, even whether to get a degree at all -- economics gives you a framework instead of just vibes. I watched a friend spend two hundred thousand dollars on a graduate program in a field with poor job prospects because he thought the title would open doors. The labor market data was publicly available. He ignored it. It hurt to watch.
Where Economics Falls Short
Here is the honest part that most people won't tell you: economics is not a crystal ball. It predicts trends and probabilities, not specific outcomes. The models are built on assumptions that often don't hold in the real world. Humans are not rational actors, and the more we study economics, the more obvious it becomes that behavior economics exists as a correction to that assumption. There are also blind spots. Traditional economics struggles with things like wealth inequality, environmental degradation beyond simple externalities, and the qualitative aspects of human wellbeing that no GDP figure captures. When I worked in corporate strategy, I saw executives cite economic models to justify decisions that were clearly emotionally driven. The model was just a costume for prejudice at that point. Another issue is data quality. Garbage in, garbage out applies to economics just as much as anywhere else. Many economic indicators are revised months after publication, sometimes dramatically. The GDP number you read about in January might be totally different by June. Making decisions based on preliminary data is a common trap, especially for people who read financial news daily.
If you want to actually use economics rather than just admire it, the practical workaround is to combine it with other frameworks. Game theory helps with strategic interactions. Psychology explains the irrational bits that pure economics can't account for. Simple accounting basics ground everything in reality. I teach a short workshop on this sometimes and the participants always say the same thing: they wish they'd learned to connect these fields together earlier. The bottom line is that economics is a tool, not a religion. Used carefully it makes you sharper at decisions involving money, time, and tradeoffs. Used blindly it gives you a false sense of certainty. The difference is whether you pay attention to what the models can't tell you.