Accounting Information And What It Actually Does For You
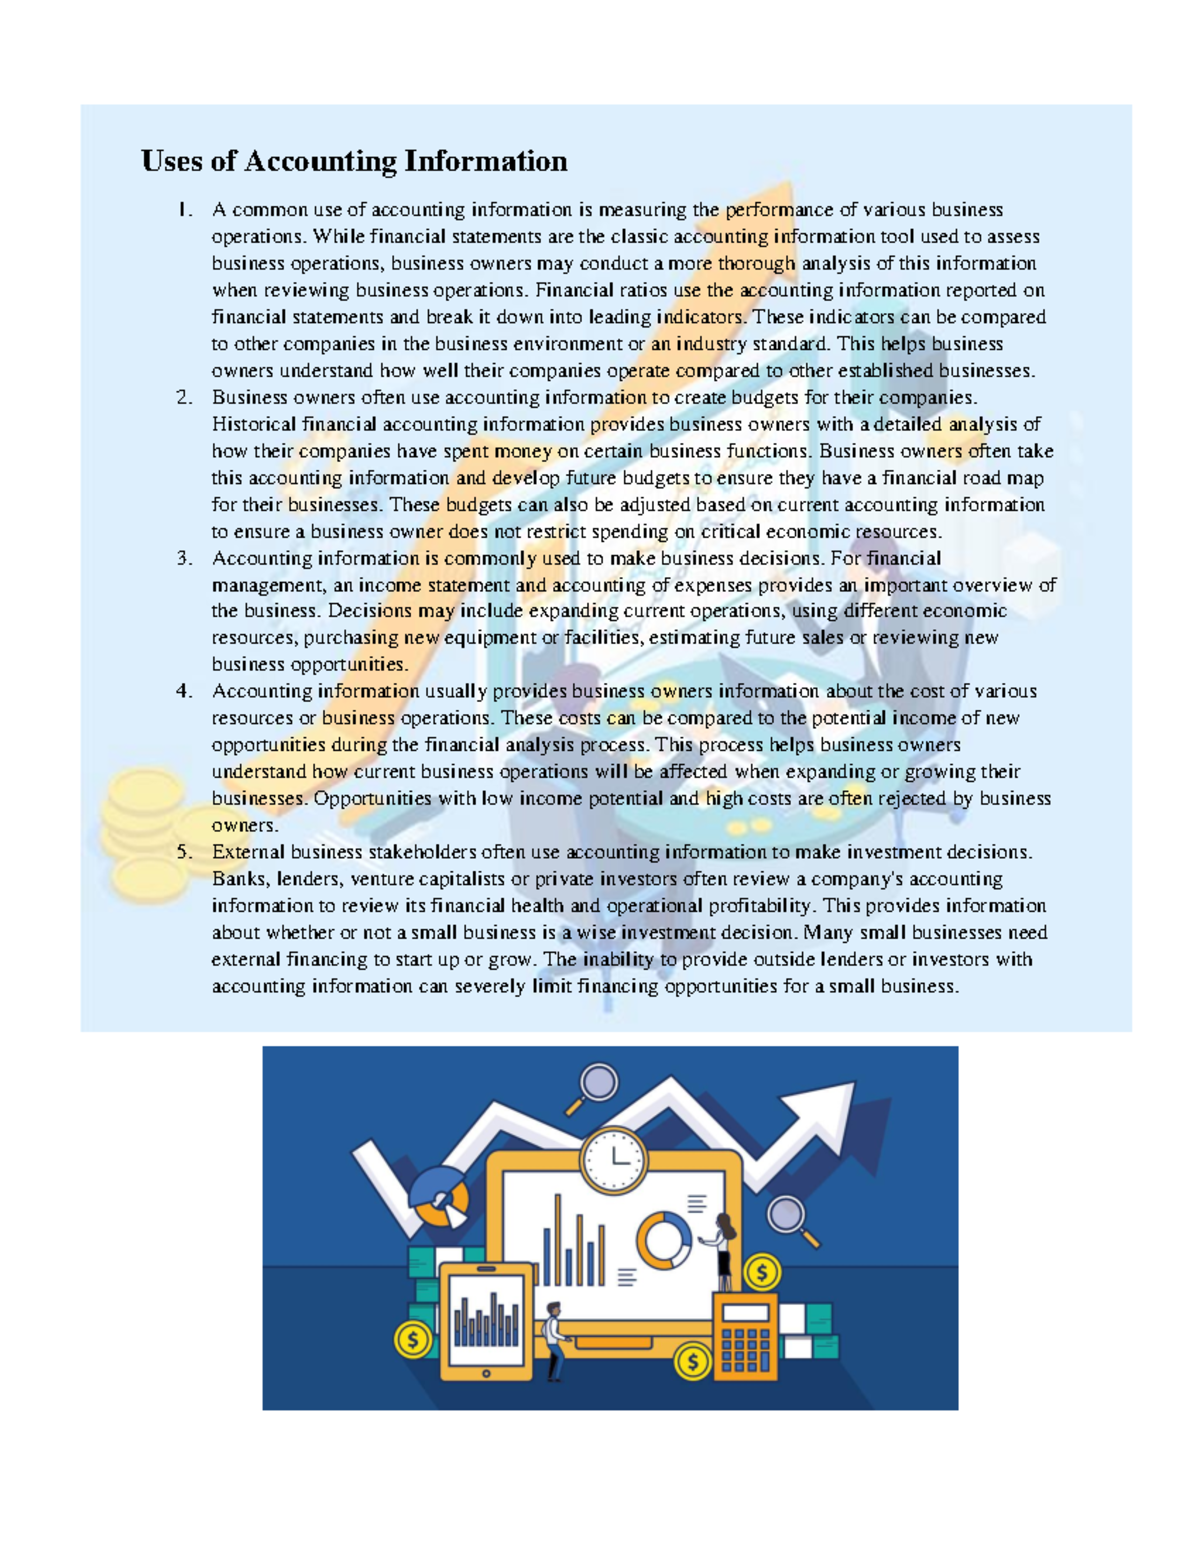
I spent years cleaning up books for small business owners who thought accounting was just tax season paperwork. It isn't. The information generated by your ledger touches nearly every decision you make, whether you realize it or not. Here is what I have seen work in practice. 1. Budgeting and financial planning. This is the most common use and also the most misunderstood. People take last year's numbers and adjust them up by ten percent. That is not a budget. A proper budget compares your revenue patterns against seasonal reality, your fixed costs, and your actual cash conversion cycle. I once had a client who budgeted based on gross revenue instead of net cash after payables. They went broke in Q2 despite showing profit on paper. The fix was switching to a cash-basis forecast and tracking receivable aging weekly. 2. Performance tracking against targets. Variance analysis tells you whether you are actually meeting your goals or just hitting revenue numbers while margins collapse. I recommend looking at contribution margin by product line or service, not just top-line sales. One retail client was celebrating twenty percent revenue growth until I showed them that three of their five product lines were operating at negative contribution after COGS and direct labor. They were buying revenue at a loss.
3. Credit and lending decisions. Banks and lenders read your financial statements before they approve anything. Consistent profitability matters, but liquidity ratios matter more for short-term credit. The DSCR (debt service coverage ratio) is the number that usually makes or breaks a loan application. If your net operating income divided by your total debt obligations falls below 1.25, expect pushback. I have seen solid businesses denied lines of credit simply because their balance sheet showed too much inventory relative to quick assets. 4. Tax compliance and planning. Accounting information feeds your tax filings directly. But the planning side is where people leave money on the table. Depreciation schedules, amortization of intangible assets, accrued versus cash expenses, and entity-level choices all flow from your accounting records. The workaround most businesses miss is tracking deductible expenses month-by-month instead of waiting until April. I set up a rolling expense cutoff calendar for a client and shaved roughly eight thousand dollars off their annual tax liability through better timing of equipment purchases and bonus depreciation elections. 5. Pricing decisions. Your cost data should dictate your pricing floor, not your gut feeling or what the competitor charges. Activity-based costing gives you a clearer picture of what products actually cost to deliver when you allocate overhead by driver rather than spreading it evenly. A restaurant I worked with discovered their signature dish had a food cost of thirty-eight percent after accounting for waste, prep time labor, and portion control. They raised the price by eleven dollars and the dish became their highest-margin item without losing volume.
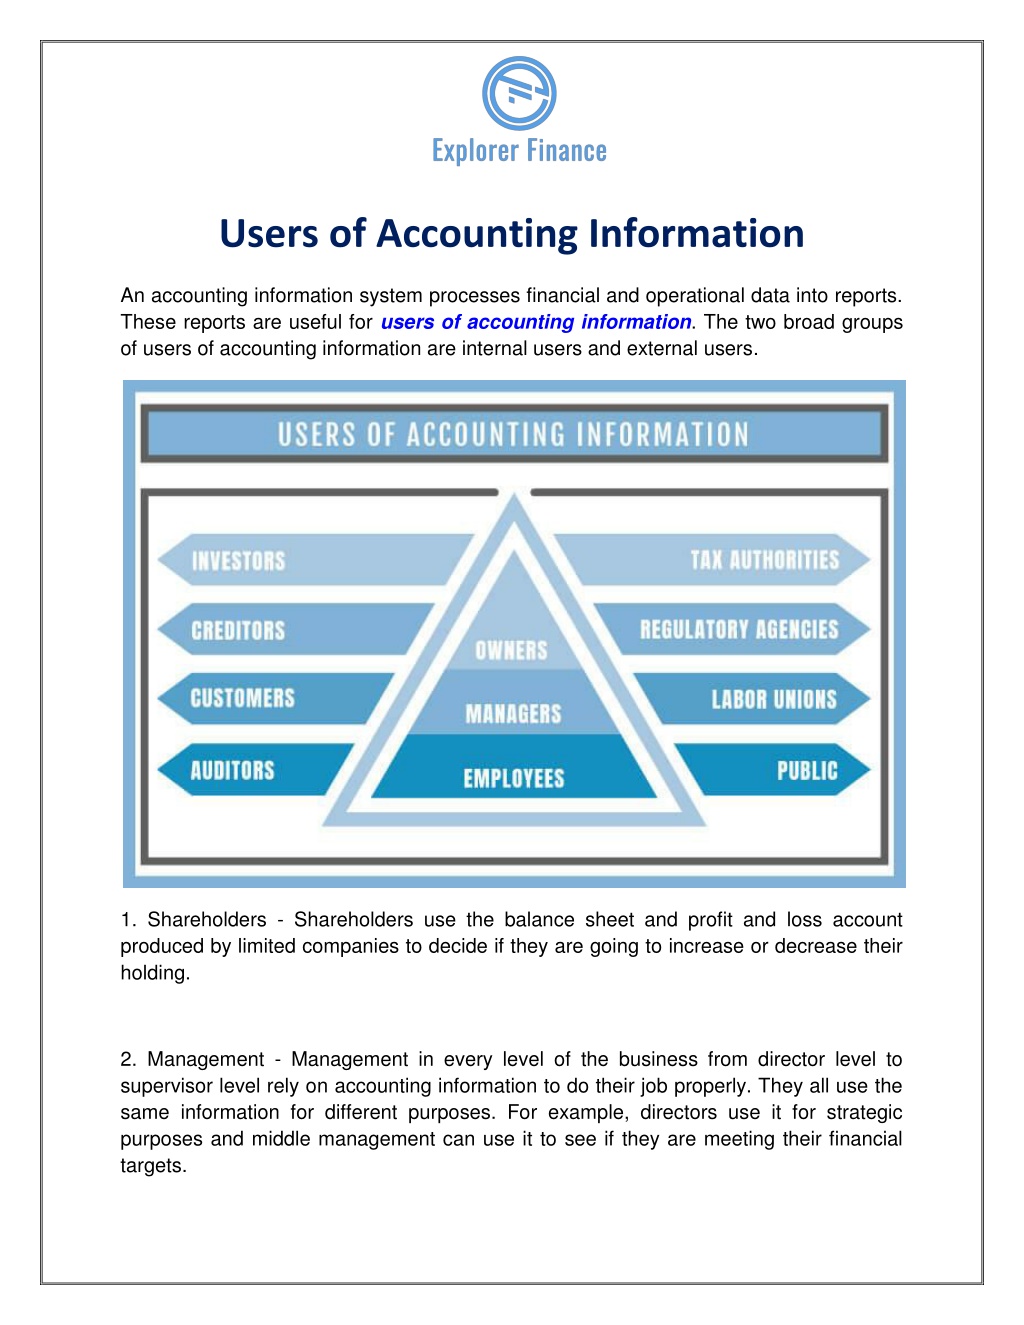
6. Investor and stakeholder communication. If you are raising capital or reporting to partners, your accounting information is the primary document people read. Consistency in presentation matters as much as accuracy. One investor I spoke with rejected a term sheet entirely because the company switched accounting methods mid-year without disclosure. The numbers were fine. The lack of transparency was the problem. 7. Fraud detection and internal controls. Reconciling your accounts regularly surfaces anomalies before they become losses. Benford's law analysis on vendor payments, duplicate payment checks, and unusual journal entries near period end are standard procedures. I caught a payroll fraud scheme by noticing that one employee's overtime hours spiked consistently in the last three days of each pay period. It turned out to be a supervisor padding hours. The monthly reconciliation would have caught it months earlier if someone had actually been doing it. 8. Operational efficiency analysis. Ratio analysis on inventory turnover, accounts receivable days, and accounts payable days reveals where cash is stuck. A manufacturing client of mine had an inventory turnover ratio of 4.2 while their industry benchmark was 8.5. Half their working capital was sitting on shelves. They reduced SKUs by thirty percent and renegotiated reorder points, freeing up nearly two hundred thousand in cash within six months.
Get the Full Details
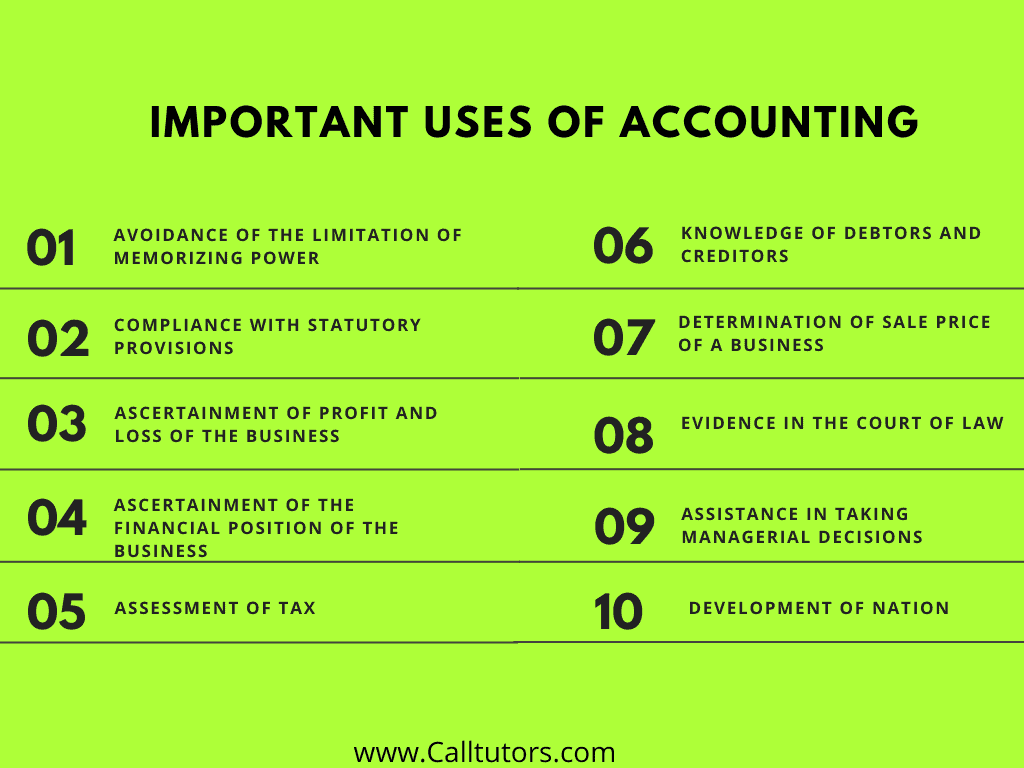
9. Strategic decision-making. Make-or-buy decisions, expansion feasibility, and acquisition targets all depend on your cost structure and profitability data. When I advised a company considering whether to lease or buy equipment, the break-even analysis came from their own depreciation schedules, tax position, and cost of capital. The answer changed depending on whether they used straight-line or accelerated depreciation, which is a detail most small business owners overlook. 10. Regulatory and compliance reporting. Depending on your industry and size, you may need to file reports with government agencies, industry bodies, or regulatory commissions. GAAP compliance, IFRS conversion, sector-specific requirements like healthcare or nonprofit reporting — all of this relies on your underlying accounting system being structured correctly from the start. I spent three weeks rebuilding a nonprofit's chart of accounts because their donation tracking was mixed with program expense coding. Grant reviewers flagged it immediately.
The Practical Reality
Accounting information is only useful if it is current and accurate. Stale data from three months ago leads to decisions based on conditions that no longer exist. Most small businesses I encounter are running on outdated spreadsheets instead of integrated software, which means their "information" is really just memory and guesswork dressed up in columns. The systems that work best are those where transactions flow from point of sale or point of service directly into the ledger without manual re-entry. Automating that step reduces errors and gives you real-time visibility. Manual data entry introduces mistakes at a rate of roughly one to two percent per transaction, which compounds quickly over thousands of entries per quarter. If you are building this from scratch, start with a chart of accounts that matches how you actually operate, not how an accountant textbook says you should. Then pick software that grows with you rather than what is cheapest today. The transition cost from a basic system to a more capable one averages two hundred to four hundred hours of setup and data migration if you do it right, or about twice that if you try to fix it after the fact.