Converting Large Sums From Yen to Dollars
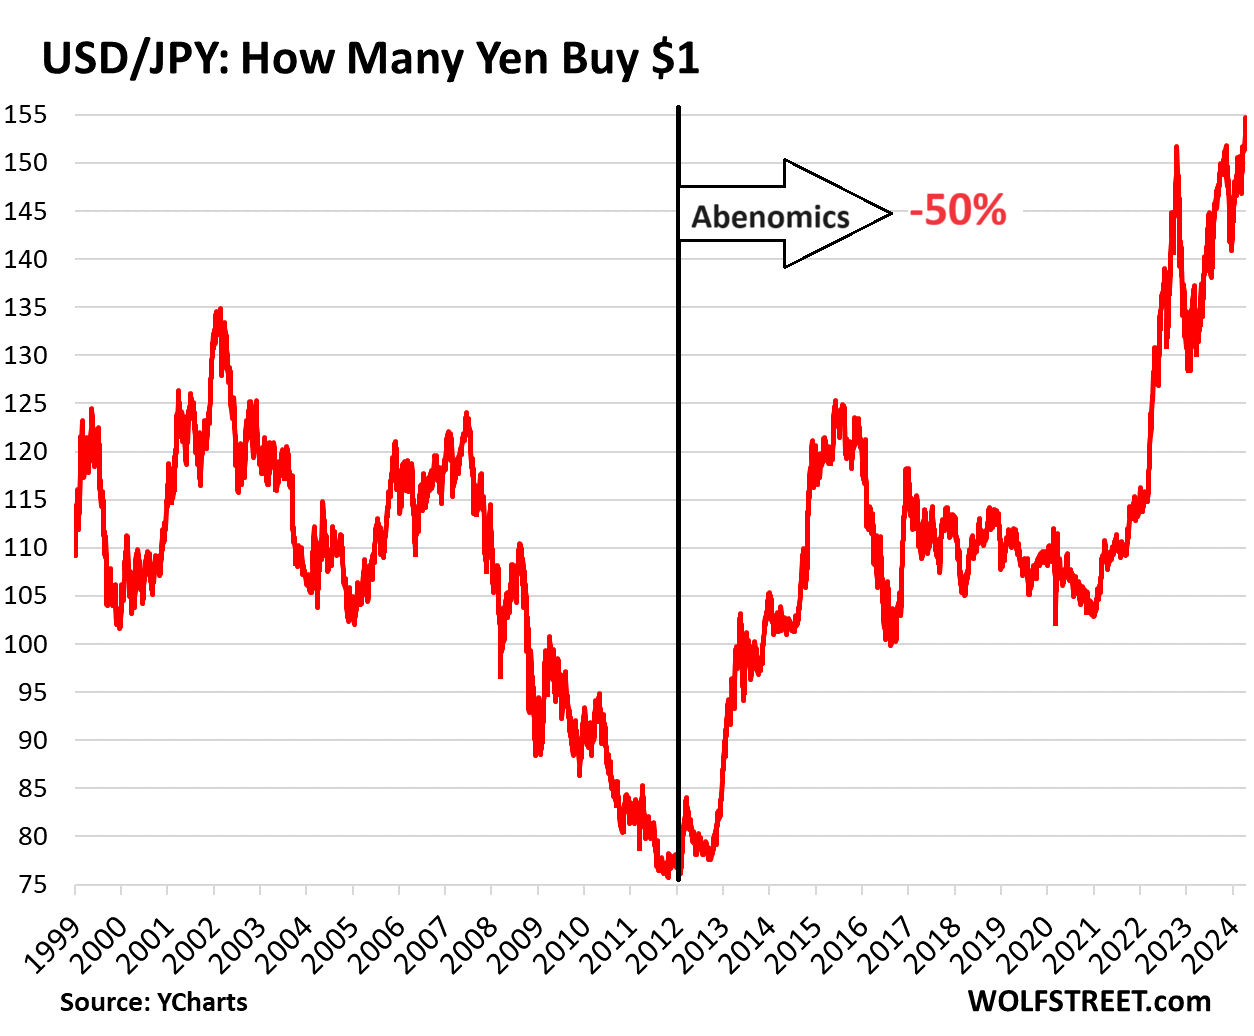
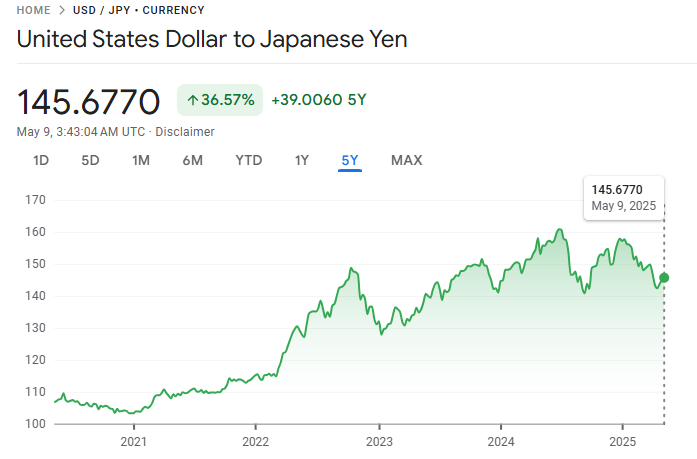
The exchange rate between the Japanese yen and the US dollar shifts constantly. At the time I'm writing this, 100 million yen sits somewhere in the ballpark of $650,000 to $680,000, but checking a live rate will always give you a slightly different number than the one I'm quoting here. The way to figure this out properly is simple math, though how you execute it matters more than most people realize. You take your amount in yen, divide it by the current exchange rate, and that's your USD equivalent. So if the rate is 155 yen per dollar, you divide 100,000,000 by 155 and you get roughly $645,161. If the rate is 148, the same 100 million yen nets you about $675,676. That 7.4% swing between those two rates is not theoretical. It happened over roughly an eight-month stretch in 2024, and any large transaction during that window felt very different on either side. The exchange rate you see on Google or a free currency site is the mid-market rate. That is not the rate you will actually get if you are moving real money. Banks and remittance services add a spread, and on a transaction this size the spread becomes the single biggest cost. A spread of even 0.5% on 100 million yen eats about $3,200 out of your total. That is not a rounding error. It is a meaningful chunk of money that disappears before the funds ever reach your account.
I learned this the hard way a few years ago when I was handling a property sale in Tokyo for a client who needed the proceeds in USD. The mid-market rate looked favorable at around 130 yen to the dollar. My client's bank quoted them a rate of about 134.5 for the actual wire transfer. The difference looked small per unit, but on 100 million yen it came out to roughly $2,900 less than what the headline rate promised. We ended up using a specialized FX broker instead, locked in a rate closer to 131, and cut that cost down to about $600. The broker charged a small fee on top, but the tighter rate more than covered it.
Why the Numbers Change Faster Than You Think
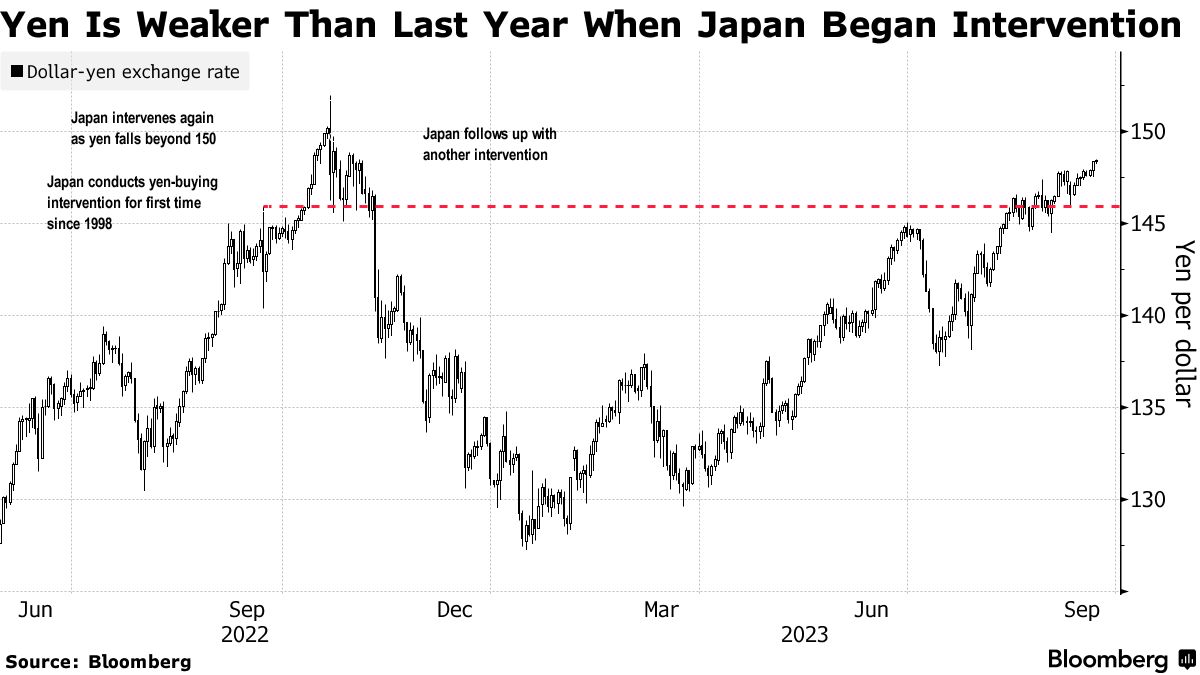
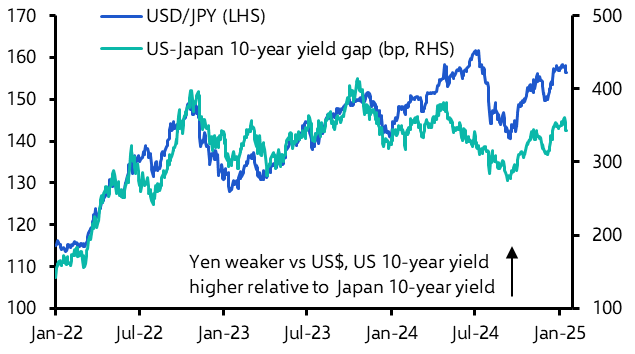
Yen movements are driven by a mix of Bank of Japan policy shifts, US Federal Reserve decisions, and broader risk sentiment across global markets. The yen has spent years weak due to Japan's persistently low interest rates while the Fed raised rates aggressively. That widened gap pushed the yen below 150 for a stretch that most people still remember vividly. When the BOJ finally signaled a rate hike in early 2024, the yen bounced sharply, and every yen-denominated asset someone was watching suddenly became more expensive in dollar terms. For personal conversions under 100,000 yen this volatility barely registers. On 100 million yen, a five-cent move in the exchange rate costs you $50,000. That means timing and execution matter far more than they do for smaller amounts. If you need to convert on a specific date, blocking the rate through a forward contract or a limit order with your provider is worth the extra step. It removes the gamble entirely. Another thing people routinely overlook is that the conversion rate depends heavily on the direction of the transfer. Converting yen into dollars is one thing. Converting dollars into yen is another, and some providers quote different spreads depending on which way the money flows. On high volumes, this can create a noticeable arbitrage-like discrepancy between what you pay to buy yen versus what you receive when selling it. It is not illegal, just annoying, and it is something you should check before committing to a single provider.
Get the Full Details
Practical Ways to Execute the Conversion
Bank wire transfer: This is the most common route, especially if your client already banks with a major institution. It is reliable but typically the most expensive due to wider spreads and occasional outgoing wire fees. Processing time ranges from one to three business days depending on whether both banks are in the same country and whether compliance review triggers delays. I have seen a 100 million yen transfer held for an extra two days simply because the receiving bank flagged the source of funds. Specialized FX brokers: Companies like OFX, TransferWise (now Wise), and others that focus on currency conversion tend to offer tighter rates, especially at higher volumes. Most will assign you a dedicated account manager once you move past a certain threshold, which makes communication significantly smoother. You also get rate alerts and the option to set a target rate so the conversion happens automatically when the market hits your number. Cryptocurrency routes: Some people convert yen to USDT or USD on a Japanese exchange like bitFlyer or GMO Coin, then move it offshore. This can be faster and occasionally cheaper depending on the spread at the moment, but it introduces regulatory risk, tax reporting complexity, and the fact that not every jurisdiction treats crypto proceeds the same way as fiat. It is a viable shortcut for some situations but a liability trap for others. Do not skip the tax consultation.
Common Mistakes That Cost Money
The first mistake is looking at the rate on a Sunday evening and assuming that is the rate you will get on Monday morning. Markets move, and the rate you saw on Friday close can shift before your provider even opens for the week. Always confirm the rate at the moment you lock in the conversion. The second mistake is ignoring the all-in cost. A provider might advertise a "no fee" conversion, but if their spread is two cents wider than the market rate, you are paying that difference in hidden cost. On 100 million yen, two cents per dollar is $200,000 in lost value. Always compare the actual rate you receive, not the marketing copy. The third mistake is assuming a single conversion is always the right call. If you need to move 100 million yen over a period of weeks or months, splitting it into multiple smaller conversions can reduce your exposure to rate swings. Dollar-cost averaging is usually discussed in the context of buying assets, but the same logic applies here. You smooth out the average rate instead of betting everything on a single snapshot.
There is also the matter of tax implications. If you are converting yen that represents capital gains, rental income, or proceeds from a sale, the currency conversion itself may trigger a taxable event depending on your jurisdiction. Japan taxes worldwide income for residents, and the United States does the same for citizens and residents. The gain or loss on the currency conversion can factor into your tax liability. This is not something to figure out after the fact.
When This Approach Falls Apart
Large conversions are not frictionless. Some providers impose limits or require additional documentation for amounts above a certain threshold. Anti-money laundering checks can delay transfers, especially if the source of funds is not immediately obvious from your account history. I once watched a perfectly straightforward conversion get held up for four business days because the sending bank wanted notarized documentation proving the origin of the yen. It was from a legitimate property sale, but the paperwork trail was messy enough that the bank played it safe. If speed is your priority and you cannot afford a multi-day hold, a bank wire may not be the best option. In those cases, a specialized FX broker with an established relationship and pre-cleared documentation often processes faster because they have already done the compliance legwork upfront. The trade-off is that setting up that relationship takes time, which circles back to why planning ahead matters. The other hard limitation is that no conversion method eliminates risk entirely. Rates can move against you between the time you decide to convert and the time the trade executes. Even with a locked-in rate, execution is not always instantaneous. Slippage is minimal on major pairs like USD/JPY, but it is not zero, particularly if you are moving a large amount during a volatile period.
The bottom line is that converting 100 million yen to dollars is straightforward in theory and complicated in practice. The math is trivial. The execution is where the money gets made or lost. Focus on the effective rate you actually receive, compare providers on that basis, understand the fee structure, and do not treat a large FX conversion like a small purchase where convenience outweighs cost. At this scale, convenience is expensive.