What a 1040 Calculator Actually Does for You
A 1040 Calculator is a digital tool that walks through the US individual income tax return, Form 1040, and figures out your taxable income, tax liability, credits, and refund or amount owed. It replaces the old method of manually plugging numbers into tax brackets and doing arithmetic by hand. Most people who use one are filing their own returns and want to avoid the $150–$400 you'd pay a preparer for a straightforward return. The calculator handles the bracket math, standard deduction phasing, credit phase-outs, and the actual multiplication steps that trip people up.
How to Use a 1040 Calculator Step by Step
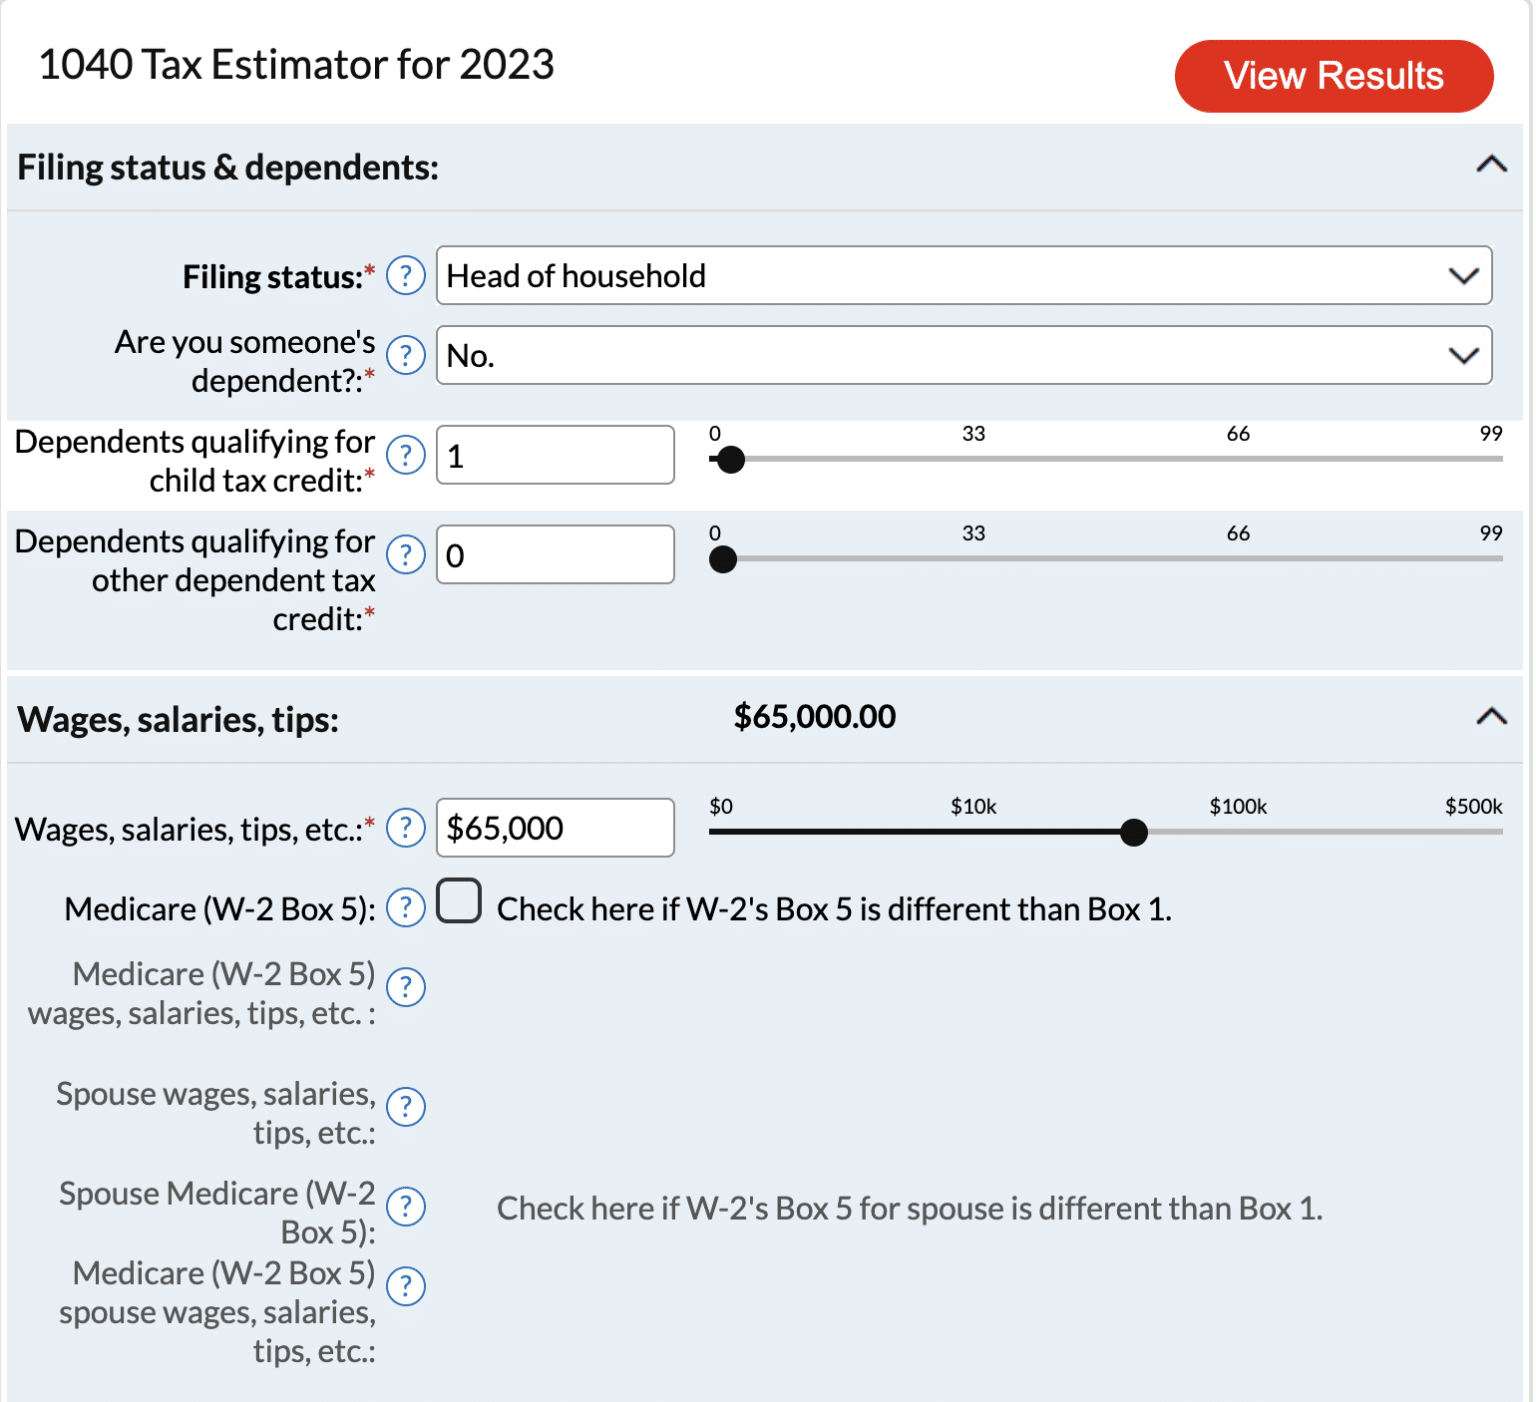
Start by gathering your W-2s, 1099s, and any records of deductions or credits. Open the calculator and enter your filing status first. This changes everything downstream — the standard deduction amount, the bracket thresholds, and which credits you qualify for. Input your gross income: wages, interest, dividends, business income, IRA distributions. The calculator will sum these into your total income. Then it subtracts adjustments — things like student loan interest, HSA contributions, or SEP-IRA deductions — to arrive at adjusted gross income, or AGI. AGI is the single most important number on the form. It determines your phase-outs for most credits and itemized deductions. From there, choose between the standard deduction and itemizing. For most taxpayers in 2024 and 2025, the standard deduction is significantly higher than typical itemized deductions. A married couple filing jointly gets $29,200 in 2024 and $29,400 in 2025. That's before any age or blindness additions. If your mortgage interest, state and local taxes, and charitable contributions combined don't clear that threshold, itemizing wastes time and doesn't lower your tax.
The calculator then computes taxable income, applies the correct tax brackets, adds any additional taxes like self-employment tax or the net investment income tax, subtracts credits, and gives you the final number. Compare it against your total withholding and estimated payments. The difference is your refund or what you owe.
Get the Full Details
Common Pitfalls I've Run Into
I spent two years building and testing a 1040 Calculator internally before I stopped trusting my own spreadsheet work. One thing I learned the hard way: most calculators and spreadsheets get the AMT (Alternative Minimum Tax) wrong on the first pass. AMT isn't simply a second calculation — it's a parallel system with its own exemptions, rates, and preference items. If you have large stock option exercises, significant state tax refunds, or depreciation from a rental property, skipping the AMT check can understate your tax by thousands. Another issue is the phase-out stacking. Credits like the Child Tax Credit, Saver's Credit, and deduction phase-outs like Itemized Deductions (PEP was repealed but the concept still matters in certain situations) all interact with AGI thresholds. A calculator that only applies one phase-out at a time will give you the wrong answer if you're near multiple thresholds simultaneously. I've seen this happen when someone had both student loan interest phase-out and IRA deduction limits triggered in the same return. The order of operations matters, and most free calculators don't handle it correctly. If you're near the edge of a phase-out, run the numbers twice: once with the calculator, and once by hand or with a second tool. The discrepancy tells you something is wrong.
When a 1040 Calculator Isn't Enough
These tools are fine for W-2 employees with standard deductions and maybe a few 1099s. They fall apart when you have Schedule C business income with self-employment tax, Schedule E rental properties with passive loss rules, capital gains with wash sale adjustments, or foreign income with the foreign earned income exclusion. For those situations, the calculator becomes a guessing game because it can't model the interaction between forms. I keep TaxSlayer or TurboTax for anything beyond a simple return. They're not perfect either, but they carry the form logic that a standalone 1040 Calculator doesn't. The difference is maybe $50 in software cost versus an audit flag from getting the numbers wrong. At that point the math doesn't work in your favor.
A Real Workaround I Use
When I need to verify a return quickly, I use a free 1040 Calculator for the initial pass, then copy every line into a separate spreadsheet where I manually verify the bracket calculations. It takes about 20 minutes extra. I caught three errors last year this way — one was a misapplied earned income credit phase-out that would've cost me about $1,200 in overpayment. Not life-changing, but the kind of mistake that adds up over several years of filing. For people who file every year and have moderate complexity, spending ten minutes cross-checking the calculator result against a manual breakdown is the most reliable thing you can do. There's no shortcut that beats looking at the actual numbers.