Understanding Monthly Payments on a $140,000 Loan
People often call it in passing, but the exact term most calculators use is 140K Mortgage Payment when they're trying to figure out what their monthly outlay will look like. It is just a $140,000 principal amount, and the monthly number depends on the interest rate, the loan term, and whether taxes and insurance are bundled in or paid separately. Here is what I actually saw recently. A borrower came to me with a 30-year fixed at 6.5% and wanted to know the payment. The math is straightforward enough that you can do it by hand if you want, but I usually fire up a quick spreadsheet because it saves time when you have a whole queue of clients asking the same question. At 6.5% over 30 years, the principal and interest alone comes out to about $885 per month. Add property tax and homeowners insurance, which vary wildly by location, and you are probably looking at somewhere between $1,050 and $1,300 total monthly payment depending on where the house sits. If the property tax rate in that county is high, say over 2.5% of assessed value, your escrow portion alone could eat another $200 to $300 a month.
I worked with a client last fall who had a $140,000 loan at 7.25% for 30 years. Her P&I was roughly $957. She assumed her total payment would be around $1,100 based on old numbers from a different state. It turned out her escrow was $480 per month because her local tax rate and insurance premiums were significantly higher than she remembered. The gap between what she expected and what she actually owed was enough to make her almost back out of the purchase. We adjusted her budget and found a slightly longer amortization path through an 8-year ARM with a rate buydown, which dropped her initial payment by about $110 for the first two years. That gave her breathing room while she sorted out the long-term numbers. The thing most people miss is that the rate you see advertised is rarely the rate you get locked in at. There are points, lender credits, origination fees, and third-party add-ons that shift the effective cost. A 7% rate with one point costs you about $1,400 upfront and lands you a slightly lower monthly payment. A 7.25% rate with lender credits might actually save you money over five years if you plan to refinance or sell before the break-even point. You need to calculate the net present value of those choices, not just compare monthly payment screenshots.
How to Calculate It Yourself
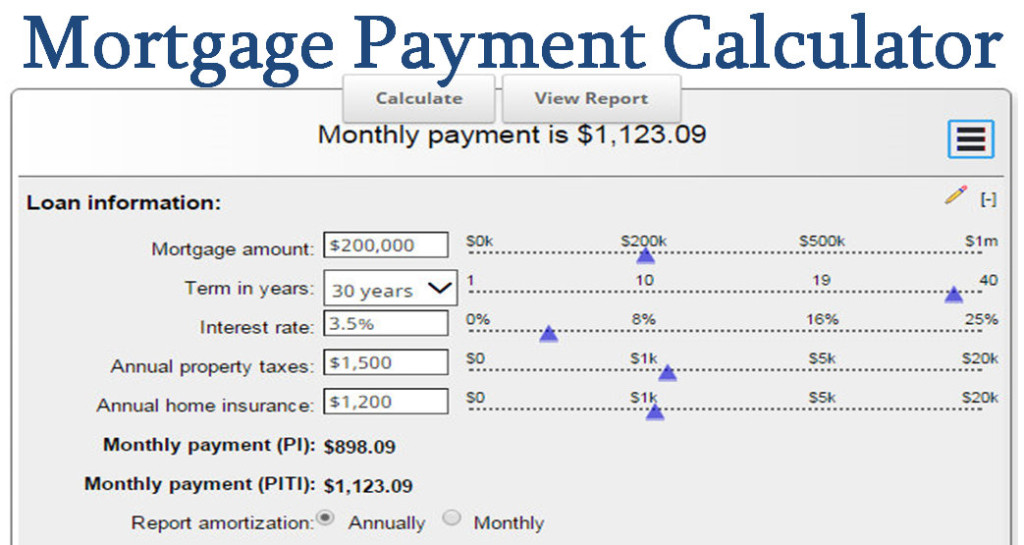
The formula is standard textbook stuff: monthly payment equals the principal times the monthly rate, divided by one minus one over one plus the monthly rate raised to the total number of payments. In practice I just use a spreadsheet with the PMT function because it handles negative signs and decimal precision without me second-guessing my own arithmetic. For a $140,000 loan at 6% over 30 years, the PMT function gives you approximately $839.37 in principal and interest. That number does not include escrow, HOA dues, or mortgage insurance. If your down payment was less than 20%, you will likely have PMI added on, which for a $140,000 loan might run another $50 to $90 per month depending on the lender and your credit tier. I ran into a situation once where a borrower was quoted a 140K Mortgage Payment figure that looked suspiciously low. It turned out the lender had only quoted the P&I and omitted the PMI completely. When the third disclosure packet arrived with the PMI line item included, the actual total jumped by about $75 a month. The borrower had been budgeting against the lower number for weeks. I learned to always ask for the full PITI estimate before anyone gets attached to a payment figure, and I now require my team to pull the HUD-1 or Closing Disclosure draft before any verbal commitment is made.
Get the Full Details
Another thing nobody talks about enough is the difference between the note rate and the APR. The note rate is what determines your payment. The APR factors in fees and gives you a truer picture of cost, but it can be misleading if you are planning to move in three years. In that case the note rate and monthly payment matter far more than the APR does. If you are staying put for ten years or more, the APR becomes a much more useful comparison tool between lenders.
When a 140K Mortgage Payment Doesn't Work for You
Sometimes the numbers just do not add up. If you are looking at a $140,000 loan and the monthly payment after escrow pushes your debt-to-income ratio over 43%, conventional financing becomes difficult. In those cases I usually recommend exploring FHA loans, which allow higher DTI ratios up to around 50% with strong compensating factors. The tradeoff is you will carry mortgage insurance for the life of the loan unless you refinance later. There are also scenario where refinancing makes more sense than holding a conventional loan. If you currently have a $140,000 balance at 8% and rates have dropped to 5.75%, the refinance saves you roughly $340 a month. But you need to run the break-even analysis including closing costs, which typically range from $2,500 to $5,000 on a loan of that size. At those numbers the break-even point sits around eight to fourteen months. If you are not planning to stay in the home past that window, the refinance is not worth the paperwork and cost. One edge case that comes up more often than you would think involves VA and USDA loans. These programs sometimes allow zero down payment on a $140,000 purchase, which dramatically changes the payment calculation because you are not financing closing costs into the loan balance. A veteran I worked with last spring bought a $140,000 home with no down payment through VA lending. His monthly payment including funding fee amortized over the loan term was still under $900 P&I at the current rate environment, and he avoided PMI entirely. That is a meaningful difference compared to a conventional loan with the same principal amount.
If you want to dig into the numbers yourself, there are several free calculators online that handle this type of computation. I tend to use ones that let you toggle escrow and PMI separately because the all-in-one calculators often make assumptions that do not match your actual situation. The Department of Housing and Urban Development maintains a reasonably accurate calculator, and the Consumer Financial Protection Bureau has a tool that pulls from actual loan estimates to give you a more realistic picture.

Practical Steps Before You Sign Anything
Get pre-approved, not just pre-qualified. The difference matters because pre-approval means a lender has reviewed your financial documents and committed to a specific loan amount and rate range. Pre-qualification is basically a casual estimate that can change at any moment. I have seen buyers lose contracts because they walked into an offer with a pre-qualification letter while the competing bidder had a solid pre-approval on file. Lock your rate as soon as you are confident in the numbers. Rate locks typically last between 30 and 60 days, and extending them usually costs extra. If you lock too early and your closing date slips, you end up paying extension fees. If you lock too late and rates move against you, your payment increases and your budget gets squeezed. I recommend locking when you have a fully executed purchase contract and the closing timeline is set in stone. Shop at least three lenders. The same $140,000 loan can have different closing costs, different rate sheets, and different service quality depending on who you go through. One lender might charge $3,200 in origination fees while another charges $1,800 for essentially the same product. That difference shows up in your monthly payment over the life of the loan and in your out-of-pocket costs at closing. I always have my clients run a side-by-side comparison of the Loan Estimate forms, line by line, before making a final decision.
Read the fine print on rate buydowns. Some lenders offer temporary buydowns where your rate is reduced for the first one or two years. This can make a 140K Mortgage Payment feel much more manageable initially, but you need to understand what the payment looks like once the buydown period ends. A 2-1 buydown might drop your payment by $150 in year one and $75 in year two, then jump up significantly in year three. If your income does not scale to meet that increase, you are set up for a painful surprise. The bottom line is that a $140,000 mortgage is a very common loan size and there is plenty of data available to help you understand exactly what you are getting into. The key is to look past the headline monthly payment number and examine the full picture including fees, insurance, taxes, and how long you plan to hold the loan. Most mistakes I see people making come from focusing on the wrong number in the wrong place at the wrong time.