How the Math Actually Works Before You Even Open a Calculator
A mortgage calculator is just a tool that applies the standard amortization formula to your specific numbers. The formula itself hasn't changed in decades. What changes is how people interpret the output. Most folks run a 15 vs 30 Year Mortgage Calculator and stare at two monthly payment figures without understanding what sits underneath them. The real difference between those two loan terms isn't just the payment size. It's the total interest paid over the life of the loan and how quickly you build equity. I've run these calculations for clients and for myself on projects going back to the mid-2000s. The one thing I can tell you right now is that most people underestimate how much the interest rate differential matters. A 15-year loan doesn't always come with a meaningfully lower rate than a 30-year. When it doesn't, the math starts looking a lot less favorable than you'd expect.
Using a 15 Vs 30 Year Mortgage Calculator Without Messing It Up
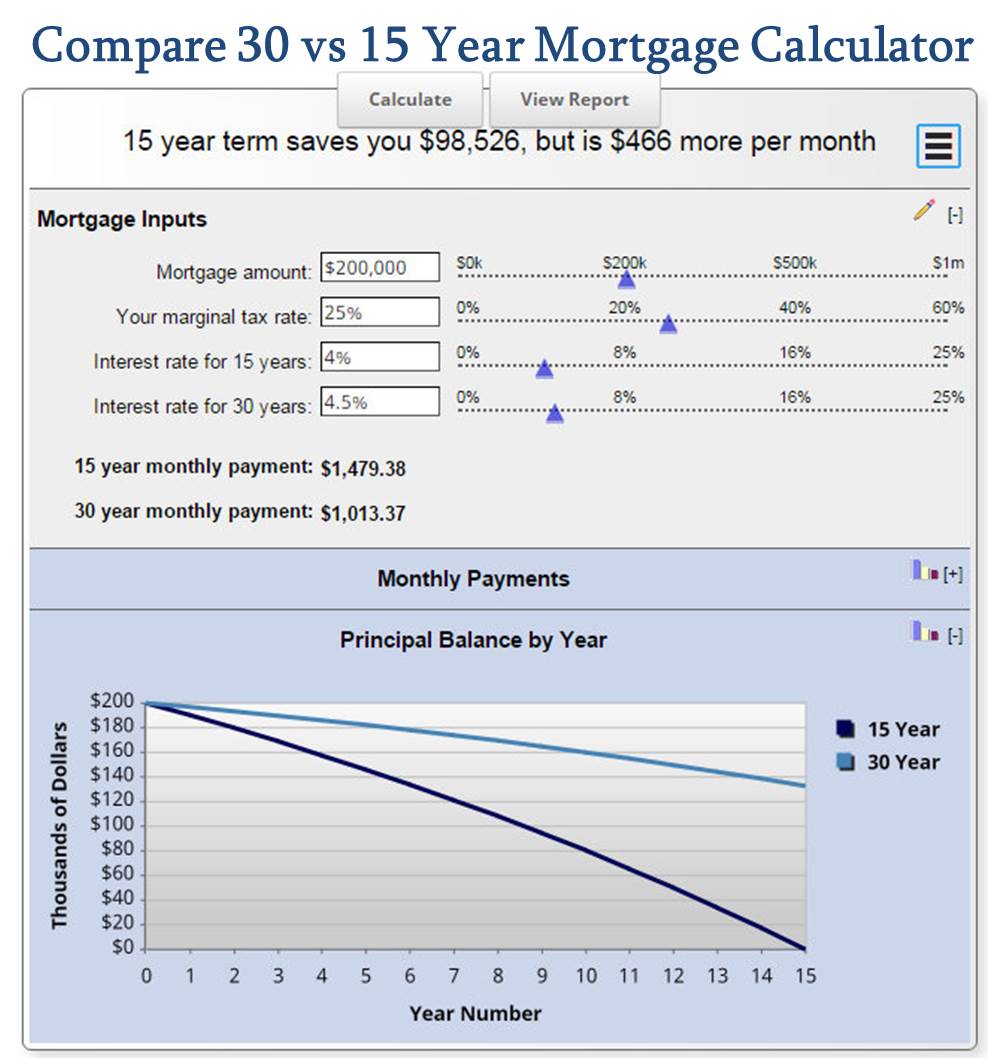
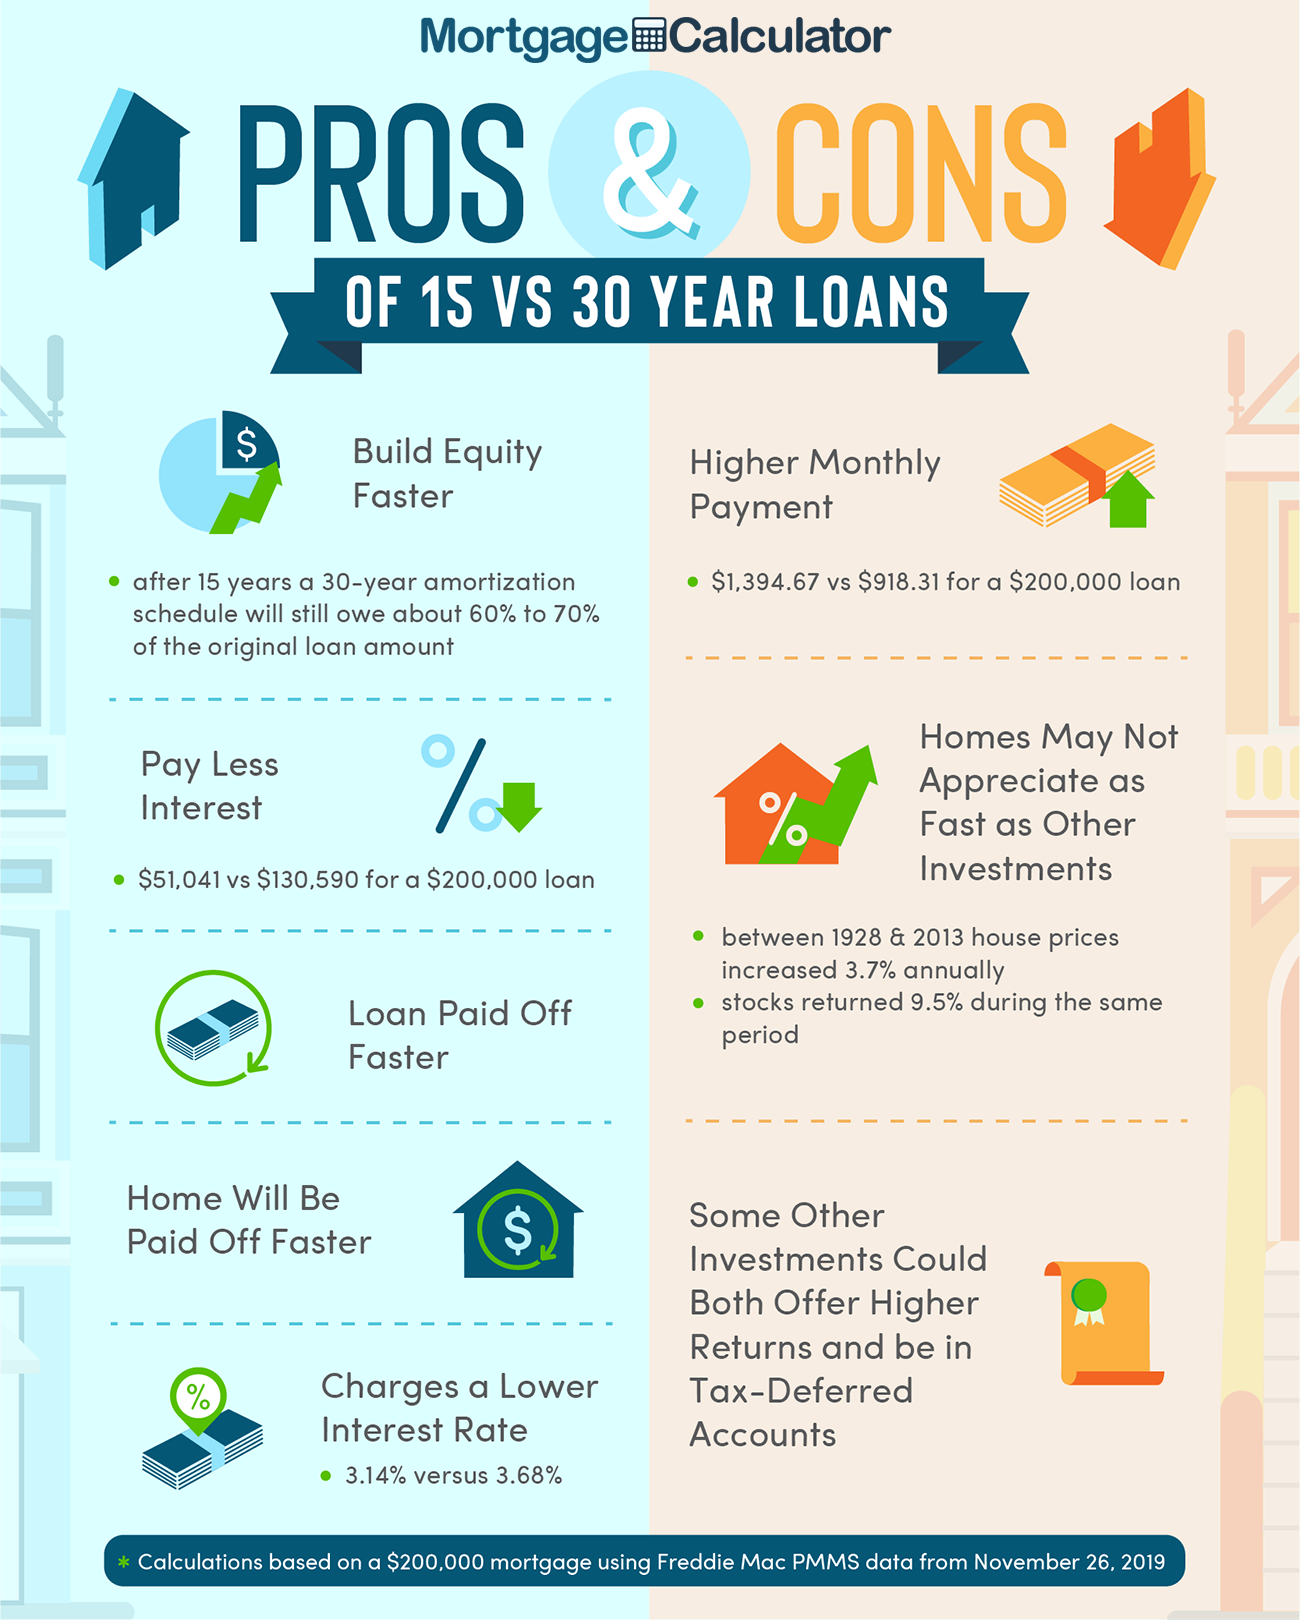
Here's the straightforward process. You need four inputs: the loan amount, the interest rate, the loan term, and your starting date if you want an amortization schedule. Plug those into the calculator and hit compute. The output will show your monthly principal and interest payment, total interest paid, and total amount paid over the life of the loan. Some calculators also break down the year-by-year amortization, which is where things get interesting. The tricky part comes when you're comparing the two side by side. The 15-year payment will be noticeably higher, sometimes dramatically so. The instinct is to look at that higher payment and walk away. But you need to look at the total interest column instead. That number tells the real story. On a 30-year conventional loan at current rates, you can easily pay more in total interest than the original principal amount. That's not a typo. It happens routinely on jumbo loans and on purchases in expensive markets. Let me give you a concrete example. Say you're financing $400,000. At 6.5% over 30 years your monthly payment comes to roughly $2,528. Total interest paid over the full term lands around $510,000. Switch to 15 years at 6% and your monthly jumps to about $3,375. Total interest drops to roughly $207,000. You're paying nearly $1,000 more per month but saving over $300,000 in interest. The trade-off is real and it only works if your cash flow can absorb the higher payment consistently.
The Edge Case Most Calculators Don't Warn You About
Last year I was helping a client compare these two options on a $650,000 loan. The calculator showed the 15-year would save about $180,000 in interest. Sounds great on paper. But when I pulled their actual debt profile, they had a car payment, student loans, and a variable-rate credit line they were carrying. The higher 15-year payment would have pushed their debt-to-income ratio to the edge of what lenders would approve for a refinance down the road. We ended up going 30-year and they made extra principal payments on their own schedule instead of being locked into a payment that left no room for error. The calculator couldn't account for that because it doesn't know your other debts. This is the blind spot with these tools. They treat the mortgage in isolation. In practice your housing payment exists inside a much messier financial ecosystem. You have emergency funds to maintain, retirement contributions to keep funding, and other obligations that don't vanish just because you picked a shorter term.
Get the Full Details
Advanced Nuances Beginners Miss Every Time
One thing nobody talks about enough is the front-loading of interest. In the early years of a 30-year mortgage, the vast majority of your payment goes toward interest rather than principal. In the first five years of a $400,000 loan at 6.5%, you'll pay roughly $158,000 in interest and only about $35,000 toward principal. That's not a bug in the math. It's how amortization works by design. The 15-year flips this dynamic significantly because the principal portion starts much larger from month one. Another nuance involves rate lock strategies. Lenders sometimes price 15-year loans with a smaller rate discount compared to 30-year loans than they did ten years ago. In certain markets the spread between the two has compressed to half a percent or less. When that happens the total interest savings shrink considerably and the higher monthly payment becomes much harder to justify. Always verify the actual rate quote for both terms from your lender rather than assuming the 15-year comes with a meaningfully better rate. There's also the tax angle to consider if you're in the United States. Mortgage interest deductions on Schedule A favor the 30-year loan simply because you pay more interest in the early years. For high earners itemizing, this can create a meaningful after-tax difference that a basic calculator won't show you. Factor in your marginal tax bracket and see what the real net cost looks like.
When the Calculator Output Should Make You Walk Away From a 15-Year
I've seen too many people commit to a 15-year payment and then face hardship when income gets disrupted. The payment is fixed. The term is fixed. Your job situation might not be. If you're a contractor, commission-based, or working in an industry with known volatility, the safety margin of a 30-year payment matters a lot more than the interest savings. I had a client who took the 15-year on a $500,000 loan during a booming market and then got laid off six months later. He had to refinance back to a 30-year just to keep the house, which erased most of his projected savings and came with closing costs. That's a real scenario and it happens more often than you'd think. The calculator will never flag this risk. It shows you the best case numbers and assumes you'll make every payment on time for fifteen years straight. Life doesn't work that way. If you can't comfortably carry the 15-year payment with a solid emergency fund still intact, the shorter term isn't helping you. It's trapping you.
What to Look for in a Decent Calculator
Not all online tools are created equal. A proper calculator should show you the amortization schedule, not just the monthly payment. It should allow you to input extra principal payments so you can model what happens if you pay additional money toward the loan each month. It should let you adjust the interest rate in real time since rates shift weekly. If the tool you're using only gives you one static number without any ability to tweak variables, you're not getting a useful comparison. You're getting an approximation at best. The ones that include an early payoff scenario are the most valuable. Say you want to see what happens if you switch from a 30-year to paying it off in twenty years through extra principal. Good calculators let you model that. Bad ones don't. The difference between a good tool and a bad one here is roughly fifteen minutes of your time versus twenty minutes of fiddling with spreadsheets yourself.

The Bottom Line Without Fluff
A 15 vs 30 Year Mortgage Calculator is useful for giving you a baseline. It's not useful for making the decision for you. The numbers it produces are correct within their own narrow frame. But your actual financial situation includes variables the calculator can't see. Your income stability, your other debts, your tax situation, your emergency savings, your retirement timeline, your risk tolerance. Those matter more than the difference in total interest on paper. If the higher 15-year payment fits comfortably within your budget and you have at least six months of expenses saved, the shorter term makes mathematical sense. If it stretches you thin or wipes out your buffer, the 30-year with optional extra payments is the smarter move. The calculator can't tell you that. You have to figure that out yourself.