How a 15-Year Mortgage Rate Calculator Actually Works
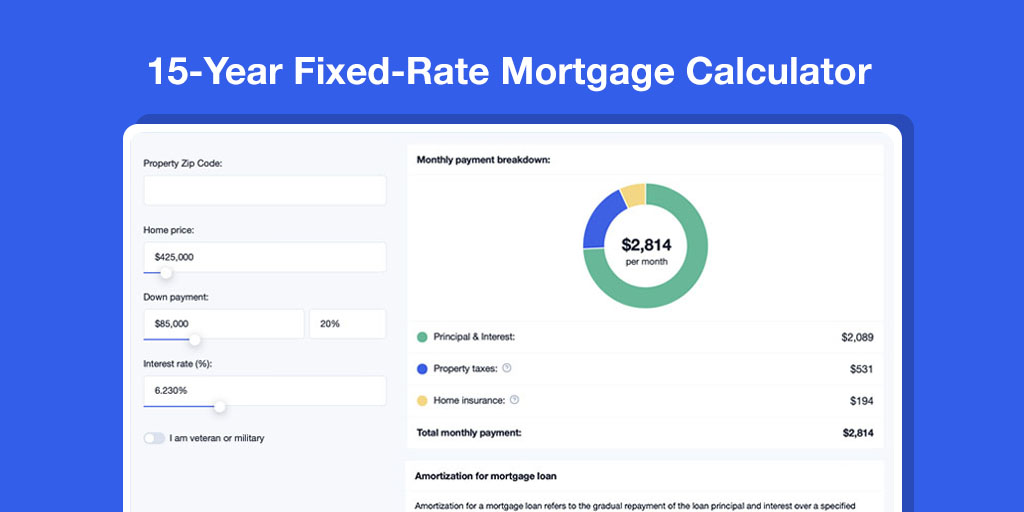
A 15 Year Mortgage Rate Calculator is a straightforward tool that takes your loan amount, interest rate, and term length, then outputs your monthly payment. But the reality of using one well goes beyond just plugging in numbers. The formula behind it is the standard amortization equation: M = P[r(1+r)^n]/[(1+r)^n-1], where P is principal, r is monthly interest rate, and n is number of payments. Most online calculators handle this without issue, but they don't always tell you what matters most. I spent years underwriting loans before moving to the advisory side, and I've seen people make the same mistakes over and over. Here's what actually happens when you run a real calculation. Let's say you're looking at a $250,000 loan at 5.5% over 15 years. Your payment works out to roughly $2,035 per month. That's the number the calculator gives you, and it's correct. But it doesn't include property taxes, homeowner's insurance, or PMI, which can add $400 to $900 depending on your location and down payment.
Using a 15 Year Mortgage Rate Calculator Without Wasting Time
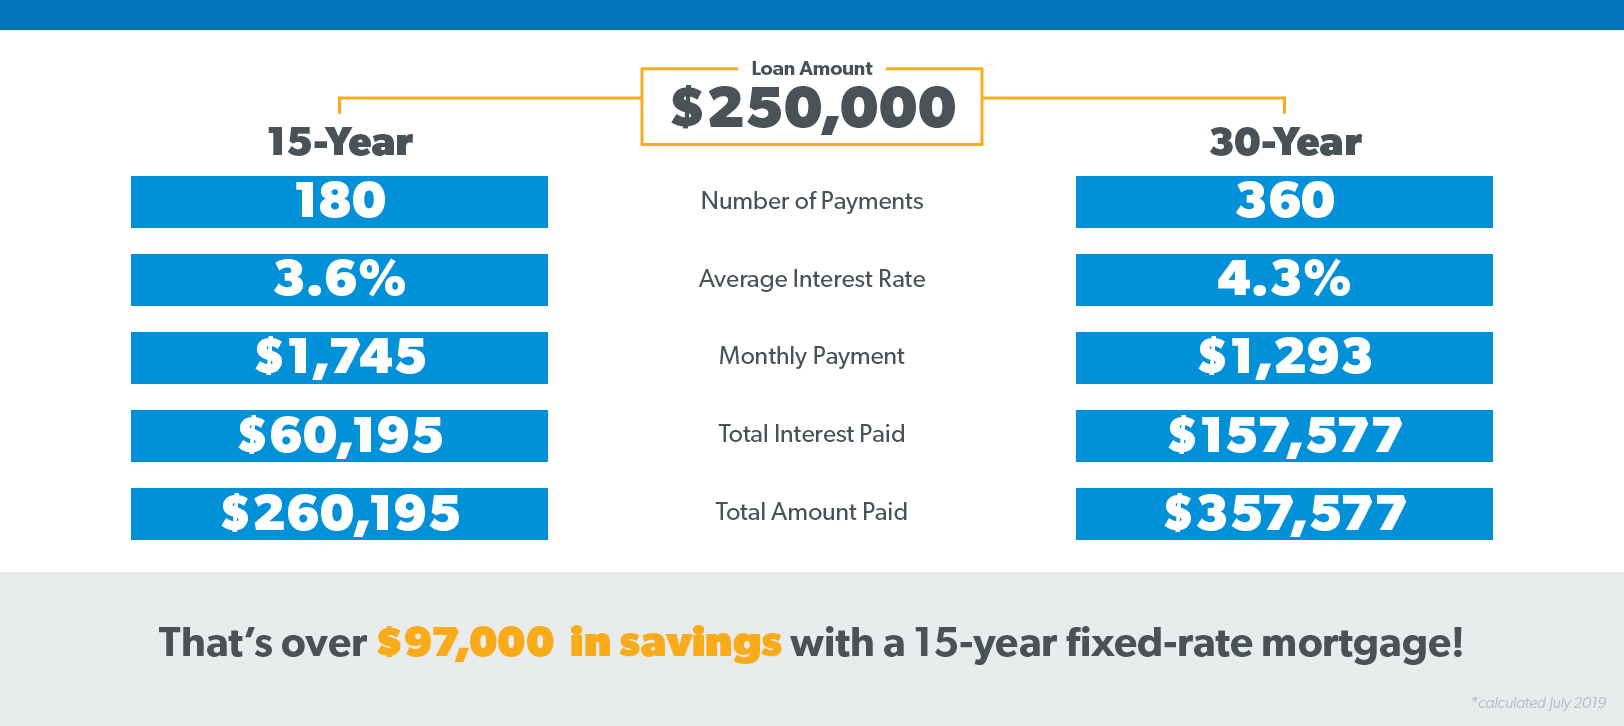
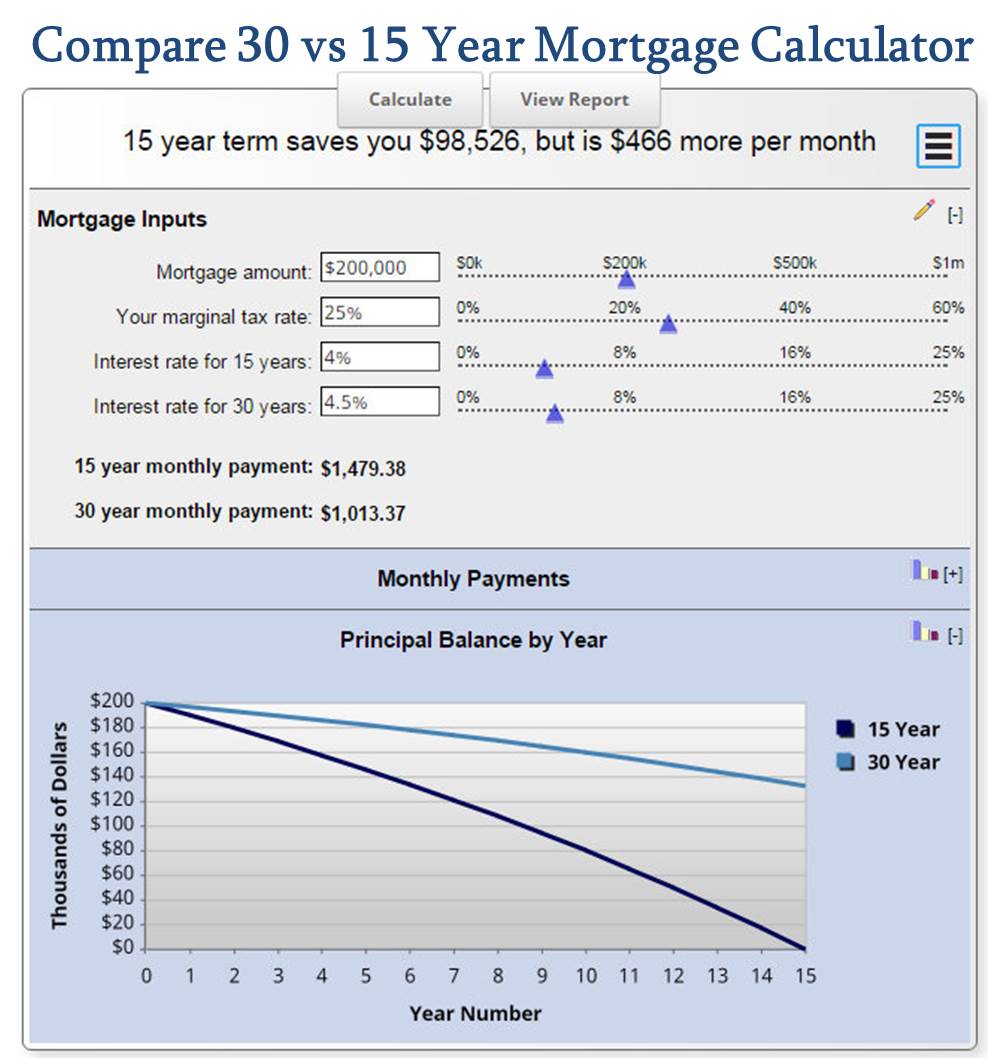
The best calculators let you toggle between rates quickly so you can compare scenarios. I recommend running at least three rate points through the same calculator—your current rate, one point lower, and one point higher. This shows you how sensitive your payment is to rate changes, which most people ignore until it's too late. One thing almost no one accounts for: the difference between the quoted rate and the APR. Lenders advertise the interest rate, but the APR folds in closing costs, points, and other fees into an annualized figure. A loan at 5.25% with two discount points could have an APR closer to 5.6%. The calculator shows you the payment based on the interest rate, but the APR is what determines your true cost. I learned this the hard way when a borrower came to me furious that his "low rate" loan wasn't saving him anything compared to a slightly higher rate with fewer fees. Here's a practical trick. If your calculator has an extra payment field, run the numbers with an additional $200 per month. On a $250,000 loan at 5.5%, that extra $200 slashes roughly three years off the term and saves about $18,000 in total interest. That's the power of the 15-year structure—you can accelerate payoff without refinancing or changing your loan type.
Another edge case worth noting. Some calculators use a 360-day year and others use 365. It's a small difference, usually $2 to $5 per month, but it compounds over the life of the loan. If you're comparing quotes from two lenders, make sure their calculations use the same day-count convention. I once had a client try to choose between two offers that appeared identical on the surface, but one used a 30/360 method and the other used actual/365. Over 15 years, the difference was about $340 in total interest, and it took me ten minutes of recalculating to show him which was actually cheaper.
Get the Full Details

What the Numbers Don't Tell You
A 15 Year Mortgage Rate Calculator will give you a clean monthly payment, but it won't warn you about rate lock expiration, which is typically 30 to 60 days. If your closing drags past that window, you could lose your quoted rate and take a hit of 0.125% to 0.375%, which on a $300,000 loan adds roughly $45 to $130 per month. Factor in time for appraisal, underwriting, and title work when you're planning your rate lock. There's also the issue of biweekly payments. Many people think switching to biweekly automatically halves the monthly payment, but it doesn't. Biweekly means paying half your monthly payment every two weeks, which results in 26 half-payments or 13 full payments per year instead of 12. That one extra payment per year reduces a 15-year loan to about 13 years and cuts interest significantly. But not all servicers handle this correctly. I've seen two instances where the biweekly program added fees or misapplied payments, costing borrowers nothing but creating confusion. Down payment size changes everything in the 15-year space. Because the payments are already high, putting less than 20% down triggers PMI, and on a 15-year loan PMI can cost more upfront than on a 30-year because the loan pays off faster and there's less time for it to drop off. Some lenders bundle PMI into the payment, others require a separate premium. Run both scenarios through your calculator to see the real difference.
The biggest limitation of any mortgage calculator is that it assumes a fixed rate. If you're looking at an ARM or a adjustable product, the numbers change after the initial period. Even within fixed-rate space, some loans have rate locks that expire, and some lenders offer teaser rates that reset after a set period. Always read the Loan Estimate document, not just the calculator output. The actual terms can differ from what the tool shows, especially if there are lender credits, seller concessions, or special programs involved. If you want something more reliable than a free online calculator, I'd suggest using a spreadsheet with the PMT function. It takes five minutes to set up and gives you full control over assumptions. Type =PMT(rate/12,terms,-principal) and you get the exact payment. From there you can layer in tax estimates, insurance, and extra payments without the calculator making hidden assumptions about how it rounds or calculates days.