Reading the 1929 Crash Without the Hollywood Filter
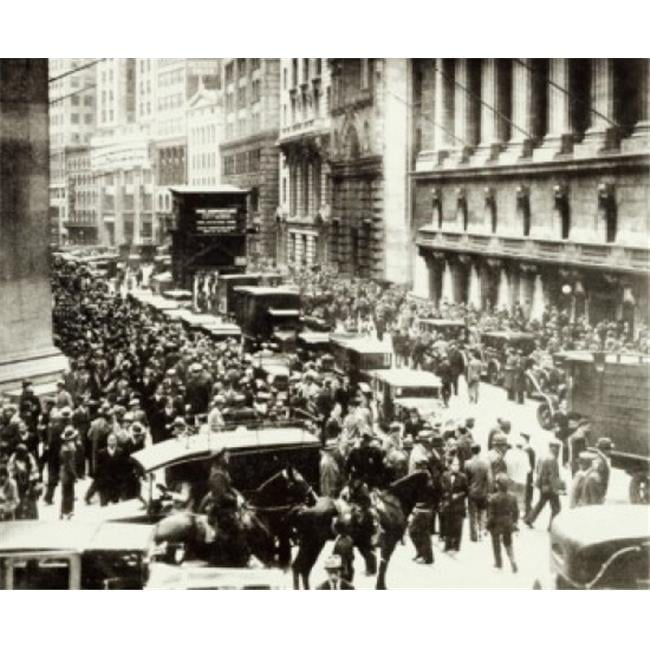
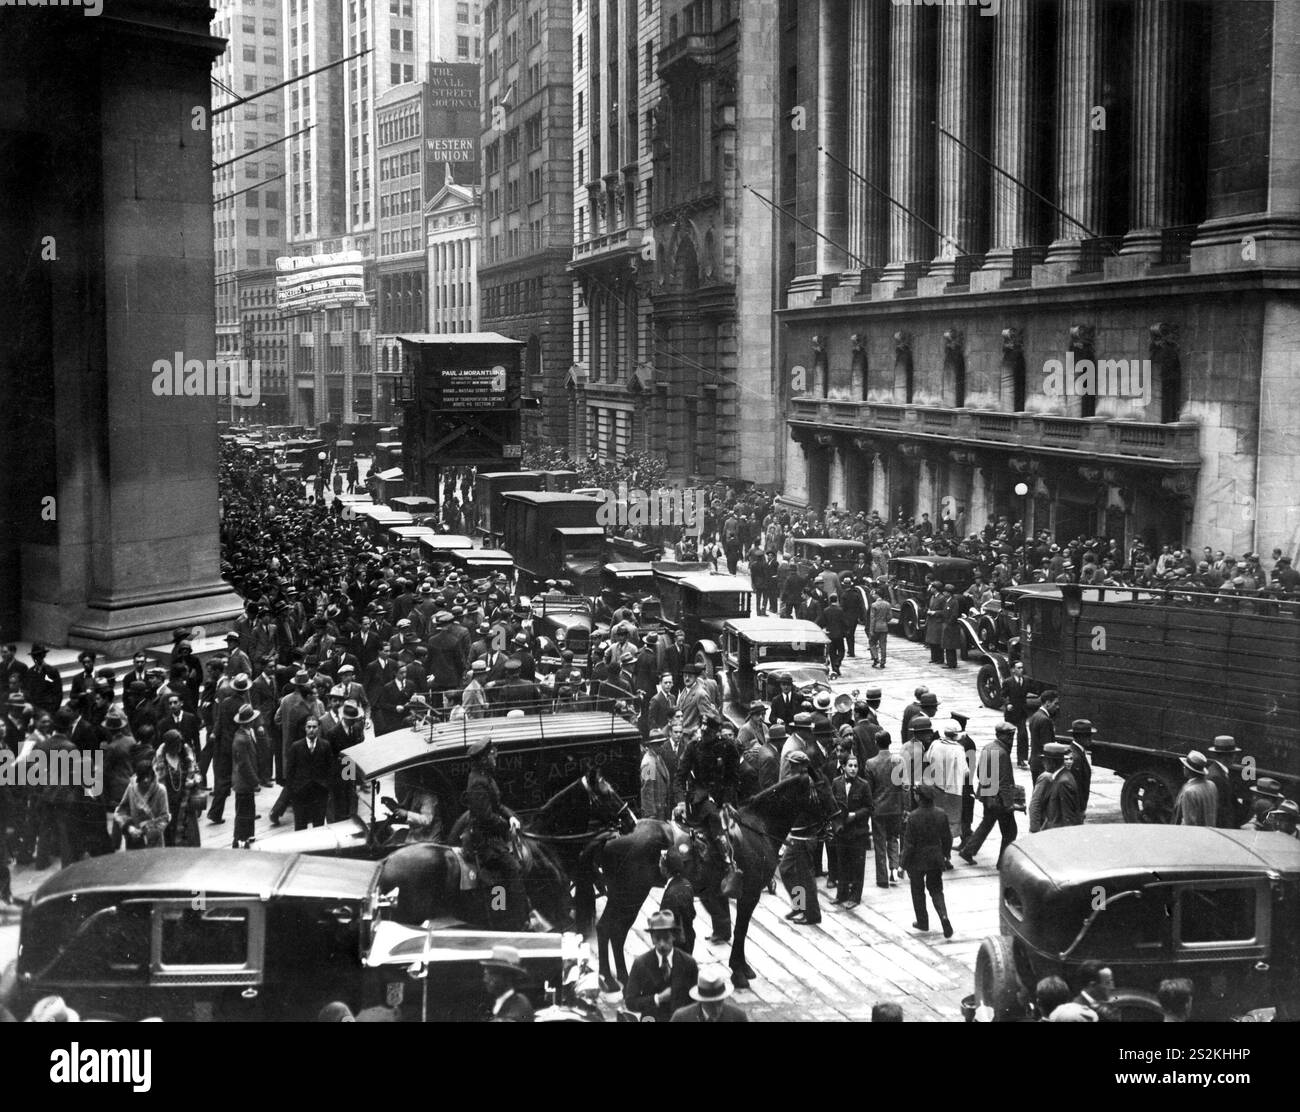
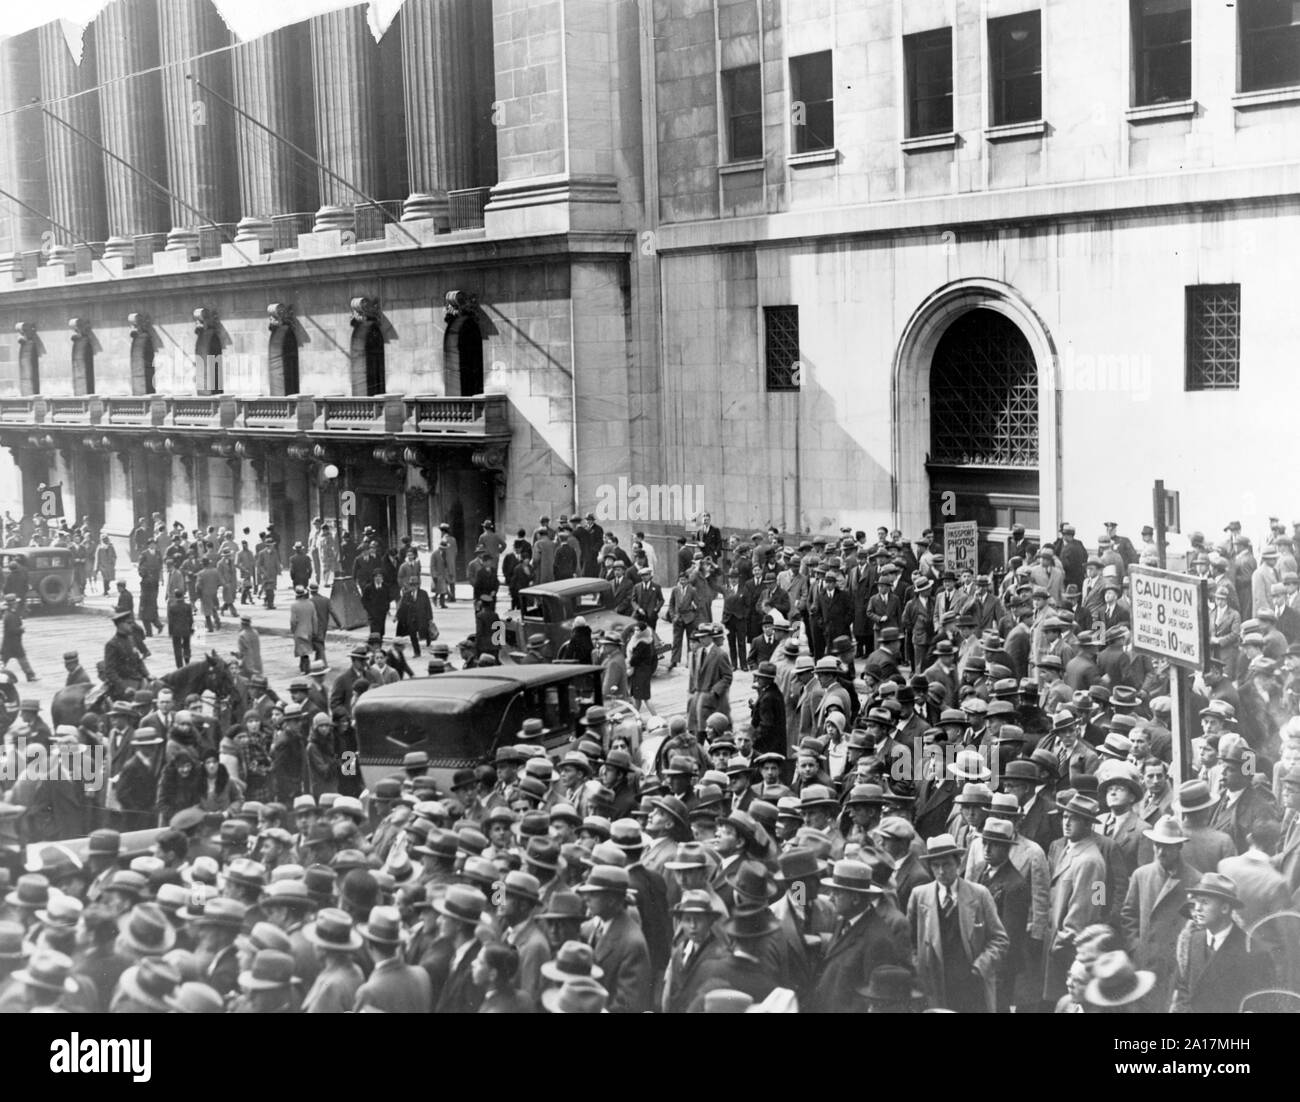
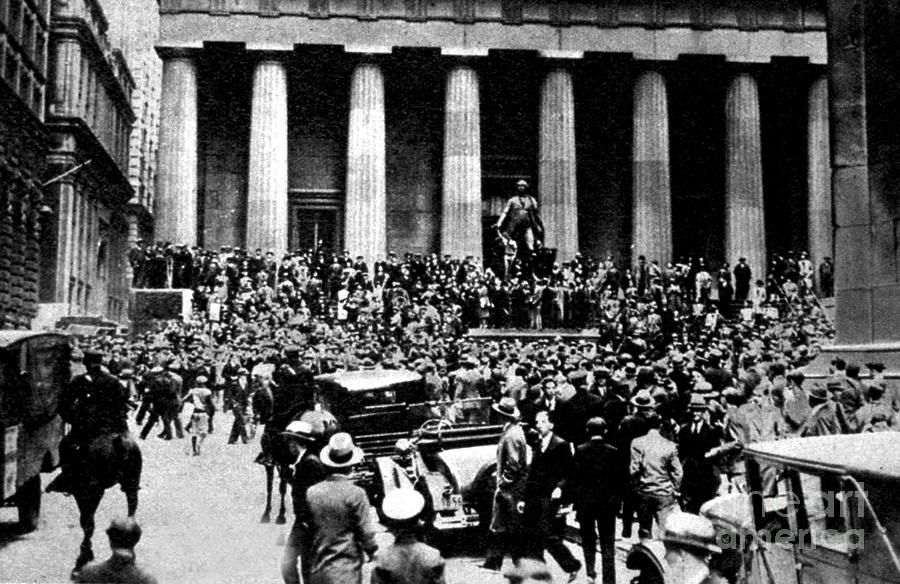
Most people think they understand the 1929 Wall Street Stock Market Crash because they've seen the black-and-white footage of panicked traders and the famous photo of the guy sitting on the ledge. The reality is far more bureaucratic and far less dramatic. It was a slow bleed that turned into a sudden rupture, driven by structural problems most investors at the time didn't even realize they had. Here's the thing nobody emphasizes enough. The crash wasn't one event. It was three distinct selling waves over six trading days in late October. The first major collapse hit on October 24, known later as Black Thursday. That day saw a record 12.9 million shares traded. A group of Wall Street banks, led by Richard Whitney of J.P. Morgan & Co., tried to prop up prices by making large buy orders. It bought steel shares at $205, above the market price, just to signal confidence. The gesture bought two days of calm before everything fell apart again. October 28 was Black Monday. The Dow dropped 38.3 points, roughly 13 percent. October 29, Black Tuesday, is the day everyone remembers. The Dow fell another 30.5 points on 16.4 million shares. But the damage had already been done. Margin calls were being issued across the board, and brokers were liquidating positions faster than buyers existed.
The margin system is where this all goes wrong. In the 1920s, you could buy stocks with as little as 10 percent down. You borrowed the other 90 percent from your broker. When prices started falling, brokers called in those loans. Investors had to sell immediately to cover the debt, which pushed prices lower, which triggered more margin calls, which forced more selling. It was a mechanical death spiral with no circuit breakers, no SEC, no deposit insurance. Just leverage amplifying panic in real time. I spent years researching portfolio drawdowns for institutional clients, and let me tell you, studying 1929 taught me more about risk management than any textbook. The problem I keep running into with people trying to apply lessons from 1929 to modern markets is that they miss the structural differences. There were no short-selling restrictions then. There were no circuit breakers. Markets just ran. Today, if the S&P drops 7 percent in a day, trading halts. That changes behavior dramatically. People still panic, but the mechanical acceleration of a pure margin spiral is much harder to reproduce now. Here's what beginners consistently get wrong about this period. They think the crash caused the Great Depression. It didn't. The Depression was already brewing from Federal Reserve policy errors, massive tariff legislation with the Smoot-Hawley Act of 1930, and a banking system that was structurally fragile with hundreds of undercapitalized single-bank branches. The crash accelerated the downturn and made it visible, but the underlying economic sickness was much deeper. You can crash a healthy economy, but a weak one will collapse on its own given enough pressure.
Another thing that gets glossed over. The media coverage at the time was almost entirely celebratory during the boom years. The New York Times published editorials calling the market a "permanently high plateau." Financial writers were echoing the general optimism of the era. When the tide started going out, nobody wanted to be the first to say they saw it. That collective silence is actually more dangerous than any panic. Panic is honest. Denial keeps the leveraged positions open until it's too late to exit. By November 1929, the Dow had fallen from its September high of 381 to around 198. That's a 48 percent decline in under two months. Some individual stocks were down 90 percent or more within weeks. But here's the uncomfortable part most people don't want to hear. Many of those stocks recovered to pre-crash levels within a few years, only to crash again in 1937 and not truly clear those levels until the mid-1950s. So the 1929 crash wiped out paper wealth, but the real destruction came from the sustained depression that followed, when businesses closed, unemployment hit 25 percent, and the wealth wipeout became permanent because the income stream behind those assets disappeared entirely. If you're looking at this from a modern investing perspective, the practical takeaway isn't about predicting the exact top. No one did. The practical takeaway is that leverage is the enemy during extended rallies. The longer the bull market runs without a significant correction, the more leveraged the average position becomes. By late 1929, an estimated 80 percent of trading volume was on margin. That's the signal most people ignored. When speculation becomes the dominant mode of participation, not investment, the foundation is sand.
Get the Full Details
I've advised clients through the dot-com burst, the 2008 financial crisis, and the early days of 2020. Each time, the pattern of denial followed by the pattern of forced selling is identical. The mechanism changes slightly with modern regulation, but human behavior under leverage doesn't. Understanding 1929 isn't about memorizing dates. It's about recognizing how a system built on borrowed money behaves when the borrowing stops working.
The Aftermath and Structural Changes
Congress responded with the Securities Act of 1933 and the Securities Exchange Act of 1934, which created the SEC and established the requirement for companies to publish audited financial statements before selling securities. These weren't ideal solutions, but they introduced transparency that barely existed before. Before 1933, a company could issue stock with whatever narrative it wanted and virtually no verification. Insider trading was commonplace and largely unregulated. The crash exposed how much of the 1920s rally had been built on speculation funded by borrowed money and sold on hope. The Glass-Steagall Act of 1933 separated commercial and investment banking, which was another direct response to the conflicts of interest that became obvious during the crash. Banks were taking depositors' money and gambling it in the markets. When the markets fell, depositors lost everything and there was no FDIC insurance yet. That part came in 1933 as well. Before that, bank runs were a regular feature of American economic life, and the crash made them dramatically more frequent. The human cost is harder to quantify than the financial data. Unemployment rose from about 3 percent in 1929 to nearly 25 percent by 1933. Industrial production dropped by roughly half. International trade collapsed as countries raised tariffs in response to each other. The global monetary system, which had been tentatively restored to gold standard conditions in the mid-1920s, began to fracture. Countries that stayed on gold the longest, like France, actually suffered less initially but ultimately dragged their economies down through deflation. Countries that left gold earlier, like Britain in 1931, recovered their competitiveness faster.
The long-term lesson from the 1929 crash isn't that markets go up and then down. It's that systems built on excessive leverage with insufficient oversight will eventually break, and when they break, they take everything with them. The safeguards that exist today weren't created because regulators had foresight. They were created because the alternative was completely unacceptable. That's the difference between preventing a crash and merely surviving one.