How a 20 Year Rv Loan Calculator Actually Works
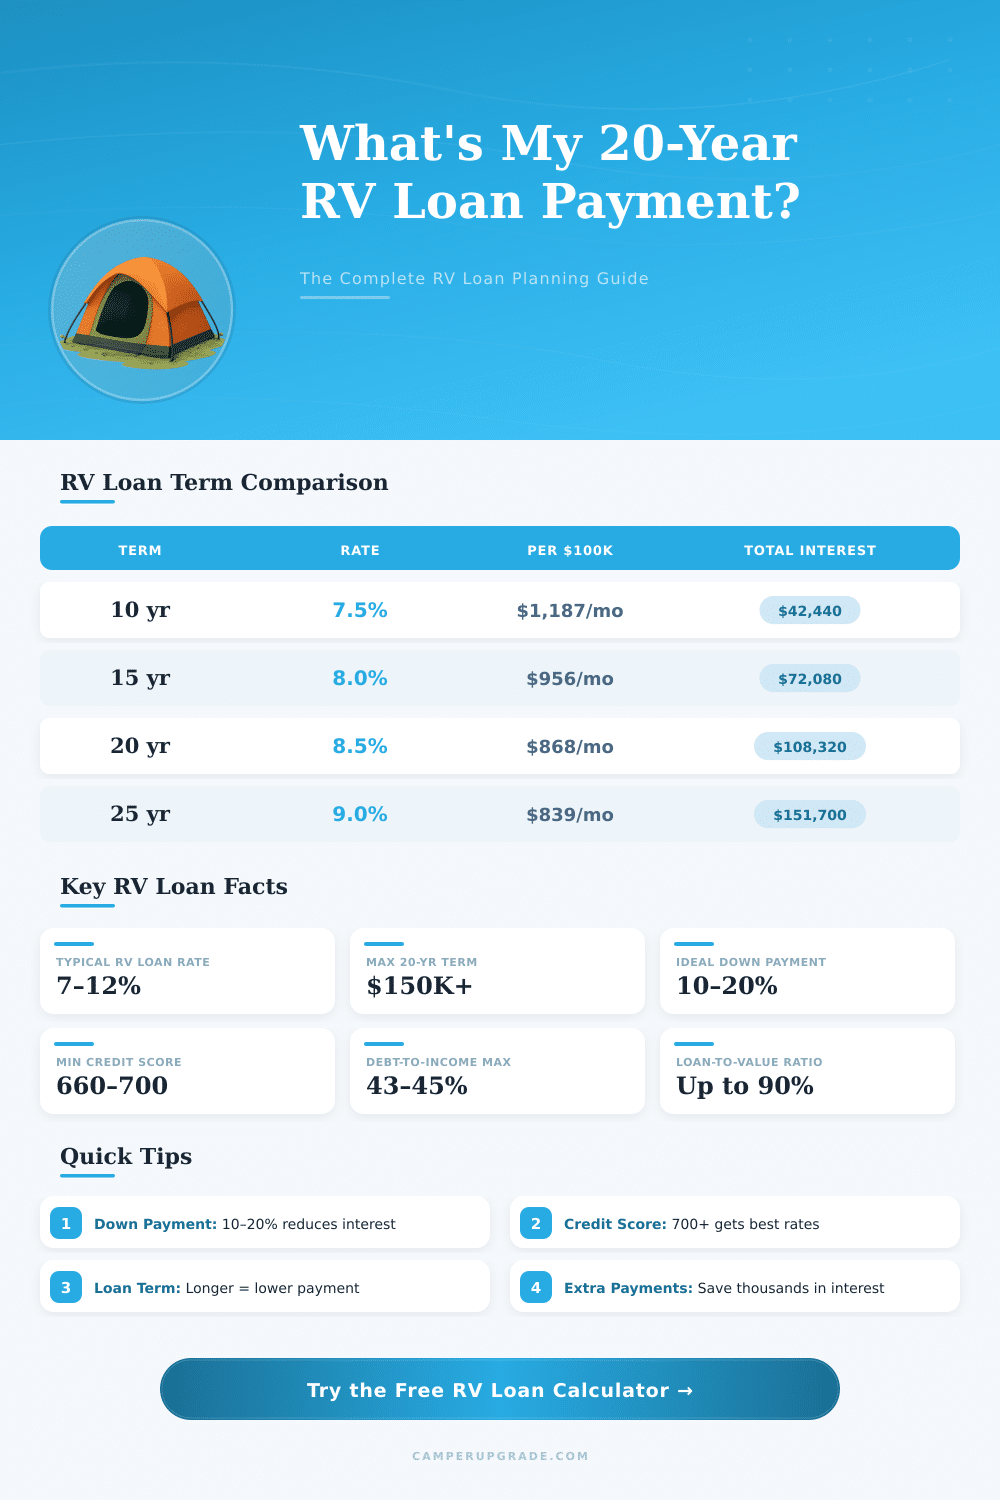
Most people grab a 20 Year Rv Loan Calculator and plug in numbers without really understanding what's happening under the hood. I've been helping folks figure out RV financing for over a decade, and the thing I notice most is that the output looks clean but the assumptions behind it are often wrong. Let me walk through how these calculators work and what you need to watch out for.The basic formula is standard amortization. You take your loan amount, divide by the number of payments, but then you add interest that compounds monthly. The key variable is your annual percentage rate, which lenders quote you as a nominal rate but it compounds monthly, so the effective annual cost is slightly higher. A 20-year loan at 6.5% on a $45,000 balance gives you roughly a $369 monthly payment. That's the math. The reality is messier. Here's where people get burned. These calculators assume the full loan amount is financed at the quoted rate for the entire term. In practice, RV loans often have balloon payments, prepayment penalties, or variable rates after year three. I had a client last year who used a calculator and committed to a $380 monthly payment on paper. When we sat down with the actual loan docs from the credit union, there was a five-year adjustable rate period that would have pushed the payment to $440 within eighteen months. The calculator never showed that because it doesn't know about the ARM structure. Another thing the standard tool misses: insurance, registration, and property taxes if you're registering in a state that taxes recreational vehicles. These aren't part of the loan but they're monthly obligations that eat into the same budget. A quick rule of thumb is to add roughly $75 to $120 per month for those costs depending on your location and the value of the rig.
How to Use This Correctly
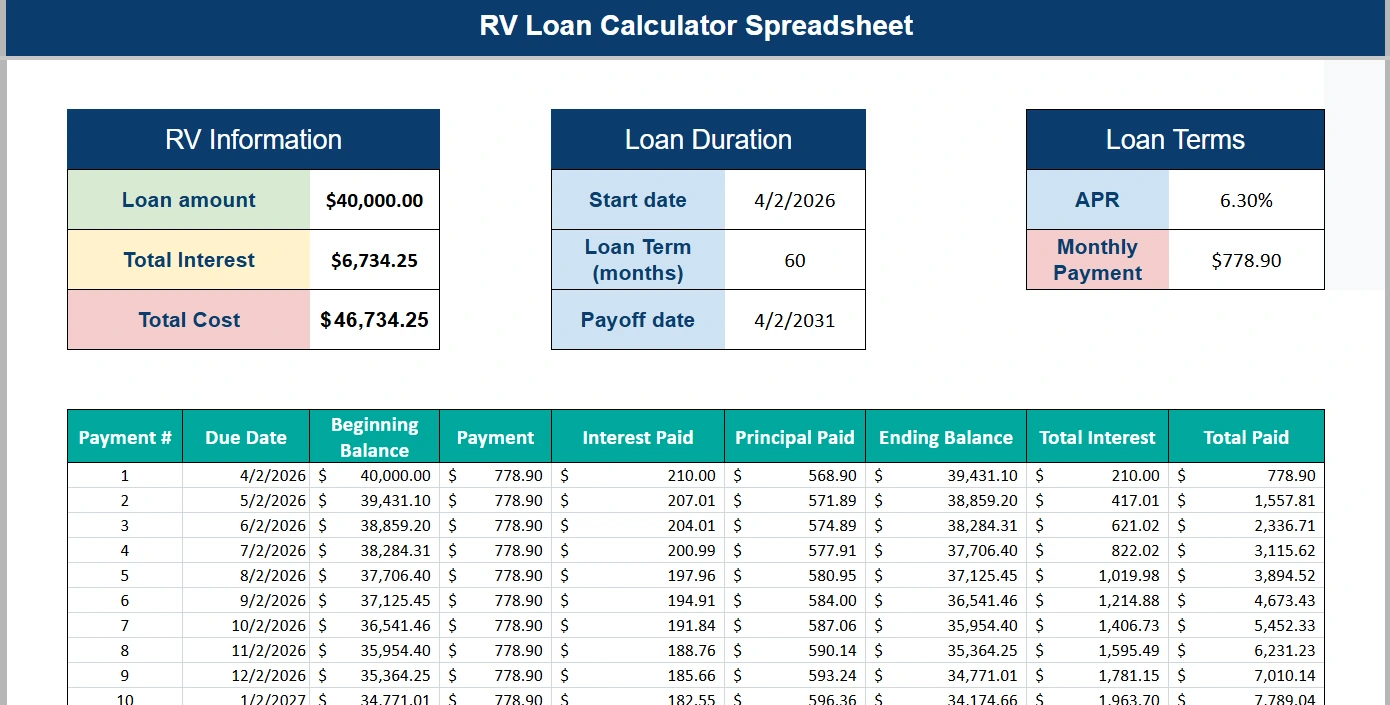
Run the numbers twice. First, use a basic calculator with the base rate the dealer or lender quotes you. Then run it again at the rate plus half a percentage point. That half-point buffer accounts for your actual credit tier and any lender fees that get rolled into the APR. If the higher scenario still fits your budget, you're in decent shape. If the buffered version breaks you, the real rate will too. Also check whether the lender allows extra principal payments without penalty. Some manufacturers' captive financing arms, like Forest River or Thor's lending partners, offer low introductory rates that come with a prepayment penalty in years one through three. That makes the 20-year term a trap. You pay interest on the full balance for years even if you sell or refinance early. I keep a simple spreadsheet alongside the calculator output. It tracks the amortization schedule month by month for the first thirty-six payments, then jumps to yearly intervals. This takes about ten minutes and shows you exactly how much principal you're actually paying down in the early years. At twenty years, you'll barely dent the balance until year eight or nine. That's not a calculator problem, that's just how long amortization works. It's worth knowing before you commit.