Getting Your 2018 Taxes Sorted Out
The 2018 tax year was one of the bigger changes in recent memory thanks to the TCJA. The standard deduction doubled, brackets shifted, and a lot of the old deductions got capped or eliminated entirely. If you're trying to figure out what you owed or are working on an amended return, you need a proper way to model those numbers. That's where a 2018 Tax Cal comes in handy. You want a calculator that was built for the 2018 brackets, not one that's auto-updating to current-year rates every time you refresh the page. A lot of free calculators on the internet just piggyback off whatever the current IRS tables are. That means if you plug in 2018 income, it'll apply 2024 brackets and give you a number that looks right but isn't. I've seen people file amended returns based on those outputs and end up owing more than they should. The trick is finding one that either explicitly says 2018 or lets you lock the year. Tools like the Tax Foundation's historical calculator, or the IRS archive pages, sometimes have snapshots. I also keep a copy of a Google Sheets model that hardcodes the 2018 rates so I don't accidentally use updated percentages.
How the 2018 Brackets Actually Look
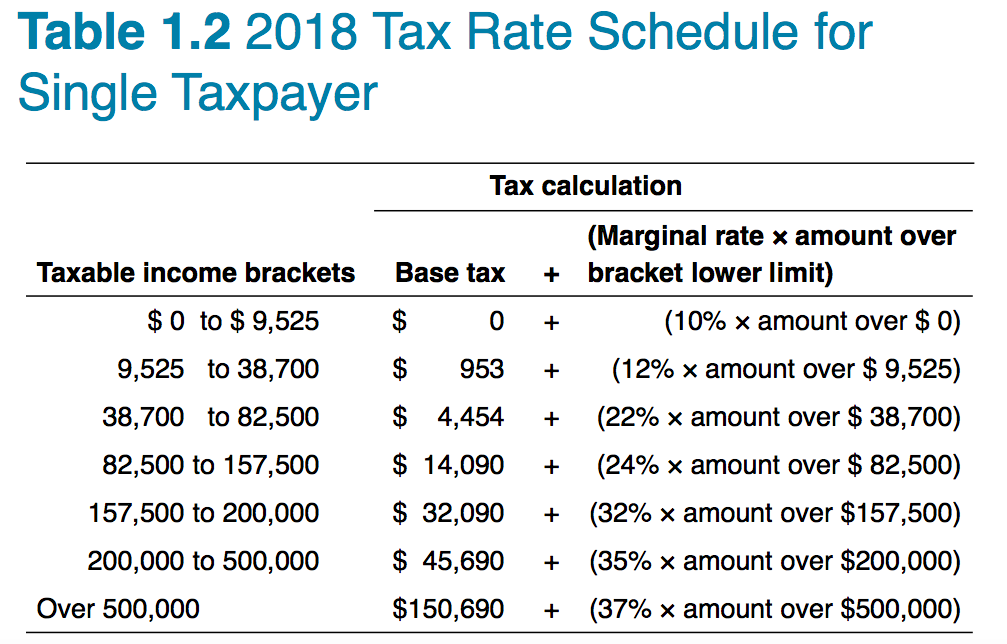
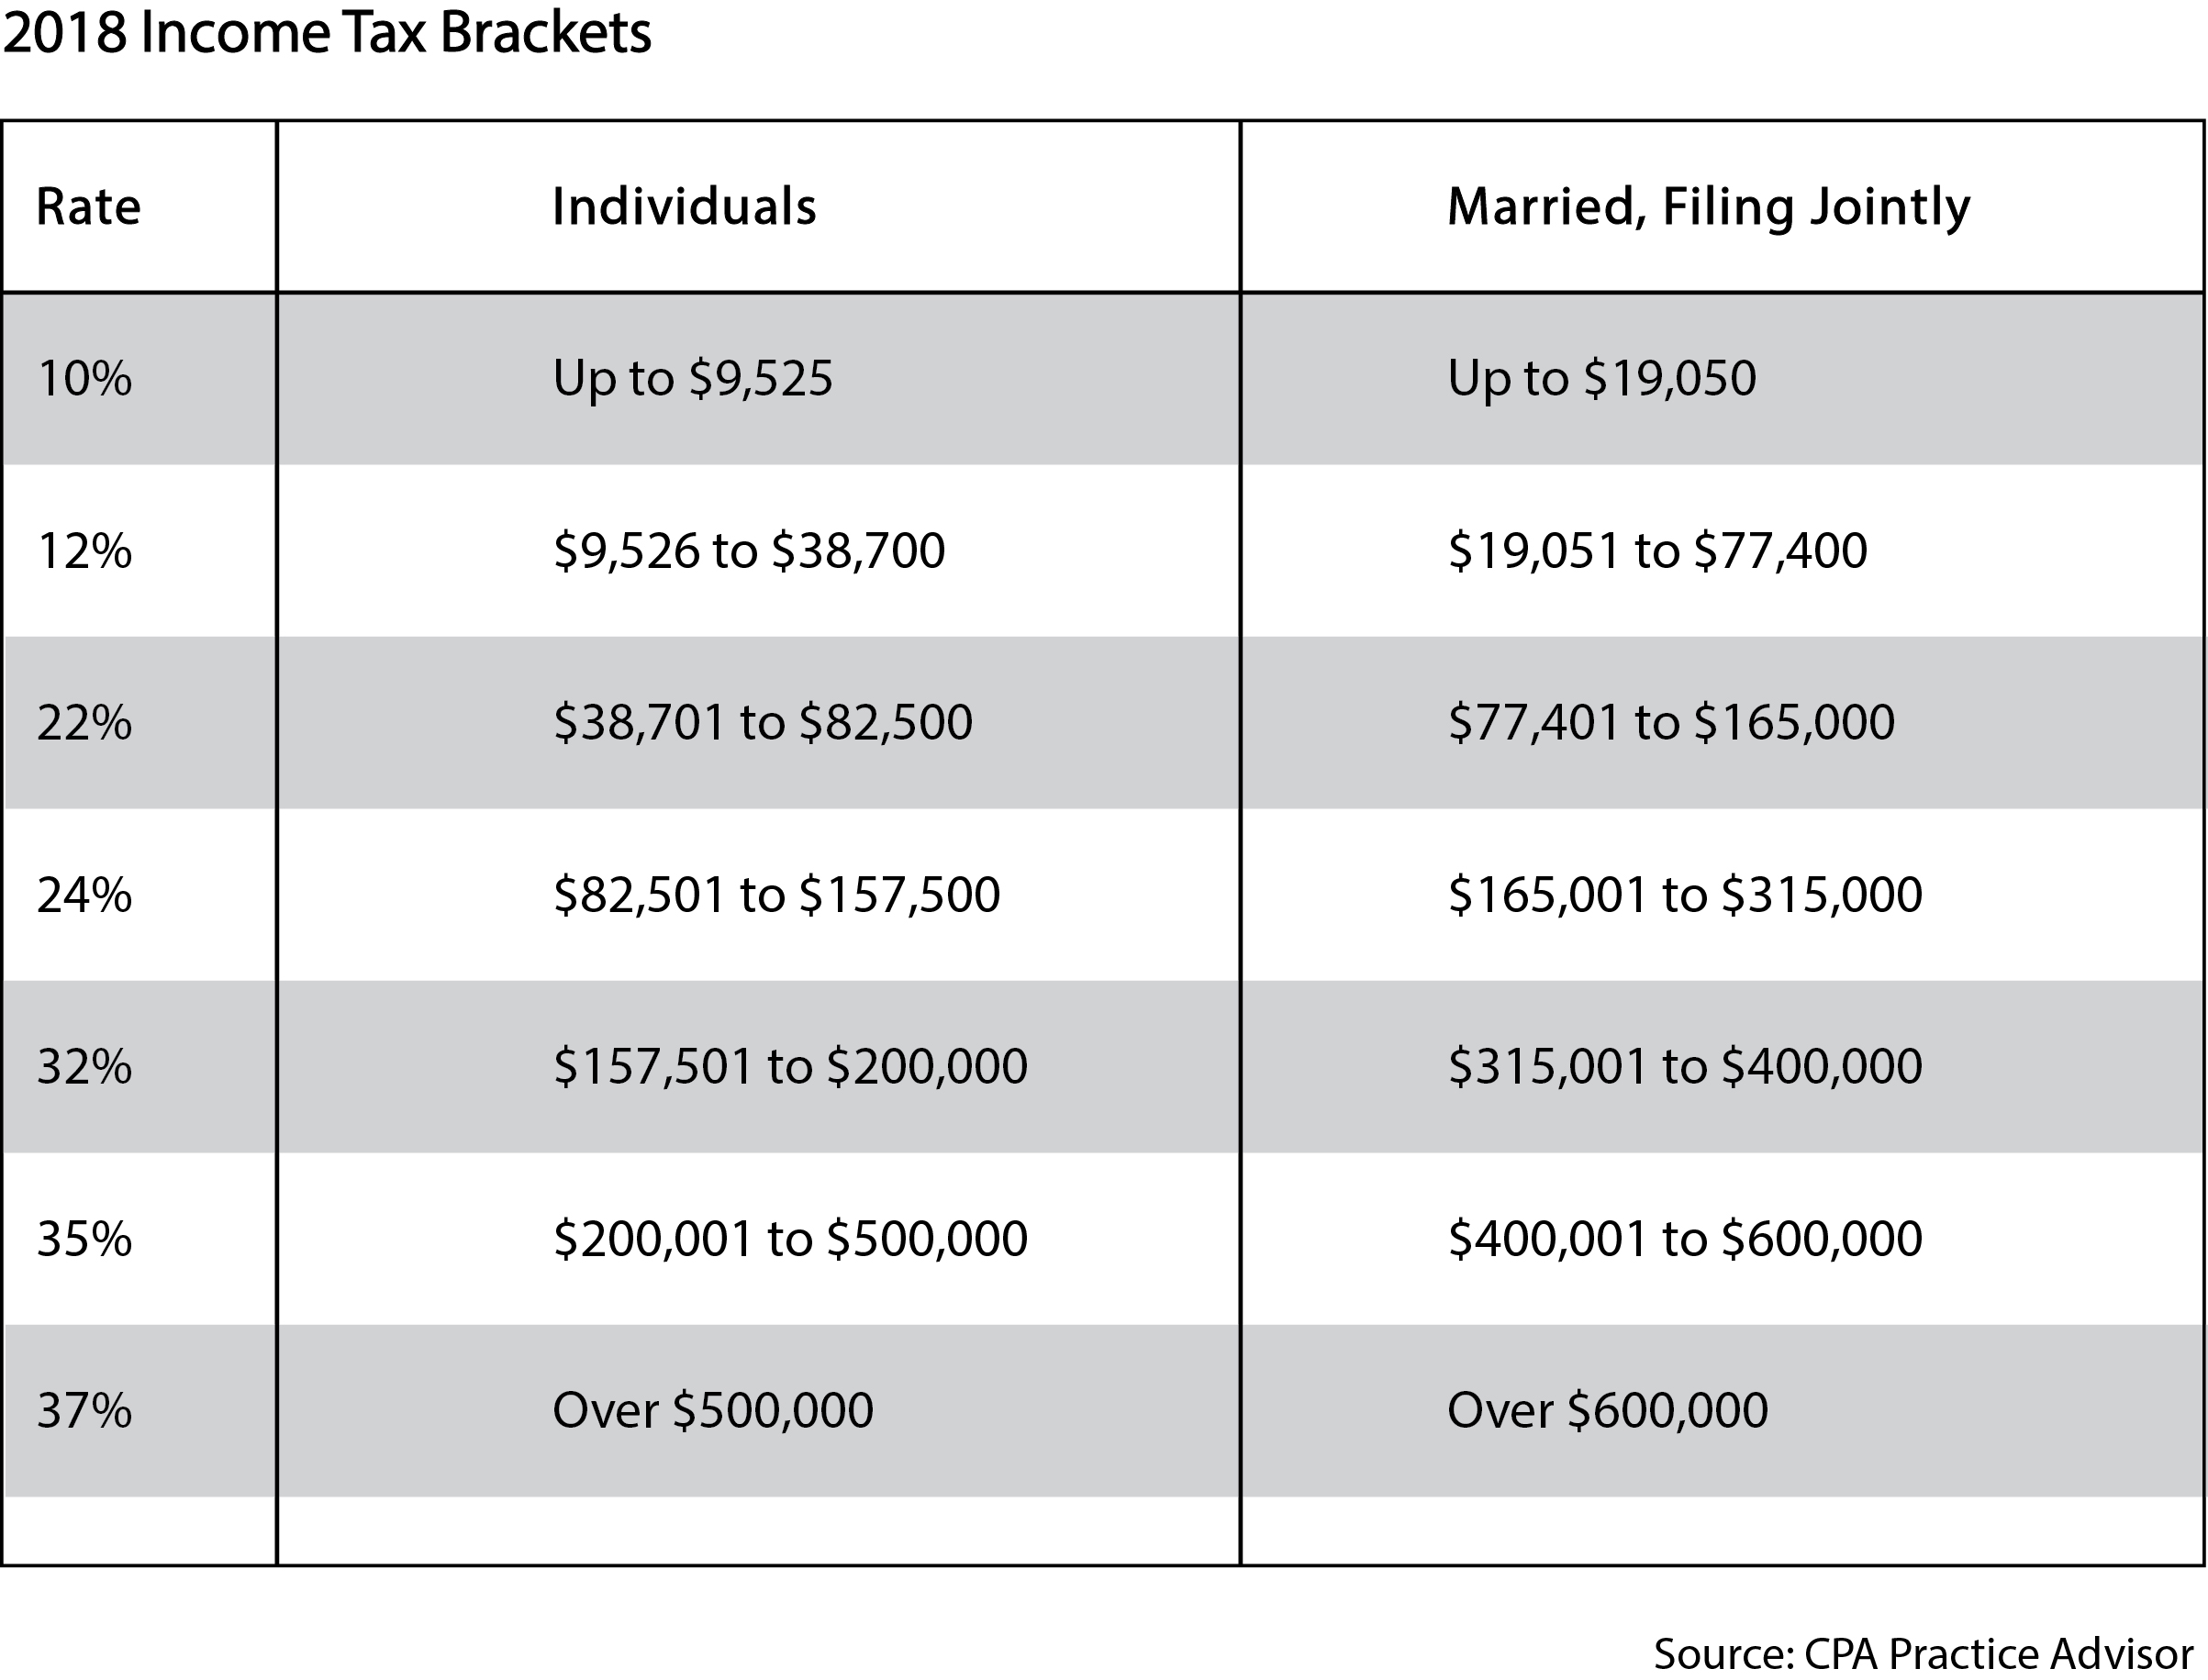
Here's what you're working with. Single filers: ten percent on income up to nine thousand five hundred seventy-five dollars. That jumps to twelve percent on the next chunk, all the way up to one hundred twenty-six thousand dollars in total. Fifteen percent starts at one hundred twenty-six thousand. Twenty-two percent kicks in at two hundred thirteen thousand. Twenty-four percent begins at two hundred fifteen thousand seven hundred fifty. Thirty two percent starts at four hundred eleven thousand five hundred. Thirty five percent at eight hundred twenty-five thousand. And the top bracket, thirty seven percent, applies to anything over that last threshold. Married filing jointly roughly doubles those thresholds except at the very bottom and very top where the jumps get weird. Head of household sits somewhere in between single and joint. The point is you can't just guess your way through this anymore.
Things the Calculators Get Wrong
I ran into a specific edge case last year when someone was trying to retroactively model their 2018 return. They had itemized deductions that were partially eaten by the Pease phaseout but also limited by the SALT cap, which kicked in at ten thousand dollars that year. Their calculator showed a deduction that was roughly fourteen hundred dollars too high because it wasn't cross-referencing the two limitation rules simultaneously. The workaround was simple but annoying: calculate the SALT cap impact first, reduce your state and local tax deduction to that ten thousand dollar ceiling, then run the remaining itemized deductions through the overall Pease formula. It took me about twenty minutes manually instead of the three minutes a good calculator would have taken if it handled both interactions. Another common failure point is qualified business income. The QBI deduction changed the effective tax rate for pass-through owners in a way that most basic calculators don't even attempt. If you have Schedule C income and your taxable income falls in the phase-in range for QBI, the calculator needs to run a separate computation. If it doesn't, your liability will be off. I've seen discrepancies of two hundred to eight hundred dollars depending on the situation.
Get the Full Details
Downsides and What to Do Instead
The honest problem is that no single free online calculator handles every interaction cleanly for a year this complex. The IRS doesn't maintain an official archived calculator that goes back to 2018. The software companies mostly push current-year products. So you're left with third-party tools that may not be fully accurate, or you do it yourself. If you're doing this for one return, I'd suggest building a small spreadsheet. It takes about forty-five minutes to set up correctly, but once it's done, you can reuse it. You'll input gross income, adjust for adjustments to income, arrive at AGI, decide whether to itemize or take the standard deduction, apply the QBI deduction if applicable, and land on taxable income. Then you hit the brackets. This usually gives you a number within twenty to forty dollars of what you'd actually owe, which is close enough for most purposes. If you need exact figures for an amended return or an audit, you're better off paying a professional who has access to software like Lacerte or ProConnect that let you select the tax year explicitly. Their accuracy comes from maintaining the actual IRS tables and interaction logic internally. You can also use the IRS Tax Assistant tool for specific questions rather than trying to derive your entire liability from a generic calculator.
The bottom line is that the 2018 tax year isn't something you should wing. The bracket structure alone creates situations where two people with identical gross income can owe wildly different amounts depending on filing status and whether they hit certain phaseouts. A proper 2018 Tax Cal that respects the year-specific rules will save you from the awkward conversations with the IRS that come from using a calculator that wasn't built for the job.