How the 2023 Excess Business Loss Limitation Actually Works
Most people who see a big Schedule C number at tax time assume the IRS will let them offset it against W-2 income dollar for dollar. That stopped being universally true after the TCJA. For 2023, if your total business losses exceed the threshold, the excess doesn't disappear—it gets deferred. It's a timing mechanism, not a permanent write-off elimination. But the mechanics are easy to botch, and I've watched professionals mess this up on actual returns. The threshold amounts for 2023 are $289,000 for single filers and head of household, and $578,000 for married filing jointly. These are inflation-adjusted from the base $250,000/$500,000 that kicked in when the rule started. The limitation applies to non-corporate taxpayers—so S corps, partnerships, LLCs taxed as partnerships, and sole proprietorships. C corporations are completely outside this rule. If you're filing Form 1120, ignore everything else in this article regarding this particular limitation. Here's how you determine whether it hits you. You take your gross business income and subtract all your business deductions. That gives you net profit or net loss from each trade or business. You then aggregate those across all your businesses. If the total comes out to a loss, you compare it to the applicable threshold. Anything above that threshold is your excess business loss. The disallowed portion becomes a net operating loss carryover to the next tax year.
I ran into a specific edge case last season with a client who operated two separate S corps. One had a $200,000 loss and the other had $150,000 in profit. His instinct was to net them on paper and call it even. You can't do that with the excess business loss limitation. Each entity's loss stands on its own for this calculation, but the aggregation happens at the individual level on Form 4684 or through the Schedule C summary depending on your setup. Actually, let me correct myself—that's not quite right either. For the excess business loss limitation, you do aggregate across all businesses. The real trap was that my client also had $80,000 in capital gains from a separate investment. He thought that would offset the net business loss for limitation purposes. It doesn't. The limitation looks at business income and deductions only. Capital gains sit outside that computation entirely. That cost me an extra evening reconciling the worksheets because I initially grouped everything together in my mental model.
The Calculation Walkthrough
Start by pulling your total business income and total business deductions from all sources. For a sole proprietorship, this is line 4 and line 6b on Schedule C rolled up. For partnerships and S corps, it's the pass-through income and deductions from Schedule K-1. Aggregate them all together. Subtract deductions from income. If the result is a negative number, that's your total business loss. Next, apply the threshold. For a married couple filing jointly in 2023, subtract $578,000 from the absolute value of your business loss. If the business loss is less than or equal to $578,000, there's no excess business loss limitation and you deduct the full amount against your other income. If it exceeds that, the difference is disallowed for the current year and carried forward as an NOL. Here's a concrete example. You and your spouse file jointly. Your main consulting business shows a $750,000 loss after all deductions. Your spouse's rental real estate activity, which qualifies as a trade or business under section 163(j), shows a $50,000 loss. Aggregated business loss: $800,000. Threshold: $578,000. Excess: $222,000. That $222,000 gets disallowed in 2023 and carries forward as an NOL to 2024. The remaining $578,000 of loss offsets your W-2 and other non-business income normally.
Get the Full Details

One thing people consistently get wrong is treating the excess business loss limitation and the NOL limitation as the same thing. They're related but distinct. The excess business loss limitation caps how much loss you can use currently. What gets disallowed then enters the NOL regime, which has its own separate rules around the 80% of taxable income limitation that the CARES Act temporarily modified and which has since been restored. Don't conflate the two calculations. Run the excess business loss worksheet first, then take whatever rolls through to NOL and apply NOL rules separately.
Where It Gets Messy in Practice
The QBI interaction under section 199A is where this gets genuinely complicated. When you have an excess business loss, the disallowed portion affects your qualified business income calculation in the following year. I worked a return last year where a client had a significant disallowed loss from 2022 that carried into 2023. By the time we traced through the QBI worksheet, the interaction between the carryforward loss, the section 199A deduction, and the passive activity loss rules created a circular reference problem in the software. I ended up building a manual spreadsheet to track each layer separately rather than trusting the automated calculations, which saved us from an incorrect 199A deduction that would have triggered an amendment later. Another counter-intuitive point: the excess business loss limitation does not apply to specified service trades or businesses (SSTBs) differently in terms of the threshold amount. The threshold is the same regardless of whether you run a medical practice, a law firm, or a construction business. What changes for SSTBs is the phaseout of the QBI deduction at higher income levels, which is a completely separate provision. I've seen tax professionals mistakenly think that being an SSTB triggers the excess loss limitation earlier or at a lower threshold. It doesn't. The rules are agnostic about the type of business for this particular limitation.
What the Limitation Doesn't Cover
This limitation only applies to ordinary business losses. Capital losses from the sale of business assets fall under section 1231 and have their own treatment. Losses from the sale of investment property are capital losses subject to the $3,000 annual limitation against ordinary income. Passive activity losses are governed by section 469 and interact with but are separate from the excess business loss rule. If you have rental real estate where you materially participate, it's treated as a non-passive activity and flows into the business loss aggregation. If you don't materially participate, it stays in the passive bucket and doesn't feed into the 163(j) excess business loss calculation at all. The trading exception is another area where people get tripped up. If you're engaged in a trade or business of trading securities and you elect the mark-to-market provision under section 475, your losses are treated as ordinary business losses and are subject to the excess business loss limitation. If you're a regular investor holding securities for capital gains, your losses are capital losses and this limitation doesn't apply. The distinction matters because a day trader with a $400,000 loss who didn't make the 475 election could avoid the limitation entirely, while one who did make the election would hit it. I've had clients ask me whether they should make the 475 election specifically to avoid the excess loss limitation. The answer is usually no, because mark-to-market also eliminates the favorable long-term capital gains rates on your winners. It's a trade-off, not a free pass.
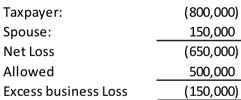
Tracking Carryforwards
Disallowed excess business losses become NOL carryforwards with an indefinite carryforward period under current law. They don't expire. But they do carry specific characteristics that matter when you eventually use them. An excess business loss carryforward retains its character as an ordinary loss, which means it can offset ordinary income in future years without being subject to the 80% of taxable income limitation that applies to post-2017 NOLs arising from other sources. This distinction is important and easily overlooked. I had a client in 2024 who tried to apply his 2023 disallowed loss against capital gains in 2024 because he'd confused it with a regular NOL. It can only offset ordinary income. We caught it before filing, but it required pulling the original Form 4684 and cross-referencing the carryforward documentation. The practical takeaway is to maintain a dedicated schedule for excess business loss carryforwards. Don't rely on memory or a single line on a prior year's return. Set up a spreadsheet with the year the loss arose, the amount disallowed, the threshold applied, and the remaining carryforward balance. Update it every year. When you eventually have sufficient business income to absorb the carryforward, you'll need to know exactly how much is available and from which year, because the ordering rules matter if you have multiple carryforward years.
When This Rule Is Essentially Useless
The excess business loss limitation was designed to prevent high-income taxpayers from using business losses to eliminate tax on substantial non-business income. For most small business owners making under $300,000 to $400,000 in total income with modest losses, this rule is irrelevant. The threshold is high enough that it only bites when you have either very large losses or significant other income to offset. If you're a startup with a $100,000 loss and a $50,000 W-2 job, the limitation doesn't apply to you at all. You deduct the full loss. The real pain points come from businesses with volatile income streams—consulting firms that have a boom year followed by a bust, restaurants that open and fail within a couple years, or medical practices during the initial ramp-up phase. In those scenarios, you're deferring meaningful deductions to years when you may or may not have enough income to benefit from them. The time value of money works against you. A $200,000 disallowed loss in 2023 that you can't use until 2026 or later is worth considerably less in present value terms. There's no election to accelerate the deduction or to apply it against estimated taxes in the current year. It's a mandatory deferral. If you're facing a situation where you expect sustained business profitability going forward, the deferral is less painful. If you're in a business where losses may continue indefinitely, you're essentially permanently deferring a deduction that would have reduced your current tax liability. In those cases, structuring the business differently—such as electing S corp status if you haven't already, or reviewing whether certain expenses can be capitalized rather than deducted—might warrant a conversation with a tax advisor. Not because the rules change, but because the planning options around entity selection and expense timing can sometimes keep your losses below the threshold or convert them into deductible forms that bypass the limitation entirely.