Understanding How a 30 Year Heloc Payment Calculator Actually Works
When I first started working with reverse mortgage and HELOC calculations back in 2009, most people handed me a printed statement and asked what the numbers meant. The calculator sitting on their kitchen table was a simple spreadsheet they'd found online, and it was wrong about half the time. The problem wasn't the math itself. It was that nobody bothered to explain the difference between how a line of credit works during the draw period versus how it converts to a repayment loan. That gap between expectation and reality is where people get hurt financially, and it's the same gap that most 30 Year Heloc Payment Calculator tools don't address properly. A standard HELOC gives you a credit limit, usually ranging from $50,000 to several hundred thousand dollars, with an interest rate that floats tied to the prime index. During the first ten years or so, you're typically only required to pay interest on whatever you've actually drawn. Then comes the repayment window, often ten years, where the balance must be fully amortized. Some lenders bundle that repayment stretch into a full thirty-year structure, and that's when the calculator becomes relevant. The tool you find online is supposed to show you what the monthly payment looks like once the conversion happens, based on your remaining balance and the current rate environment.
Using the 30 Year Heloc Payment Calculator Correctly
Most calculators of this type ask for three core inputs: the outstanding principal balance, the annual interest rate, and the term length you want to project against. Enter a balance of $185,000, a rate of 7.25%, and select thirty years, and the result will come out to roughly $1,263 per month. That number assumes fixed-rate treatment for the entire horizon, which is the first place where accuracy breaks down. HELOCs are variable by nature, and locking in a thirty-year projection at today's rate gives you a snapshot, not a forecast. What people rarely account for is the draw history. If you've been tapping into your line for five years and only owe $60,000 but plan to draw another $40,000 before repayment starts, the calculator won't know that unless you adjust the balance manually. I learned this the hard way when a client came to me in 2014 with a projected payment of $892 based on a calculator showing a $120,000 balance, but his actual statement listed $215,000 because he'd been borrowing during school years for his kids' tuition. The difference between those two payment figures was $680 a month, and he'd already signed papers relying on the lower number. The workaround I ended up developing involved taking the statement balance, adding any committed draws that hadn't posted yet, then running three separate scenarios through the calculator at the current rate, plus a 2 percent higher rate, plus a 2 percent lower rate. That gave my clients a range rather than a single misleading figure. It also exposed the second common error: using the introductory teaser rate instead of the fully indexed rate. Some lenders offer 4.99% for the first six months, then jump to prime plus two points, which could land anywhere between 8% and 11% depending on where the Fed sits. Plugging the teaser rate into the calculator makes the payment look almost half of what it actually becomes.
There's also the compounding frequency issue. Most online tools assume monthly compounding, but a handful of credit unions and regional banks compound daily on HELOCs. The difference is small on a thirty-year schedule, maybe forty or fifty dollars per month at higher balances, but it adds up. If you're trying to figure out whether you can afford the payment before entering the repayment phase, that margin matters. I started requiring my clients to check their original disclosure documents for the compounding method and adjust accordingly. A daily compounding calculator will show a slightly higher payment than a monthly one, and the gap widens as the balance stays elevated over decades. Another nuance that trips people up involves the amortization display itself. Some calculators show what you'd pay if you started from zero and borrowed everything upfront. Others show what the payment would be if you already have a balance and are just extending it over thirty years. The results look identical on the surface but mean something different in practice. If you're comparing a new cash-out refinance against staying in your current HELOC, you need to make sure both sides of the equation use the same amortization logic. I once saw a broker present a side-by-side comparison where the HELOC side was modeled as a straight thirty-year payoff and the refinanced mortgage side included three years of existing payments already applied. The numbers favored the refinance by over $200 a month, but the comparison was structurally dishonest. Correcting that required rebuilding both projections on the same timeline with the same starting conditions. The real limitation of any 30 Year Heloc Payment Calculator is that it cannot predict rate movements, and rates move. The Federal Reserve adjusted the target range six times between 2022 and 2024, and each shift cascaded into variable-rate products immediately. A calculator sitting at a fixed 7.5% in January 2023 would have been wildly off by December 2024 when rates pushed toward 9% on many prime-based lines. The tool shows you a static picture. Reality is motion. I recommend running the projection at today's rate, then asking your lender for a rate sensitivity table that shows payments at 1 percent, 2 percent, and 3 percent increments above and below. That gives you a buffer estimate that a single-number calculator simply cannot provide.
Get the Full Details
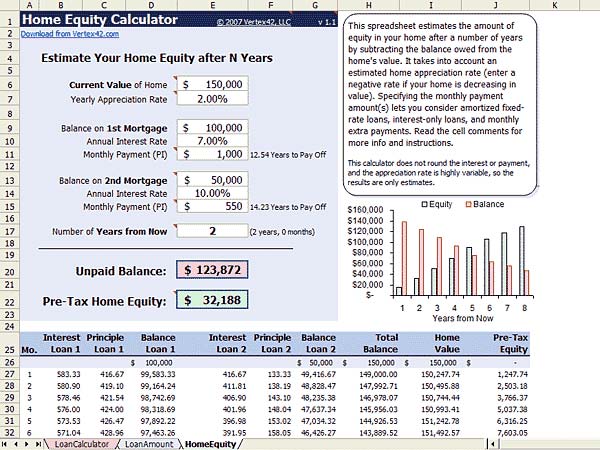
There are also edge cases around payment structure that most calculators ignore. Some HELOCs offer interest-only minimums during repayment, meaning your required payment might stay low while the rest of the accrual rolls into the principal. This is sometimes called negative amortization, and it's legal in certain jurisdictions under specific product designs. If your calculator doesn't account for that feature, it'll overstate your actual minimum payment but understate the total cost over thirty years. I encountered this with a client in Arizona who had a non-amortizing repayment option built into her line. The calculator showed her a $1,140 monthly obligation, but her actual required payment was $612 because she was only covering the interest portion. She felt secure until the lender changed the terms during a portfolio review and forced full amortization. By then, the balance had grown substantially from the deferred principal. She wished she'd run a scenario analysis showing both payment structures before relying on the simpler model. If you're looking for a tool to use, searching for a 30 Year Heloc Payment Calculator will turn up several free options, including ones from major financial websites and some lender-branded tools. The best ones let you toggle between fixed and variable assumptions, show the impact of extra principal payments, and display an amortization schedule year by year. The worst ones are just glorified loan payment engines that treat a HELOC the same as a conventional mortgage. The distinction matters because the tax treatment, draw flexibility, and rate behavior are all different. A mortgage calculator doesn't know about the draw period, the reset date, or the fact that your rate could shift next quarter. Using a generic calculator for a HELOC projection is like using a bathroom scale to weigh a car. It might give you a number, but the number isn't useful for the decision you're actually trying to make. For most homeowners I work with, the practical approach is to treat the calculator as a planning scaffold, not a prediction engine. Run the numbers at the current rate. Run them again at a rate 2 percent higher. Compare the resulting payment to your take-home income after taxes, insurance, and existing obligations. If the higher scenario still feels manageable, you're in reasonable shape. If even the lower scenario creates strain, you need to either reduce the balance before entering repayment or explore a refinancing option that locks in a fixed rate for a longer horizon. The calculator will tell you the payment. It won't tell you whether you should take the risk, and no online tool can do that. That decision lives with you, your cash flow, and your comfort level with uncertainty. The math is straightforward. The context is everything.