What You're Actually Getting Into
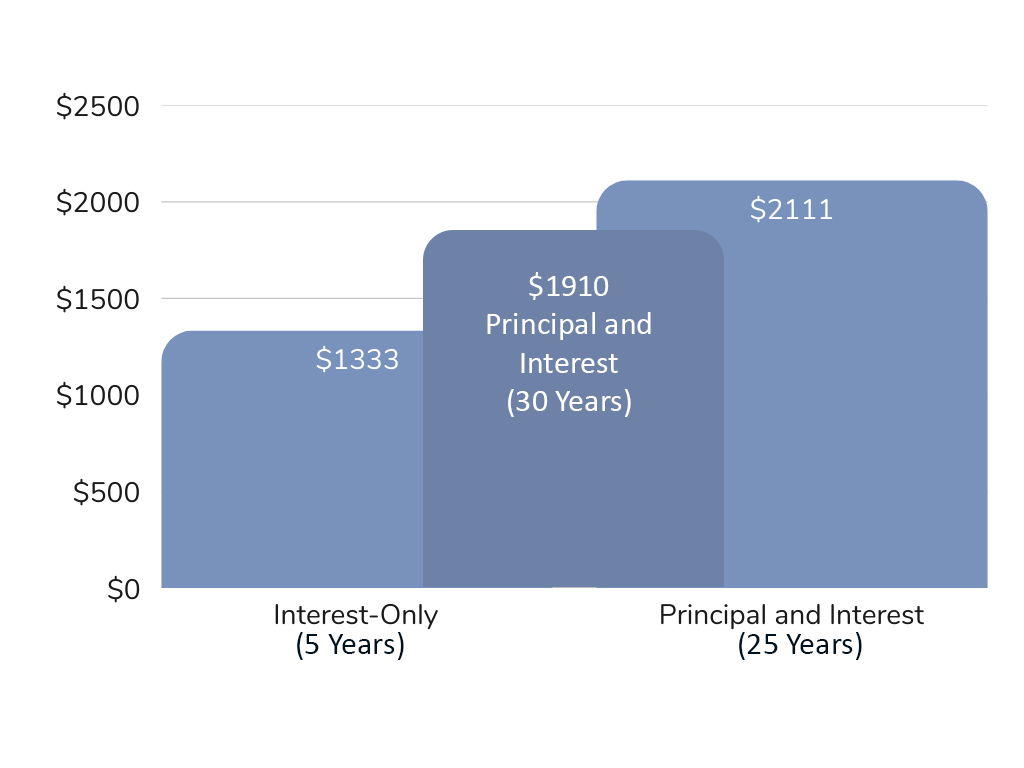
A 30 Year Interest Only Loan lets you pay just the interest on your mortgage for a set period, usually the first five to ten years of the term. After that window closes, the loan flips into a standard amortizing payment where principal starts getting paid down alongside interest. The monthly payment during the interest-only phase is dramatically lower than it would be on a conventional 30-year fixed, which is the whole reason people look at it in the first place. Lower payments sound good until you realize the principal balance never shrinks, and once the interest-only period ends, your payment can jump by thirty to fifty percent overnight depending on the terms. I worked through a case last year where a borrower had an IO period structured as ten years out of thirty, and when the reset hit, the lender recalculated the payment over the remaining twenty years at the then-current rate, which had climbed from 3.5% to 6.25%. Their payment went from $1,450 a month to $2,980. They hadn't factored in the rate environment shifting. They'd only looked at the initial payment and ran with it.How a 30 Year Interest Only Loan Actually Works
The structure is straightforward on paper. You borrow, say, $400,000 at 6.5% interest. During the IO period, your monthly payment is just the interest portion: $400,000 times 6.5% divided by twelve months, which comes to about $2,167. You pay that every month for the duration of the interest-only window. The principal stays at $400,000. No equity builds. No balance drops. After the IO period expires, the remaining balance gets amortized over whatever years are left on the loan, and your payment recalculates based on the current rate and remaining term. There are a few different variants you will run into. Some IO loans convert to a fully amortizing schedule at the end, meaning you pay both principal and interest for the rest of the term. Others convert into a negative amortization loan where the unpaid interest gets added to the principal balance. A few are structured as hybrid ARMs where the IO period coincides with a fixed rate, then the rate adjusts annually after that. Each variant produces a very different outcome, and the documentation rarely flags the difference in plain language. I found this out the hard way with a client who thought they had a standard IO-to-amortizing loan. When the ten-year mark hit, the servicer applied their payment to a negative amortization schedule because the original note had a capitalized interest clause buried in section 7B. The borrower's balance had actually grown by roughly $18,000 over those ten years instead of staying flat. They had to refinance the accrued interest on top of the original principal just to get back to even. It cost them about $4,200 in closing costs to clean up.
The key thing most people miss is that not all interest-only periods are treated the same by lenders. Some require proof of income verification at origination but not at reset. Others lock in the rate for the full term and only the payment structure changes. You need to know exactly what kind you are signing before you make any assumptions about what happens in year six or year eleven.
Who This Makes Sense For and Who Should Walk Away
Interest-only loans work if you have a clear exit strategy or income trajectory that justifies the structure. Real estate investors who plan to flip or refinance within the IO window often use this product because they are not holding long enough for the payment reset to matter. They lock in low payments, collect rental income, improve the property, and move before the clock runs out. Borrowers expecting a significant raise or promotion in the next few years also sometimes find value here. You take the lower payments now, build whatever equity you can through appreciation or extra principal payments, and refinance into a traditional mortgage before the reset. I had a client who did this exact sequence. She took a five-year IO on a $525,000 loan at 5.75%, paid about $2,501 a month during that period, made several principal-only payments totaling $38,000, then refinanced into a 30-year fixed at 4.25% with full amortization before the reset hit. She saved roughly $600 a month compared to what her payment would have been under a standard loan from day one, and she still ended up with a lower rate. The problem is that not everyone can execute that sequence cleanly. Income gaps, appraisals coming in low, or credit score dips during the waiting period can all derail a refinance right when you need it most. I watched a borrower miss his refinance window by eleven days because his employment verification was delayed and the lender refused to accept a W-2 with a letter in lieu of a pay stub. By the time he qualified, rates had ticked up another quarter point. He ended up refinancing anyway but paid roughly $12,000 more in total interest over the life of the loan because of the delay.
Get the Full Details

If you do not have a defined timeline for selling or refinancing, an interest-only loan is generally a bad fit. The payment reset is not a theoretical risk. It is a guaranteed event, and the magnitude of the increase depends on how much principal remains and what rates look like at reset. There is no way to know the exact number today, only to model it under different scenarios.
The Math Behind the Payment Shock
Let me walk through a concrete example. Say you take out a $450,000 loan at 6.0% with a seven-year interest-only period. Your monthly payment during those first seven years is $2,250. The balance stays at $450,000. After seventy-two months, the loan converts to a fully amortizing schedule over the remaining twenty-three years. If rates have stayed at 6.0%, your new payment becomes approximately $2,902. That is a $652 increase per month, or about 29% higher than what you were paying before. Now suppose rates have moved to 7.5% by the time of reset. Your payment jumps to roughly $3,136. An increase of $886 per month, or nearly 39% higher. If the loan has negative amortization instead, the balance might have grown to $468,000 by year seven, and at 7.5% over twenty-three years, your payment would be closer to $3,318. The numbers compound quickly and rarely work in your favor if the market moves against you. The other hidden cost is opportunity cost. While you are paying only interest, you are not building equity through amortization. In a standard 30-year fixed loan at 6.0%, you would pay down roughly $27,000 in principal during the first seven years. That is $27,000 of forced savings that simply does not happen with an IO structure. If the property appreciates at a modest 3% annually, the equity gain from appreciation offsets part of this, but it is not a substitute for actual principal reduction.
What to Check Before You Sign
The most important thing is reading the actual promissory note, not the marketing flyer the loan officer hands you. Look for the clause that describes what happens at the end of the interest-only period. It will tell you whether the loan converts to fixed-rate amortizing, adjustable-rate amortizing, or negative amortization. The language is usually buried in the payment terms section, often labeled something like "Adjustment of Payment at Expiration of Initial Period." If you cannot find it, ask for it directly. Most lenders will point you to the right paragraph if you know what to ask for. Also check whether the loan includes a prepayment penalty. Some IO loans charge a fee if you pay off the balance or refinance within the first three to five years. A penalty of 2% on a $450,000 loan is $9,000, and it can easily erase any savings you gained from the lower initial payment. I had a borrower who refinanced at year three without realizing the penalty clause existed. He walked away with $7,800 less than he expected after closing costs. You should also verify the cap structure if the loan converts to an ARM. Annual caps and lifetime caps determine how much your rate can increase at each adjustment and over the life of the loan. A loan with a 2% annual cap and a 6% lifetime cap behaves very differently from one with 5% and 10% caps. Under worst-case scenarios, the lifetime cap alone can push your rate to 12% or higher, and your payment would reflect that immediately.

Alternatives Worth Considering
If your goal is lower initial payments but you want to avoid the reset risk, a standard 30-year fixed mortgage is almost always the safer choice. The payment is predictable for the entire term, and you build equity from month one. The monthly payment will be higher during the early years, but you are buying certainty. For a $450,000 loan at 6.0%, the payment is $2,699 compared to $2,250 under the IO structure. The difference is $449 a month, and over seven years that totals about $31,430 in extra interest. But you also accumulate roughly $62,000 in principal equity during that same period instead of zero. Another option is a 5/1 ARM, which offers a fixed rate for five years and then adjusts annually. Your payment during the initial period is similar to an IO loan, but principal starts building immediately, and the reset is governed by explicit rate caps rather than an abrupt payment conversion. The trade-off is that your rate can still climb, and the payment can still increase, but the mechanics are more transparent and the exposure is generally lower. For investors specifically, a bridge loan or short-term portfolio loan may serve the same purpose without the long-term baggage. These products are designed for holding periods of one to five years, carry higher rates, and require quicker payoff timelines. They align better with flip strategies and do not have the hidden amortization traps that sleeper IO loans can contain.
The Bottom Line
An interest-only loan is a tool, not a mistake and not a solution. It reduces your initial cash outflow at the cost of delaying equity buildup and introducing payment uncertainty. The people who use it well understand the reset date, have a plan for what happens after, and have verified the terms in the actual loan documents. The people who get hurt are the ones who treat the low initial payment as a permanent feature instead of a temporary condition. The reset will happen whether you are ready for it or not. The only question is whether you have a path to handle it when it does.