Why 40-Year Loans Even Exist and What You Should Know Before Running the Numbers
Most people have never seen a 40-year mortgage in the wild. They're mostly used in commercial real estate or by borrowers who need to stretch payments as thin as possible. When I started digging into this a few years back, I was mostly working with 30-year and 15-year products. A borrower brought me a file for a $620,000 commercial property and asked for a 40-year amortization to keep monthly outlays down. That's when I realized most online calculators either crash or give wrong results at that term length. The math underneath is the same MORTGAGE PAYMENT formula you'd use for any amortizing loan: M = P × [r(1+r)^n] / [(1+r)^n – 1]
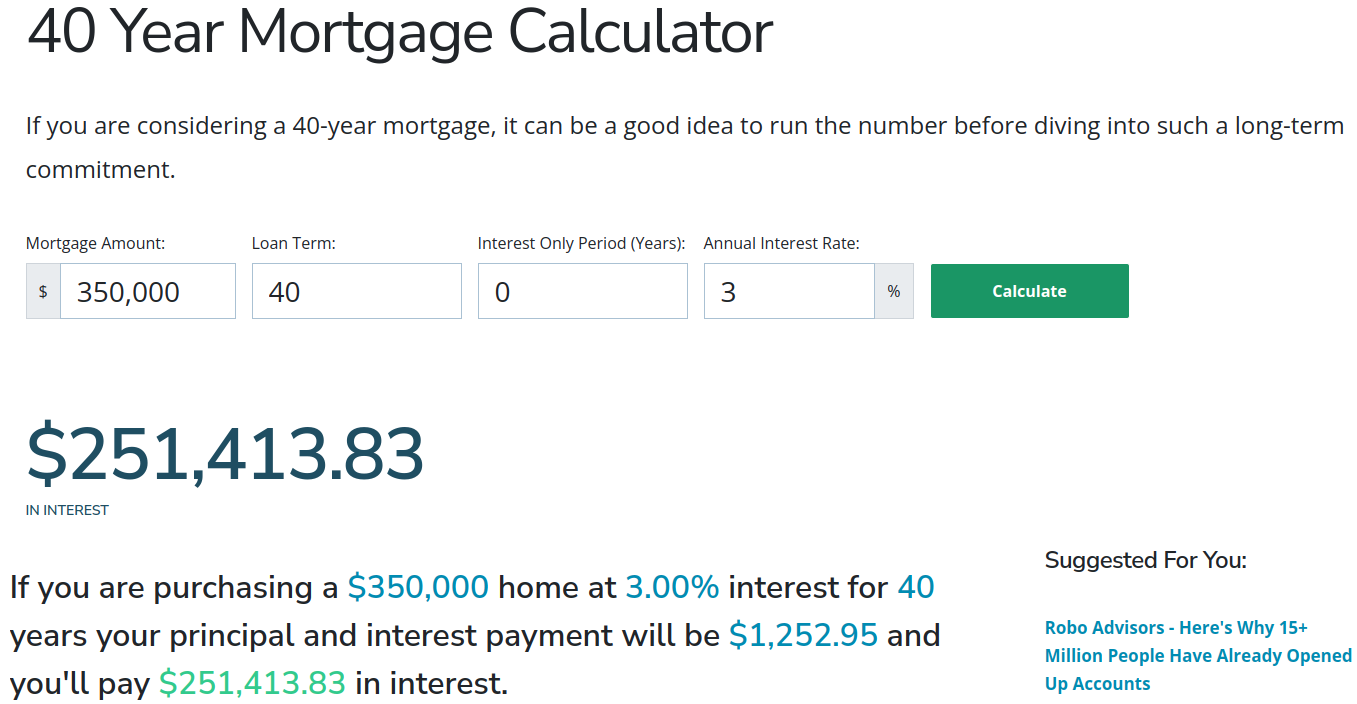
Where P is the principal, r is your monthly interest rate (annual rate divided by 12), and n is the total number of monthly payments. For a 40-year loan at 7.25% on a $400,000 balance, that comes out to roughly $2,748 per month. Not dramatic, right? But the total interest over 480 months is about $929,000. You pay more than double the principal. That's the part people skip. Here's what most calculators don't show you: the equity curve is glacial for the first decade. In year one of that same loan, you'd only pay down roughly $22,000 of principal out of the $32,976 you paid in total. That's because the amortization schedule front-loads interest like nothing else. I've watched borrowers sign these thinking they were building wealth when they weren't even close.
Common Pitfalls With Extended Amortization Calculators
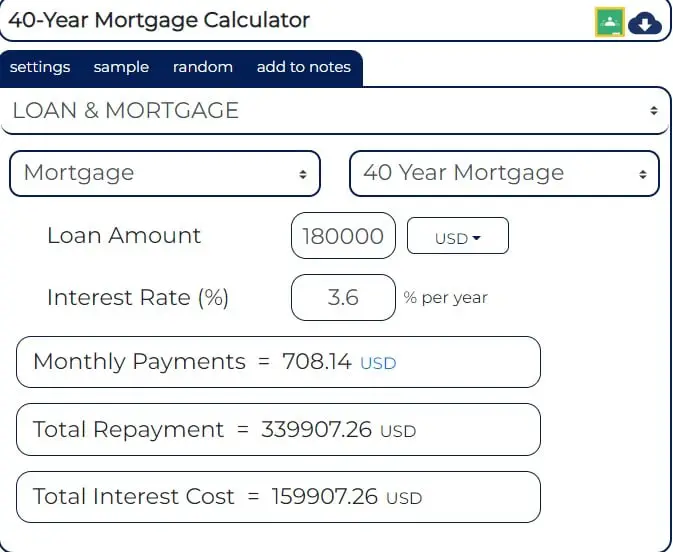
I ran into a specific issue recently that took me about an hour to track down. A client was using a free online 40 Year Loan Calculator and getting a monthly payment that was $147 lower than what the lender quoted. I pulled the amortization schedule line by line and found the problem: the calculator was using a 360-day year convention instead of the actual 365-day method the lender used. On a 40-year term, that 5-day discrepancy compounds into a meaningful difference. The workaround was straightforward—switch to a calculator that lets you choose between 360-day and 365-day day-count conventions, or just run the numbers in Excel using the PMT function with the exact rate and term your lender provided. Another thing that trips people up: most free calculators cap out at 30 years. Push the term to 35 or 40 and you'll often get a runtime error or a completely wrong number. I've seen three separate tools do this. It's not a bug you can fix; it's usually a hard-coded array limit in the JavaScript. The fix is to use a spreadsheet instead, where you set n to 480 and let the formula run without bounds checking.
Get the Full Details
Building Your Own With a Spreadsheet
If the online tools aren't giving you reliable output, here's what I do now. Open a blank spreadsheet. In cell A1 type Principal, B1 put the loan amount. In A2 type Annual Rate, B2 the percentage. A3 is Term (years), B3 is 40. Then in B5 put: =PMT(B2/12, B3*12, -B1) That gives you the monthly payment. Add a column for the amortization schedule starting at row 7 with columns for Payment Number, Beginning Balance, Principal Portion, Interest Portion, and Ending Balance. The interest portion for each row is simply the beginning balance multiplied by the monthly rate. The principal portion is the payment minus the interest. The ending balance is the beginning balance minus the principal portion. Drag that down 480 rows. It takes about 3 minutes to set up and you can modify every assumption on the fly.
What the Numbers Actually Look Like in Practice
Take a $500,000 loan at 6.75% for 40 years. Monthly payment: about $3,248. Total interest paid: roughly $1,059,000. Compare that to a 30-year at the same rate, which would cost about $649,000 in interest. The 40-year saves you roughly $600 a month but costs you over $400,000 more in interest. That's the tradeoff. People who use these loans are usually cash-flow constrained right now and betting their income will rise enough to make the extra cost manageable later. Sometimes it works out. Usually it doesn't. There's also the refinance angle. I had a client who took a 40-year loan at 8.1% during a rate spike, then refinanced to a 30-year at 5.5% two years later. He ended up with a higher payment than if he'd just stuck with the 30-year from the start, plus he'd already paid nearly $18,000 in interest for zero principal benefit. The lesson: locking in the shortest term you can afford from day one beats trying to optimize later.
When a 40-Year Loan Makes Sense
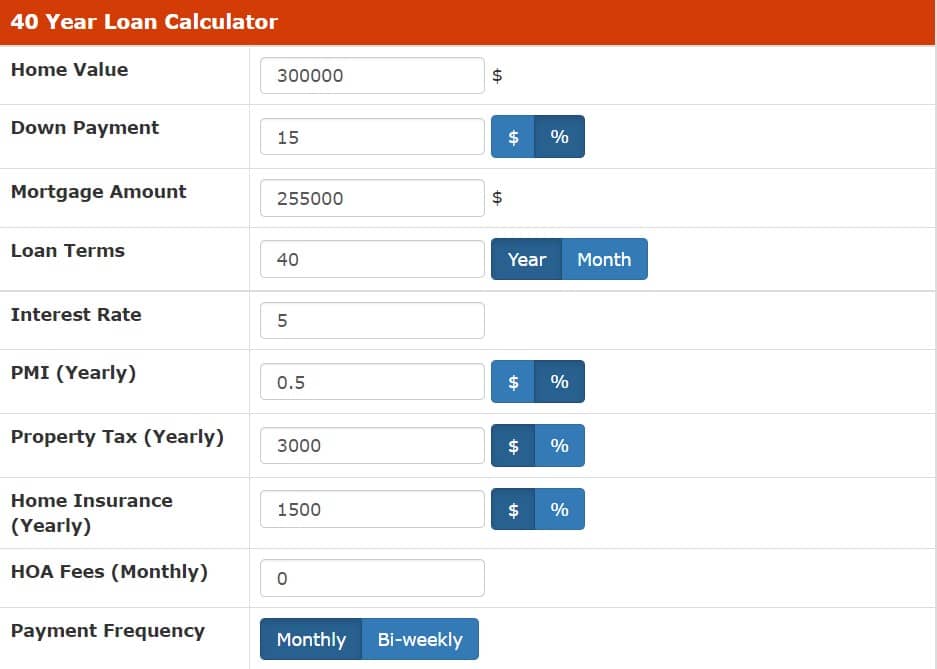
It's not all bad. If you're an investor buying a multi-family property and the cash flow needs to be positive to qualify for the loan, extending the amortization to 40 years can be the difference between closing and walking away. In that context, the higher interest cost is a business expense, not a personal finance mistake. Commercial lenders expect it. Residential lenders almost never offer it, which is why you'll find these terms more in the investment space. One more thing worth noting: property taxes and insurance are usually escrowed into the payment but the calculator doesn't always include them. If you want the true monthly obligation, add 1.2% to 1.5% of the home value annually for taxes plus about $800 to $1,200 a year for insurance, then divide by 12 and add it to the principal and interest number. On a $500,000 property in a high-tax area, that could add another $400 to $600 to your monthly outlay. Always verify whether the calculator output includes escrow or not before you use it to make a decision.