What You Actually Need to Know About 401K Audited Financial Statements
Most employers handling plan audits don't realize how narrow the word "audited" actually is. An audited financial statement for a 401(k) plan is not the same thing as an annual report you send to participants, and it's not a tax filing either. It sits somewhere in between, governed by DOL rules and generally accepted auditing standards, and the people who mess it up usually do so because they were trying to make it simpler than it is. The core document you're building is the plan's financial statement package, which has to include a balance sheet, a statement of net assets available for benefits, a statement of changes in net assets, and a statement of plan investments. That's four statements minimum before you even get to the notes. Each one needs to tie back to the custodian records, the recordkeeper's trial balance, and the participant transaction log for the plan year in question. If any two of those three don't reconcile to the penny, the auditor is going to flag it, and you're spending billable hours untangling it.
401K Audited Financial Statement Examples 2021
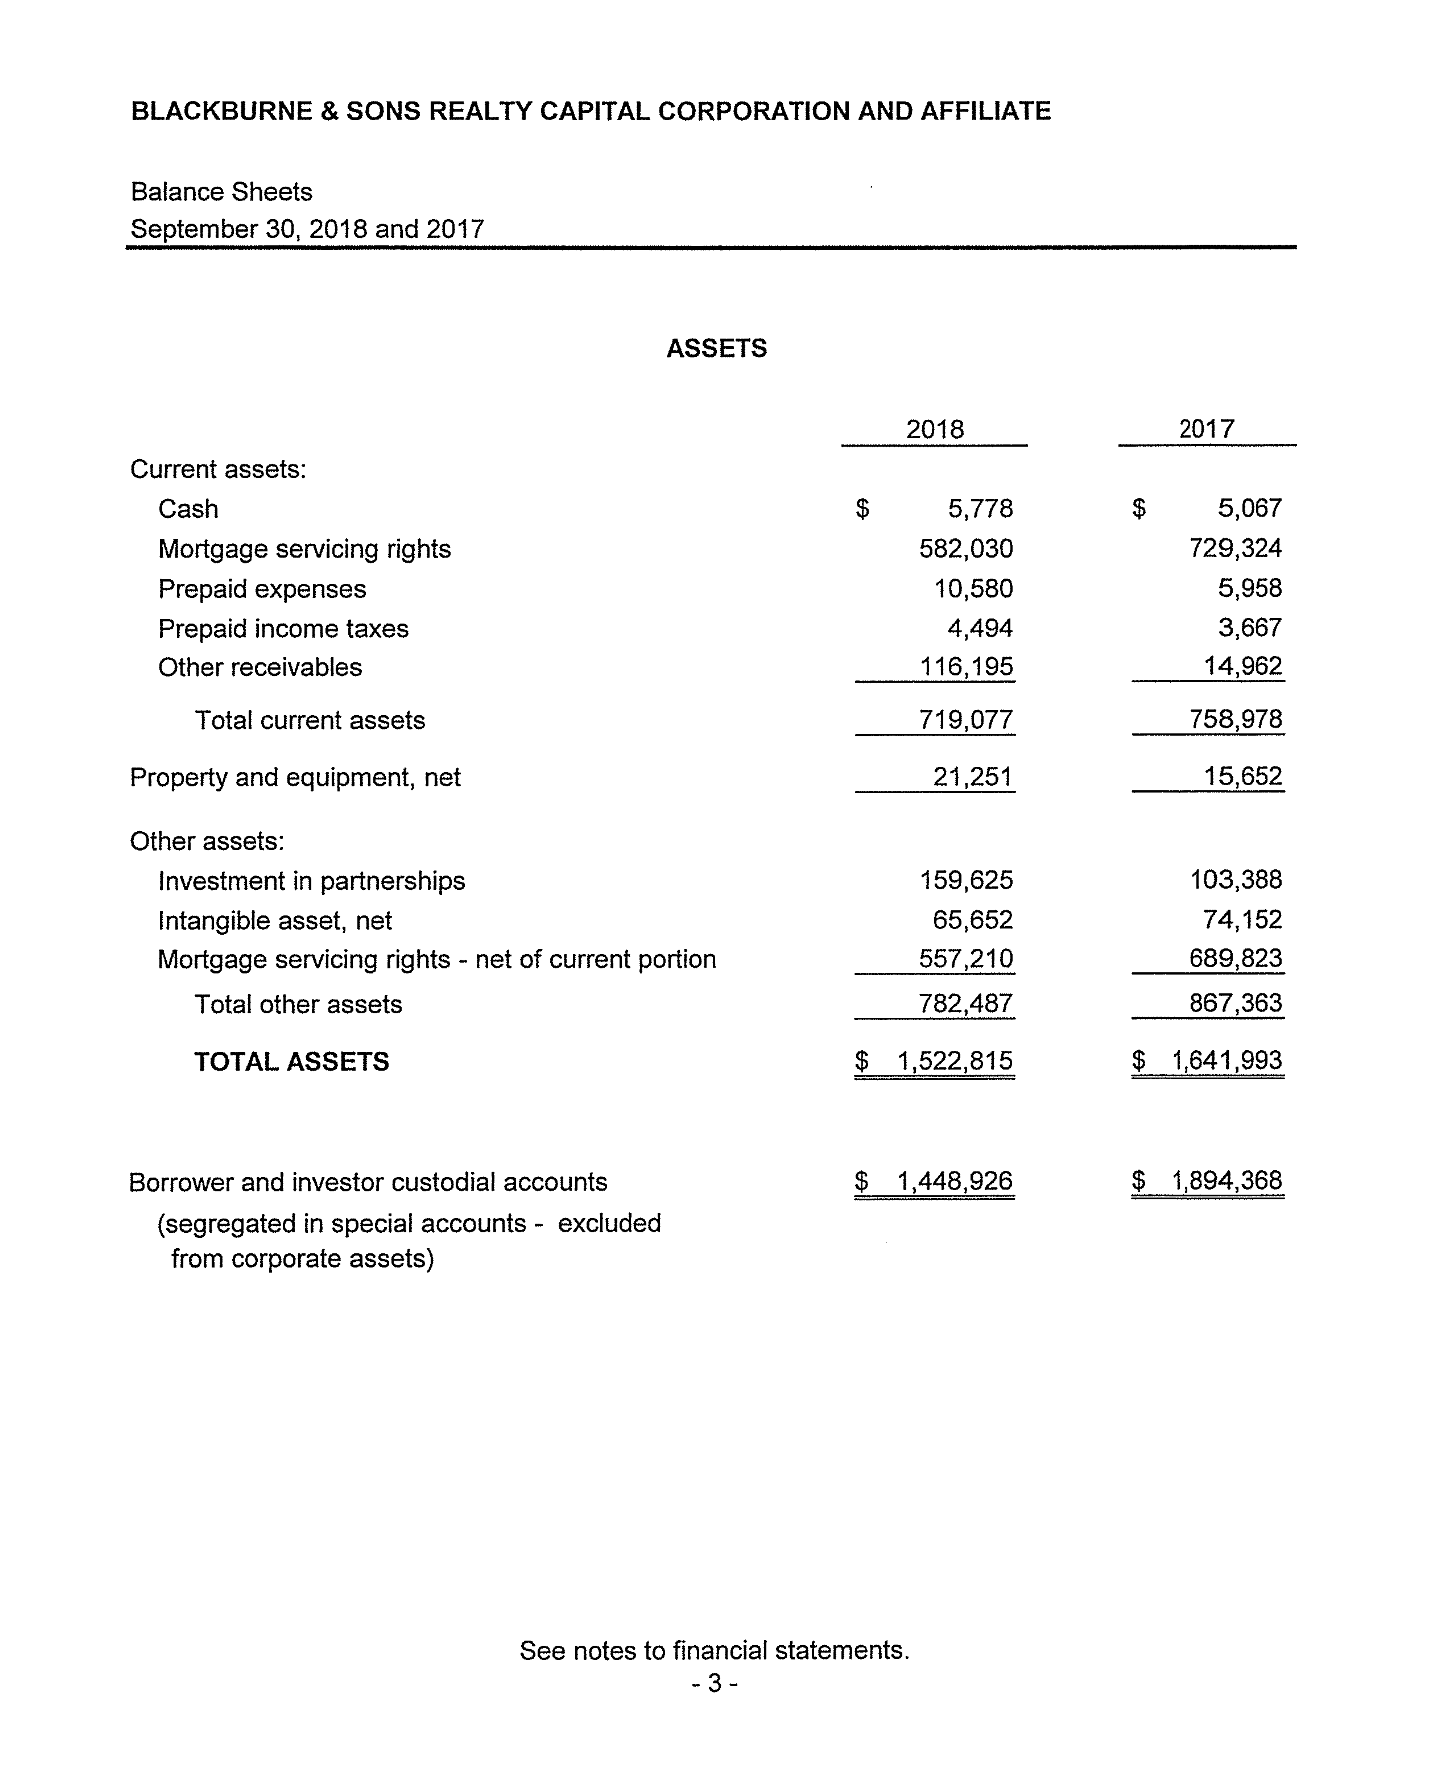
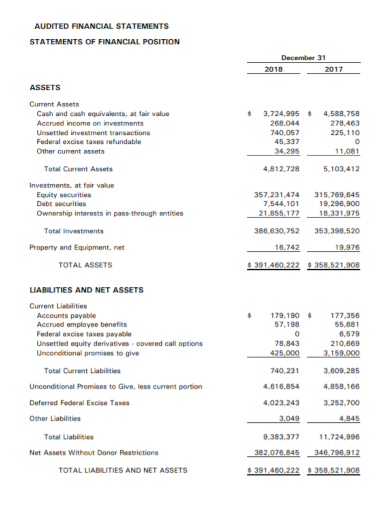
Looking at what actually worked for my clients in 2021, here's the structure most plans followed without hitting major issues. The plan year ending December 31 was standard, but a significant number of plans had mid-year sponsor changes due to acquisitions, and that created compounding problems for the opening balances and rollover reconciliations. If your plan had a change, the example below breaks down what you'd need to include. A clean example starts with the plan identification block. Plan name, EIN, plan number, and the custodian. Then the balance sheet showing cash, participant loans receivable, and the fair value of each investment category held. The line items are straightforward, but the notes to the financial statements are where most plans cut corners, and cutting corners here is how you end up with a qualification or adverse opinion instead of a clean one. The statement of net assets available for benefits needs to show the fair value of assets minus liabilities, which in a healthy 401(k) plan is just the aggregate participant account balance. That number has to match the recordkeeper's participant listing down to the last cent. I've seen plans where a single misposted employer contribution created a $340 discrepancy across four accounts, and it only showed up during the third reconciliation pass because the recordkeeper classified it under a different contribution type than the custodian statement.
The statement of changes in net assets tracks contributions, losses or gains, and administrative expenses. If the plan had losses during the year, you list them separately from gains. If the plan is required to file a full audit because it had more than 100 eligible participants on the first day of the plan year, you include the Schedule H attachment on the Form 5500. Plans with fewer than 100 can file Schedule I, which is lighter but still demands the same underlying financial data. Here's a concrete example from a plan I worked on last year. A mid-size manufacturing employer with 142 active participants. Their plan documents allowed QDRO disbursements, had a direct lending feature for participant loans, and the sponsor was also a participant. The auditor requested separate schedules for each loan class, a reconciliation of the loan receivable from the prior year, and a breakdown of the QDRO distribution flow. That's where things got tedious. The plan's previous administrator never filed a QDRO register, so we had to reconstruct the order of distributions from bank records and participant letters going back three years. The workaround was pulling the custodian's disbursement history by participant SSN and matching it against the plan's internal payment log. It took about six hours of someone actually sitting there and building a cross-reference table in Excel, but it resolved cleanly by the end of the week. If your plan is missing a QDRO register or a similar log, the gap is fixable. It just costs time, and time is the thing most plan sponsors underestimate.
Get the Full Details

How to Build Your Own Package Without Wasting Weeks
The practical path through this is methodical and deliberately unglamorous. You start with the custodian statement as your source of truth. Not the recordkeeper's numbers. The custodian. The recordkeeper can misclassify a contribution type or miss a recharacterization. The custodian statement shows what was actually held at the plan's asset level on December 31st. From there you build outward. Request the custodian trial balance and the participant account listing simultaneously. These should match, but they won't always. Cash differences between the two are common when a contribution arrives the week before year-end and gets recorded by the recordkeeper but hasn't settled at the custodian yet. That's a normal timing difference. Document it in your workpapers. Don't ignore it and hope the auditor doesn't notice. They will. Next, prepare the four required statements. Many firms use audit prep software for this, but I find a well-structured spreadsheet template saves more time than wrestling with software that forces its own logic onto your plan. Label each line clearly. Reference the custodian page number next to every balance. If a value changes from the prior year, explain why in the footnotes. Auditors appreciate context more than they appreciate silence.
The note disclosures are non-negotiable. You need to disclose the nature of the plan, the significant accounting policies, participant loans and their terms, any nonqualifying securities held, and any events that occurred after the measurement date but before the issuance of the financial statements. Post-measurement date events are easy to miss. A major contribution made in January that was intended to fund a December distribution needs to be noted if it affects the comparability of the two years. Administrative expenses also warrant close attention. If the plan paid administrative fees directly from plan assets, they belong on the statement of changes in net assets. If the sponsor reimbursed the plan, document that separately. Reimbursements reduce the plan's expense line but require proof that the money came back into the plan, ideally with a bank deposit confirmation from the same quarter.
Where Things Break Down and What to Do Instead
The biggest failure mode I see is a plan that assumes its recordkeeper is producing the audited financial statement for it. That's wrong. The recordkeeper produces participant account data. The plan's auditor or the plan administrator produces the audited financial statement. If the recordkeeper is offering an "audit package," it's a starting point, not the finished product. I've watched plans hand the recordkeeper's raw output to an auditor and get sent back immediately with a request for reconciliations that the recordkeeper couldn't possibly provide because they're looking at participant-level data while the auditor needed asset-level detail. Another area where plans fail is the 100-participant test. It's based on eligible participants, not actual participants. If your plan allows employees to participate once they reach age 21 and completion of one year of service, you count anyone who meets those criteria on the first day of the plan year. It doesn't matter if they haven't contributed yet or haven't rolled money in. The count includes them. Plans that get audited because they misread this rule spend the entire year under a heavier filing requirement than necessary. Conversely, plans that legitimately fall under the small-plan exception sometimes file a full audit because they didn't understand the threshold. Both directions waste money. Terminated plans introduce their own complications. If the plan distributed all assets and closed out within the plan year, the auditor may still require a full audit if the plan had over 100 participants at any point during the year before termination. The DOL's position is that the participant count applies to the period the plan was open, not just the final day. I learned this the hard way with a plan that terminated in November after distributing everything. The auditor initially accepted a Schedule I filing, then six months later sent a correction request saying the plan had 97 eligible participants on January 1st and 43 new eligibles who joined between January and the termination date, pushing the count above 100 for part of the year. The plan ended up filing a revised Schedule H with an additional $2,800 in professional fees. The lesson is that the participant count should be verified early and consistently, not estimated retroactively.

Practical Steps You Can Take Right Now
If you're preparing for an audit this cycle, start by pulling your custodian statements for the entire plan year, not just December 31st. The auditor will ask for monthly or quarterly snapshots anyway, and having them organized saves you from scrambling in February. Request your recordkeeper's participant listing dated as of the measurement date. Cross-reference it with the custodian's asset listing. Reconcile any differences before the auditor does. Prepare a loan receivable schedule if your plan offers participant loans. List each borrower, the original principal, the current balance, the interest rate, and the maturity date. Group them by month so the auditor can see the flow. This is information the auditor expects, and not having it organized means they'll spend more time asking for it and you'll spend more money paying for that time. Review the plan's administrative expense records for the full year. Gather invoices, payment confirmations, and any sponsor reimbursement documentation. Separate direct expenses from reimbursed ones. The financial statement needs to reflect both correctly, and mixing them up creates reconciliation noise that has no place in an audited statement.
Finally, pick your auditor early. The best auditors are booked months in advance because plan filing deadlines cluster in July and April. A good auditor will also tell you upfront which schedules and workpapers they need, so you aren't guessing. Ask them for a checklist before you start. Most will provide one if you ask. Having that checklist turns the process from a vague burden into a structured project you can manage week by week.