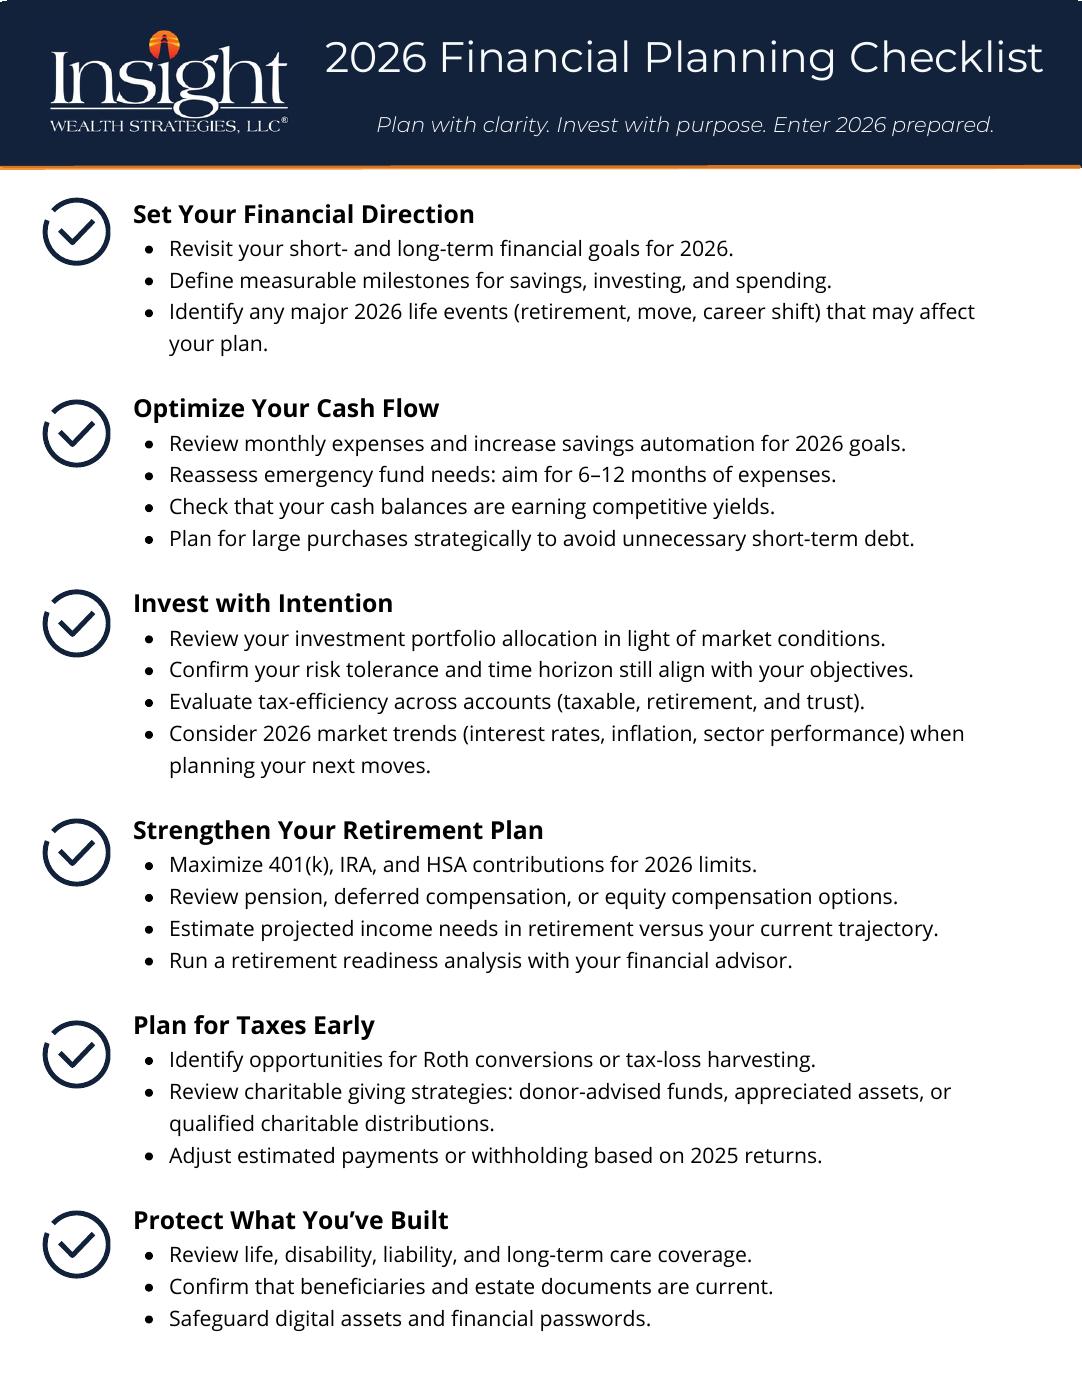
Financial planning isn't glamorous. It's mostly spreadsheets, uncomfortable conversations about money, and realizing too late that you should have started years ago. The good news is that if you have a structured approach, you won't waste time figuring out what to do. You'll just do it.
A lot of people try to build their own checklists from scattered advice they find online. This usually results in a bloated document with redundant items, gaps in coverage, and sections that don't actually apply to their situation. The 46 Point Financial Planning Checklist was built to solve exactly this problem by consolidating every critical area of personal financial planning into one coherent framework. I've used versions of this in my practice for years, and it covers the full lifecycle from emergency funds through estate planning. Here's the breakdown. The 46 points are grouped into six major categories, and each category has sub-items that need to be addressed in order. You start with the basics, which most people skip because they seem obvious. They aren't.
1. Net worth statement - assets minus liabilities, updated quarterly at minimum. I see too many clients who haven't calculated this since 2019. 2. Monthly cash flow analysis - track every dollar coming in and going out for three consecutive months. Not one month. Three. Your March spending is not representative of your spending. 3. Emergency fund calculation - target three to six months of essential expenses. Essential means rent, utilities, groceries, insurance, minimum debt payments. Not your gym membership. 4. Emergency fund placement - high-yield savings account, FDIC insured, separate from checking. Don't put it in a money market fund at your brokerage without understanding the implications. 5. Banking relationships audit - do you have multiple accounts at the same bank? Consolidate. 6. Monthly bill tracking system - automate what you can, schedule what you can't. 7. Subscription audit - cancel anything you haven't used in 30 days. Yes, even the ones you pay annual. 8. Income verification - confirm all income sources are documented and projected accurately for tax purposes.
Category 2: Debt Management (Points 9-14)
Get the Full Details
Financial Planning Checklist | Trust Point
Debt is the most common financial stressor I encounter. It's also the easiest to fix if you're systematic about it. 9. Complete debt inventory - every balance, interest rate, minimum payment, and due date across all accounts. 10. Debt-to-income ratio calculation - total monthly debt payments divided by gross monthly income. Above 43% triggers regulatory concerns for refinancing. 11. High-interest debt prioritization - anything above 8% APR gets aggressive repayment focus. 12. Debt consolidation evaluation - consolidate when the weighted average rate exceeds 10% and you qualify for a lower rate. 13. Balance transfer strategy - useful for card debt below 15% if you can pay it off within the promotional period. I've seen people miss this deadline and end up worse off. 14. Debt payoff projection model - build a timeline showing when each debt is eliminated under different payment scenarios.
Category 3: Insurance and Risk Management (Points 15-22)
This is where people lose money most silently. Underinsurance is far more common than overinsurance. 15. Health insurance review - check network adequacy, out-of-pocket maximums, and prescription coverage annually. 16. Disability insurance evaluation - own-occupation policies are worth the premium if you have specialized skills. 17. Life insurance needs analysis - use the DIME method (debt, income multiplier, college, estate) as a starting point, not the final answer. 18. Term vs. permanent insurance decision - term is sufficient for most people until age 50. After that, reassess. 19. Umbrella liability coverage - $1 million minimum if you have assets above $300,000. Cheap insurance, massive protection. 20. Homeowner's or renter's insurance audit - ensure replacement cost coverage, not actual cash value. 21. Auto insurance review - drop collision on cars worth less than 10x your annual premium. 22. Long-term care planning - consider hybrid life-care policies if traditional LTC insurance premiums are prohibitive.
Category 4: Investment and Retirement (Points 23-32)
Investing is where most DIY investors make costly mistakes. Not because investing is hard, but because their process is unstructured. 23. Investment account inventory - list every account, type, provider, and current allocation. 24. Asset allocation review - align your allocation with your time horizon, not your risk tolerance. They're not the same thing. 25. Fee analysis - calculate the total expense ratio across all holdings. Above 0.75% annually is a red flag for passive strategies. 26. Tax-efficient fund placement - hold bond funds in tax-advantaged accounts, equities in taxable accounts. 27. Employer match optimization - contribute at least enough to get the full employer match. This is free money and the first investment decision you should make. 28. Roth vs. traditional IRA analysis - depends on current vs. expected future tax bracket. If you expect to be in a higher bracket, Roth wins. 29. 401(k)/403(b) contribution strategy - max out before allocating to taxable accounts. 30. Required Minimum Distribution planning - RMDs start at age 73 under current law. Plan for the tax hit. 31. Social Security optimization - claim strategies can add $50,000 to $100,000 in lifetime benefits depending on your situation. 32. Retirement income projection - model your withdrawal rate across different market scenarios, not just the historical average.
2026 Financial Planning Checklist | PDF to Flipbook
Category 5: Tax Planning (Points 33-38)
Tax planning should happen year-round, not just in April. The difference between reacting to taxes and planning for them is significant. 33. Current year tax projection - estimate your total tax liability before the year ends. 34. Estimated tax payment schedule - quarterly payments avoid underpayment penalties. 35. Tax-loss harvesting opportunities - realize losses in taxable accounts to offset gains. 36. Charitable giving strategy - bunch deductions in alternating years if you itemize. 37. Retiree healthcare cost estimation - the average couple retiring in 2024 will spend approximately $315,000 on healthcare in retirement. Budget for it. 38. State and local tax optimization - residency changes can save substantial amounts if you're mobile.
Category 6: Estate and Legacy (Points 39-46)
This category is skipped by most people until something forces their hand. Don't be most people. 39. Will execution - at minimum, a simple will. Costs about $300 to $500 if done properly. 40. Beneficiary designation review - update these after any major life event. Outdated beneficiary designations override wills. 41. Trust evaluation - revocable living trusts avoid probate and provide incapacity planning. 42. Power of attorney for finances - name a trusted agent with clear instructions. 43. Advance healthcare directive - specify your wishes for end-of-life care. 44. Digital asset inventory - list accounts, passwords, and access instructions. This is increasingly important and increasingly overlooked. 45. Letter of instruction - non-legal document that explains your wishes, account locations, and important contacts. 46. Annual review and update schedule - set a calendar reminder to review everything every January. I ran into a case last year where a client had completed about 35 of the 46 points but had never done a beneficiary designation review. His 401(k) from a previous employer still named his ex-spouse as beneficiary. The plan administrator followed the beneficiary designation over the will. That account, worth roughly $180,000, went to someone he hadn't spoken to in twelve years. The workaround was straightforward - he filed a post-death claim with the plan administrator citing state domestic relations order provisions, but it cost him six months of legal fees and stress that could have been avoided with a single form.
There are real limitations to this checklist approach. It assumes you have all the information needed to complete each point. If you've lost records, had accounts forgotten, or have incomplete beneficiary designations, the process slows down significantly. The checklist also doesn't account for complex situations like business ownership, international assets, or special needs dependents. In those cases, you need professional guidance beyond what any checklist can provide. The biggest counter-intuitive insight most people miss is that the order of the checklist matters less than the consistency of the review. A client who completes all 46 points once a year and then does nothing is better off than a client who completes points 1 through 12 and then disappears for three years. The second client has gaps in coverage that create real risk. Another thing beginners consistently underestimate is the time investment. Completing the full checklist the first time takes approximately 8 to 12 hours if you have good records. With poor records, it can take 20 hours or more. Budget accordingly. Subsequent annual reviews take about 2 hours if you stay organized.
If you want the actual checklist document, it's widely available through financial planning professional associations and several reputable financial education platforms. Look for versions that are marked as CFP Board aligned, as those tend to be the most thorough and current.
Gallery 46 Point Financial Planning Checklist
Financial Planning Checklist | Emerj360
7+ Free Planning Checklists to Achieve Financial Goals in MS Word in 2024 | Financial checklist ...