What a 5/1 ARM Actually Looks Like in Practice
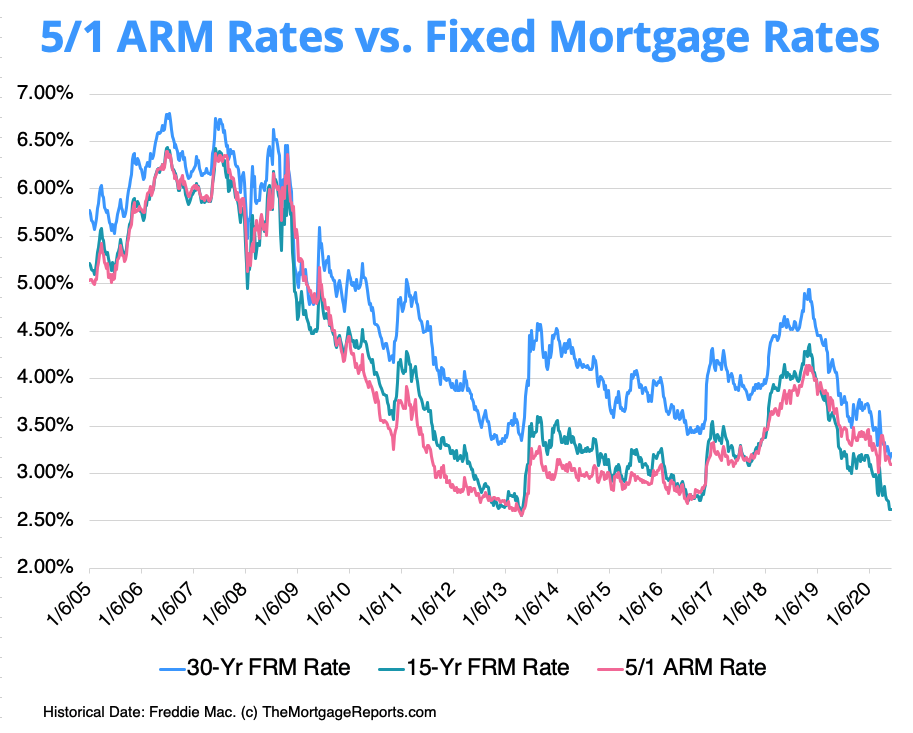
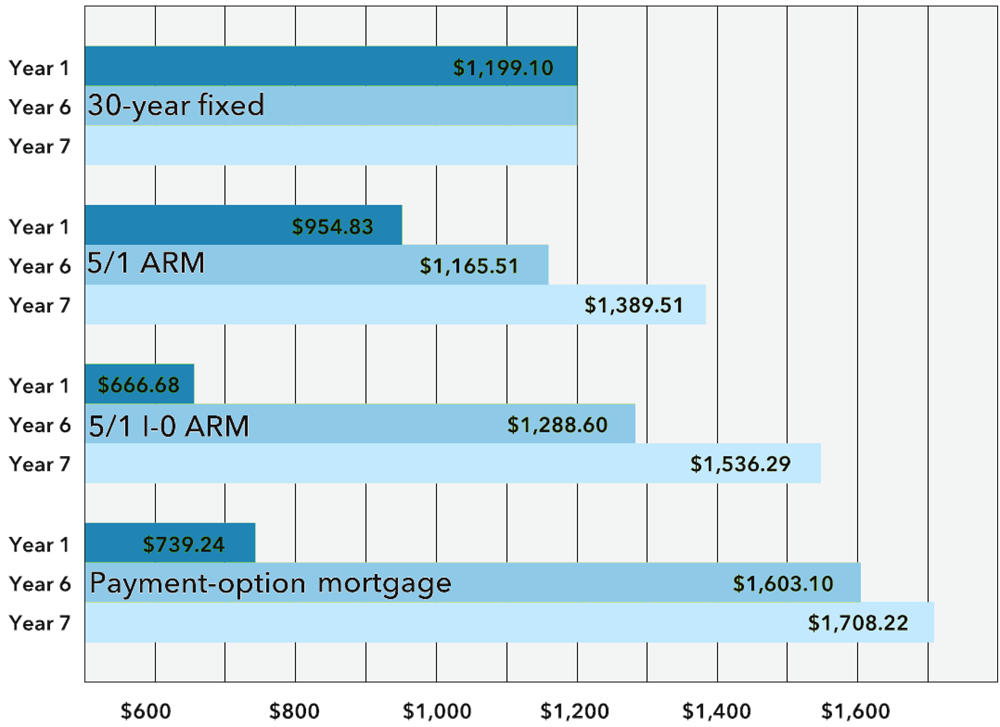
A 5/1 adjustable-rate mortgage starts with a fixed rate for five years, then resets every year after that. The initial rate is usually lower than what you'd get on a 30-year fixed, which is why people buy them. But the math behind it gets messy fast, and most calculators online don't show you the full picture. They give you one payment number and call it a day. That's not useful. Start by entering your loan amount, the initial interest rate (the teaser rate lenders advertise), your loan term, and the adjustment parameters. Most standard online calculators let you plug in the margin and the index, but far too many people skip those fields and get misleading results. The margin is usually around 2.5% to 3% on a 5/1 ARM, and the index is typically the COFI or the One-Year Treasury. Lenders add the margin to the index value to get your fully indexed rate. That number is what your rate will eventually settle toward, not the initial teaser rate. Run the calculation for at least three different scenarios: one using the initial rate, one using the current fully indexed rate, and one assuming the rate hits the periodic cap each adjustment period. That third scenario is the one most people ignore, and it's the one that matters when you're trying to figure out whether you can actually afford this loan in year six.
I've watched borrowers get handed payment estimates from calculator sites that assumed the rate would stay at 3%. The fully indexed rate on their loan was 6.5%. The difference was over a thousand dollars a month. I had to recalculate everything from scratch using the actual index value at the time of closing plus the stated margin, then apply the lifetime cap to show them the worst-case payment. The borrower ended up switching to a fixed-rate loan after seeing those numbers.
What the Calculators Don't Tell You
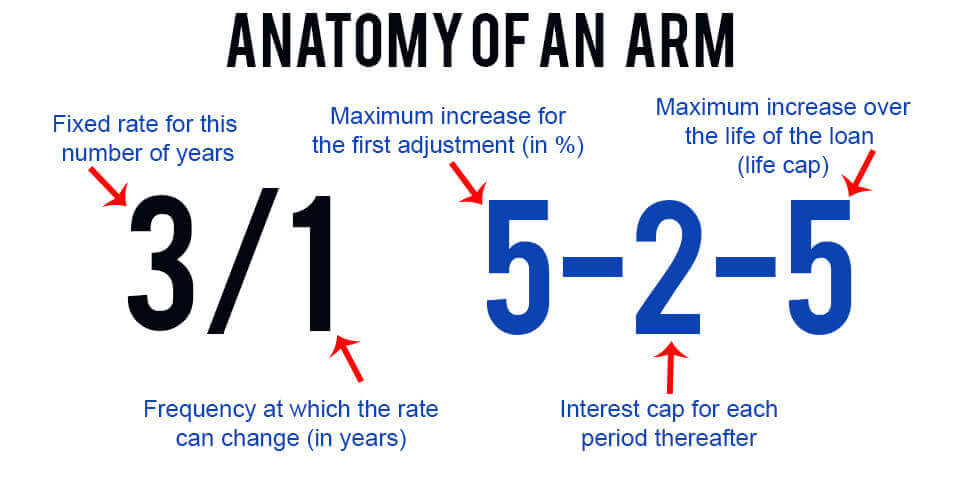
Most 5 1 Arm Mortgage Calculator tools output a single monthly payment figure based on the initial rate. They rarely show what happens during the adjustment period, and almost never display the amortization schedule after the first reset. That omission is deliberate. It makes the loan look more affordable than it actually is. The real payment after year five depends on three things: the current value of the index, the lender's margin, and the cap structure. A standard 5/1 ARM has a 2% periodic cap, meaning the rate can only increase by two percentage points per adjustment, and a 5% or 6% lifetime cap. If you're at 3% during the initial period and rates climb, you won't hit the lifetime cap immediately, but you'll get close enough to hurt. Another thing calculators rarely address is how the payment is rounded. Some lenders round up to the next dollar. Others use precise cent calculations. Over 30 years, that rounding difference can add up to a few hundred dollars in extra principal. Not huge, but worth noting if you're doing this math by hand.
Get the Full Details
Common Mistakes That Break the Math
The biggest mistake I see is people using the advertised rate as the starting point without checking what the index was on the day they locked. If the index moves between when you see the rate and when you sign, your actual rate at closing could be different. The initial rate is usually a discount off the fully indexed rate, so if the index jumped, your discount might shrink and your starting rate could be higher than expected. A second mistake is assuming the payment stays flat after year five. It doesn't. The payment recalculates based on the new rate and the remaining balance. Your principal and interest portion will change, and if your escrow includes taxes and insurance, those can change too. The total payment can jump significantly in year six, even if the rate cap limits how much the interest rate increases. I had a client once who used a calculator that only showed the first five years of payments. He thought he could afford the loan because the monthly payment was under $2,000. In year six, the payment jumped to $2,680. He'd qualified based on the initial rate, not the adjusted rate, and his debt-to-income ratio was fine at closing. But once the payment reset, he was underwater within fourteen months and had to refinance into a fixed loan at a higher rate because his credit had dropped from payment stress.
Advanced Inputs That Actually Matter
If you want accurate numbers, you need to include the index source, the margin, the cap structure, and the date of the first adjustment. Most basic calculators don't ask for all of these. The ones that do tend to be more clunky and harder to use. There's a trade-off between ease of use and accuracy, and most people pick the easier option and get worse results. Some calculators let you input prepayment scenarios, which is useful. If you plan to sell the house before year five, the adjustable portion doesn't matter much. If you plan to stay longer, you need to model at least years six through ten to see the trend. Running a ten-year projection with annual resets takes about thirty seconds in any decent calculator and gives you a much clearer picture than a single payment estimate.
When a 5/1 ARM Makes Sense and When It Doesn't
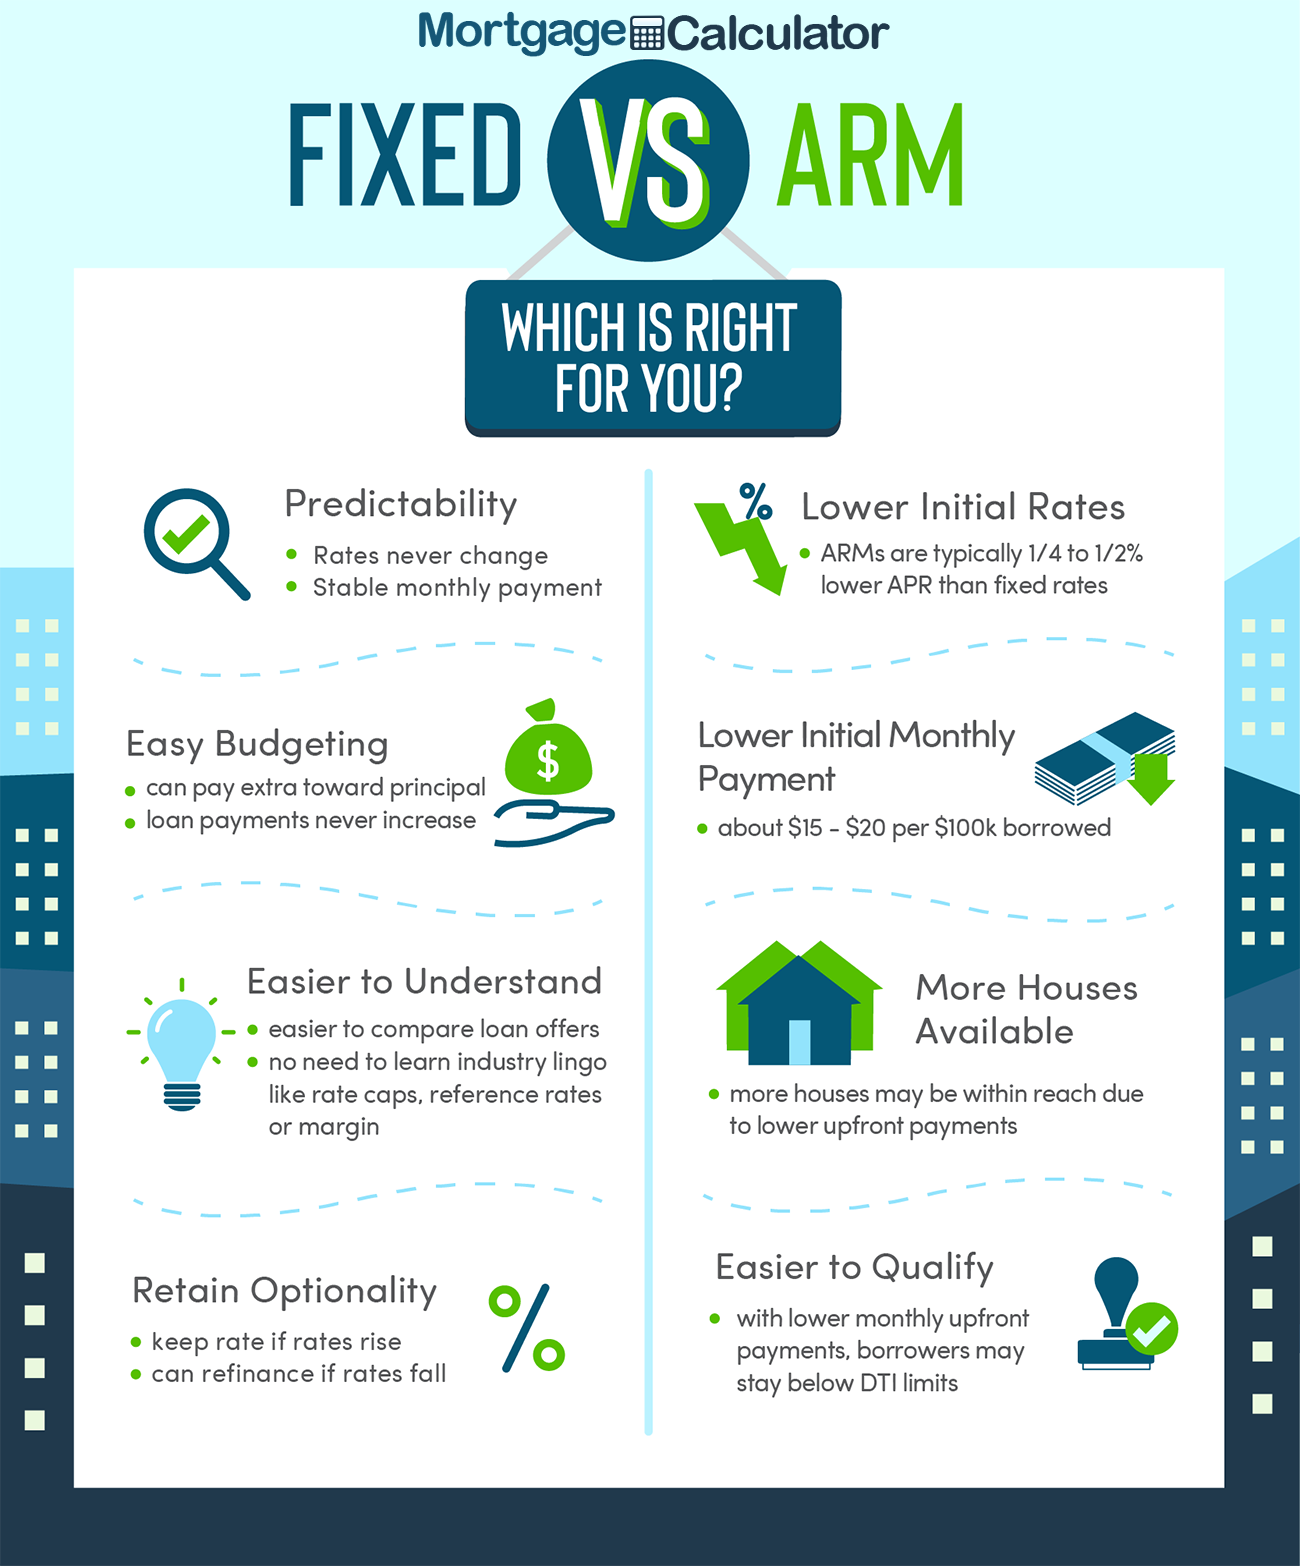
A 5/1 ARM is reasonable if you know you'll sell or refinance before the adjustment period begins. It's also reasonable if your income is likely to increase significantly within five years and you can absorb a payment increase. It's not reasonable if you're already stretched thin on your current budget. A $500 monthly increase in year six is manageable for some people. For others it's catastrophic. The calculator can show you the number, but only you can determine whether it's survivable. Fixed-rate mortgages are simpler. The payment never changes. That simplicity has a cost, which is why the initial rate on a 5/1 ARM is usually lower. You're trading predictability for a lower starting rate. Whether that trade is worth it depends on your timeline, your financial cushion, and your tolerance for uncertainty. The best approach is to run the calculator with multiple rate scenarios, review the output carefully, and then compare it against your actual budget constraints. Don't rely on a single number from a calculator page. Get the detailed schedule if possible, and if the tool you're using doesn't provide one, find a different calculator or work with a loan officer who can generate the full amortization.