Understanding How 5/1 Adjustable-Rate Mortgages Actually Move
A 5/1 ARM means your interest rate is fixed for the first five years, then it adjusts once a year after that. A 5 Year Arm Rates Calculator takes your starting rate, the index it's tied to, the margin the lender adds, and the periodic and lifetime caps, then projects what your payment looks like year by year under different rate scenarios. The math isn't complicated, but the details matter more than most people expect. You need these inputs: Initial fixed rate — the teaser or locked rate for years one through five.
Index — usually the 1-Year Treasury, COFI, or SOFR depending on the lender.
Margin — the lender's spread added on top of the index, typically 2 to 3 percentage points.
Adjustment cap — how much the rate can change each adjustment period, usually 2%.
Lifetime cap — the maximum rate above the initial rate over the full loan term, usually 5 to 6%.
Loan amount and term — same as any mortgage calculation.
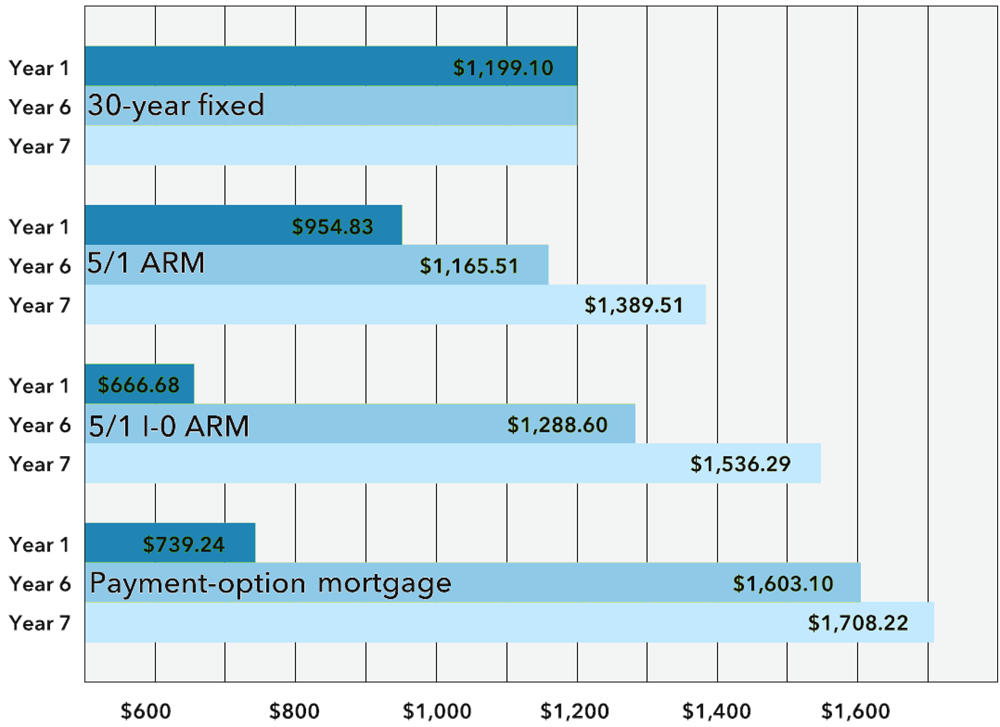
Here's the basic formula that underlies the tool: New Rate = Index Value + Margin, capped at whichever limit applies — the periodic cap, the lifetime cap, or the previous rate plus/minus the adjustment allowance. Then you plug that rate into the standard amortization formula to get the monthly payment for that year's balance and remaining term. I built a simple one that outputs a year-by-year schedule with payment projections. It's not a mortgage calculator for approval purposes — it's a decision tool. You use it to see what happens if rates spike or if they fall, so you can compare the total interest cost against a 30-year fixed at a given point in time. The tricky part most people miss is that ARM payments don't just scale linearly with rate changes because the amortization term shortens each year. When the rate resets higher, your payment goes up, but you're also paying down principal faster than the early years of a fixed loan, so the principal balance is lower than a straightforward projection would suggest. The calculator handles this by running a true amortization each year rather than just multiplying the original payment by a rate ratio.
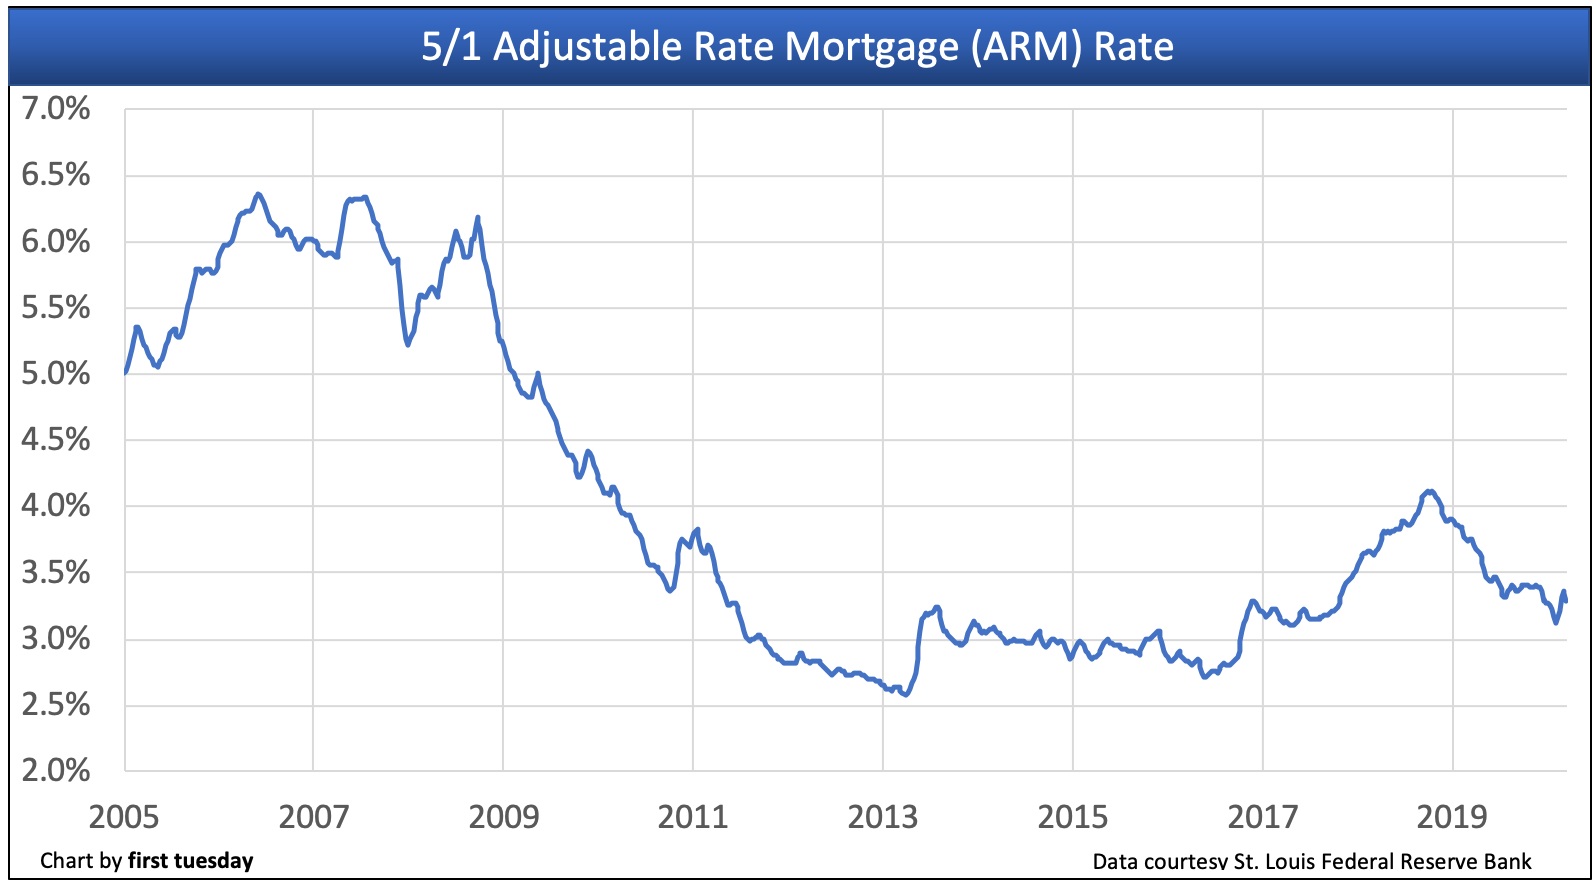
I ran into a specific edge case last year where a borrower was comparing a 5/1 ARM against a 30-year fixed at a time when the Treasury yield curve was deeply inverted. The index at that moment was actually higher than the long-term Treasury rate because of the inversion, which made the ARM's reset look worse on paper than it turned out to be. The workaround was to model the scenario using a forward-looking spread assumption instead of just the current index value, and to account for the fact that the Federal Reserve typically cuts rates when the curve is inverted as a recession signal. The calculator let me run both scenarios side by side — current index value and a projected average index over the next five years — which made the comparison honest instead of fear-mongering. Another thing beginners consistently overlook: payment caps. Some ARMs have payment caps that limit how much your monthly payment can increase at each adjustment, regardless of what the rate does. This creates negative amortization, where the payment doesn't cover all the interest due and the shortfall gets added to the principal. I've seen borrowers who didn't even know their loan had a payment cap until they got their first adjustment notice and the balance went up instead of down. If the loan you're analyzing has a payment cap, the calculator needs to flag that and show the accrued unpaid interest being capitalized. There are real limitations to what this tool can tell you. It assumes the index moves exactly as you project, which is impossible to know. It doesn't account for changes in your loan balance from extra payments or refinancing mid-adjustment. It won't tell you whether your specific loan contract has an option to convert to a fixed rate at reset, which some ARMs allow and which can be a massive safety valve. And if you're in a state with anti-deficiency laws or particular prepayment penalty structures, those aren't reflected here.
Get the Full Details

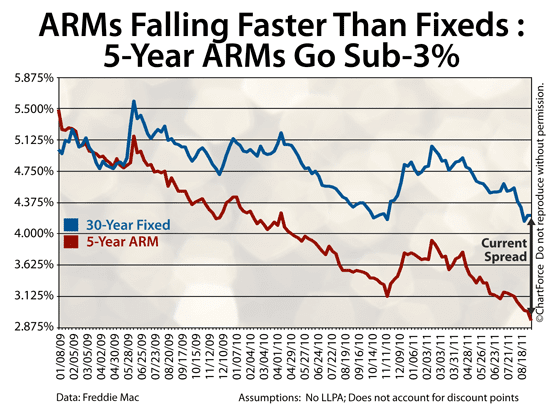
For a quick download or web version, I keep the calculator at a simple single-page tool that takes the inputs above and outputs a twelve-row table showing the projected rate, payment, and remaining balance for each year through year ten, with a cumulative interest column so you can do a head-to-head comparison with a fixed-rate loan. It runs in the browser, no account needed, and the source is plain JavaScript if you want to audit the logic yourself. The biggest practical insight is that the five-year window is where most of the risk and reward live. If you plan to sell or refinance before year six, the ARM is usually cheaper than a fixed loan by a meaningful margin — often two to three percentage points in the initial rate. If you stay past year five and rates move against you, you're exposed to annual adjustments that can climb toward the lifetime cap. The calculator helps you model both paths so you're not just picking the lowest starting rate without looking at what year six through ten actually cost you.