Understanding a Fifty-Thousand Dollar Mortgage Over Thirty Years
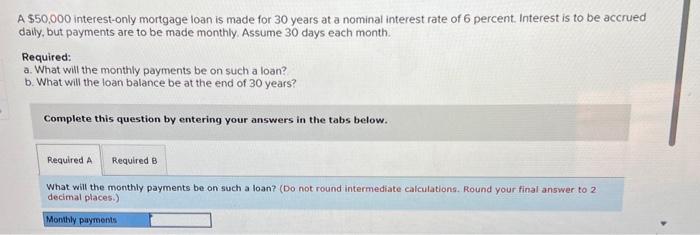
You are probably looking at this because you either have a $50,000 loan to manage or you are shopping for a property that involves a loan of this size. Either way, the math is the same whether it is a first mortgage, a home equity loan, or a construction loan. Here is the breakdown. Using a standard amortization calculation, a $50,000 principal at 6.5% interest over 30 years gives you a monthly principal and interest payment of approximately $316. That is the base number. It does not include taxes, insurance, or HOA fees. Those are layered on top by the servicer and can add $100 to $300 per month depending on where the property is located. I have seen people look at the $316 figure and forget to budget for the rest, then get surprised four months into ownership when the escrow shortage hits. If you are shopping around, the rate you actually qualify for depends heavily on your credit score, debt-to-income ratio, and whether this is a primary residence or an investment property. Investment properties typically carry rates 0.5% to 0.75% higher. At 7.25% the payment climbs to about $341 per month. At 5.75% it drops to roughly $292. The difference over the life of the loan is about $26,000 in total interest between those two rates.
I ran into a real problem once with a client who refinanced a $50,000 balance at what looked like a great rate. The lender included points and origination fees that pushed the actual yield-to-maturity well above the advertised rate. He thought he was getting 6% but the all-in cost was closer to 6.8%. The workaround was simple but easy to miss: I asked for the Loan Estimate form with the APR and total interest column filled in, then compared that against the monthly payment. Never trust the advertised rate alone. Compare the APR across at least three lenders and calculate the break-even point if you are paying points to buy down the rate. On a $50,000 balance, buying a rate down is rarely worth it unless you are spending very little in fees. Spending $2,000 to drop 0.5% on a small balance means you would need roughly seven years just to recoup the cost in lower payments. One thing most people do not realize: on a $50,000 mortgage, the early years are almost entirely interest. In the first year at 6.5%, you will pay roughly $3,200 in interest and only about $580 toward principal. That is the nature of amortization. It does not matter if the loan is $50,000 or $500,000—the front-loading of interest is structurally identical. The only thing that changes is the absolute dollar amount. This matters if you are planning to sell within five years. You will not have built meaningful equity from the mortgage payments alone. You would need to rely on appreciation or make extra principal payments. Extra principal payments are where you can actually change the shape of this loan. If you pay an additional $50 per month toward principal, you cut the term by about seven years and save roughly $8,500 in interest. If you can swing $100 extra each month, you shave off nearly eleven years and save over $15,000. Most servicers will apply overpayments directly to principal if you specify that in writing. Do not assume it happens automatically. I had a borrower once who sent extra payments for three years and never saw the balance move. His servicer was applying everything to future installments instead of reducing principal. A single email to the servicing department and the next payment cycle corrected it.
There are scenarios where a 30-year fixed at this balance is simply the wrong tool. If you expect to relocate within five to seven years, a 15-year loan or an adjustable-rate mortgage with a fixed period might make more sense financially. The monthly payment on a 15-year at 6% would be around $426, but you would be debt-free in half the time and save roughly $17,000 in total interest. The tradeoff is a significantly higher monthly obligation. If cash flow is tight, the 15-year payment could strain your budget and create risk you do not need. If your credit is below 620, you may not qualify for conventional terms at all. Subprime or non-QM loans exist but carry rates that can exceed 9%. At 9% the monthly payment on $50,000 over 30 years jumps to approximately $402. That is a painful difference. A better path in that situation is often to spend a year improving the credit profile, reducing existing debt, and then reapplying. Every 30-point increase in your score can move you into a different rate tier. For reference, here is a quick snapshot of what this looks like at various rates:
Get the Full Details
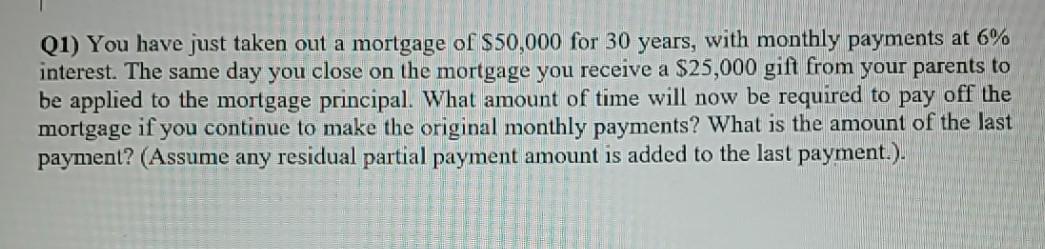
At 5.5%: monthly payment is about $284. Total interest over 30 years is approximately $52,151. At 6.5%: monthly payment is about $316. Total interest over 30 years is approximately $63,789. At 7.5%: monthly payment is about $349. Total interest over 30 years is approximately $75,759.
The total interest paid on a $50,000 loan over 30 years is always going to exceed the principal at any rate above zero. That is not a trick or a hidden fee. It is how amortization works. The only way around it is to pay down the principal faster than the scheduled payments require, or to refinance when rates drop and your qualification improves.