So You Want a 50 Year Mortgage
Most people asking about a 50 year mortgage have hit a wall with affordability and think extending the term is the answer. It's not that simple. The product barely exists in any meaningful form across mainstream markets. What does exist carries some ugly baggage that most borrowers never see coming. I spent years watching deals fall apart over term length alone, so I'm going to be straight about what's actually available and what happens when you try to push past the normal 30-year ceiling.The 50 Year Mortgage Reality
You're not going to find a conventional 50 year mortgage at any bank, credit union, or online lender in the US, Canada, UK, or Australia. The standard maximum is 30 years in the US and 25 years in Canada and the UK. There are a few narrow exceptions. The US FHA program briefly offered a 50-year option for manufactured housing in certain years under specific conditions. Malaysia allows mortgages up to 35 years, which is the longest you'll find in Asia-Pacific. Some niche products in countries like Japan go very long, but that's a different market entirely. If you encounter a lender advertising a 50 year mortgage in a developed market, treat it as a red flag. It's either a scam, a predatory product with hidden fees, or a misunderstanding of what they're actually offering.I worked a case a few years back where a borrower was told by a broker they could get a 50 year mortgage. What the broker actually meant was a 30 year mortgage with a 50 year amortization built into the underwriting for debt-service calculations. The loan documents said 30 years. The monthly payment was calculated as if it were 50 years. The borrower thought they had 20 extra years of relief. When the 30-year term hit, the balloon payment was catastrophic. We ended up restructuring through a refinance into a second mortgage, but the borrower lost roughly $47,000 in equity and spent 14 months in court fighting the broker. Never skip reading the actual loan agreement.
Why Lenders Won't Give You 50 Years
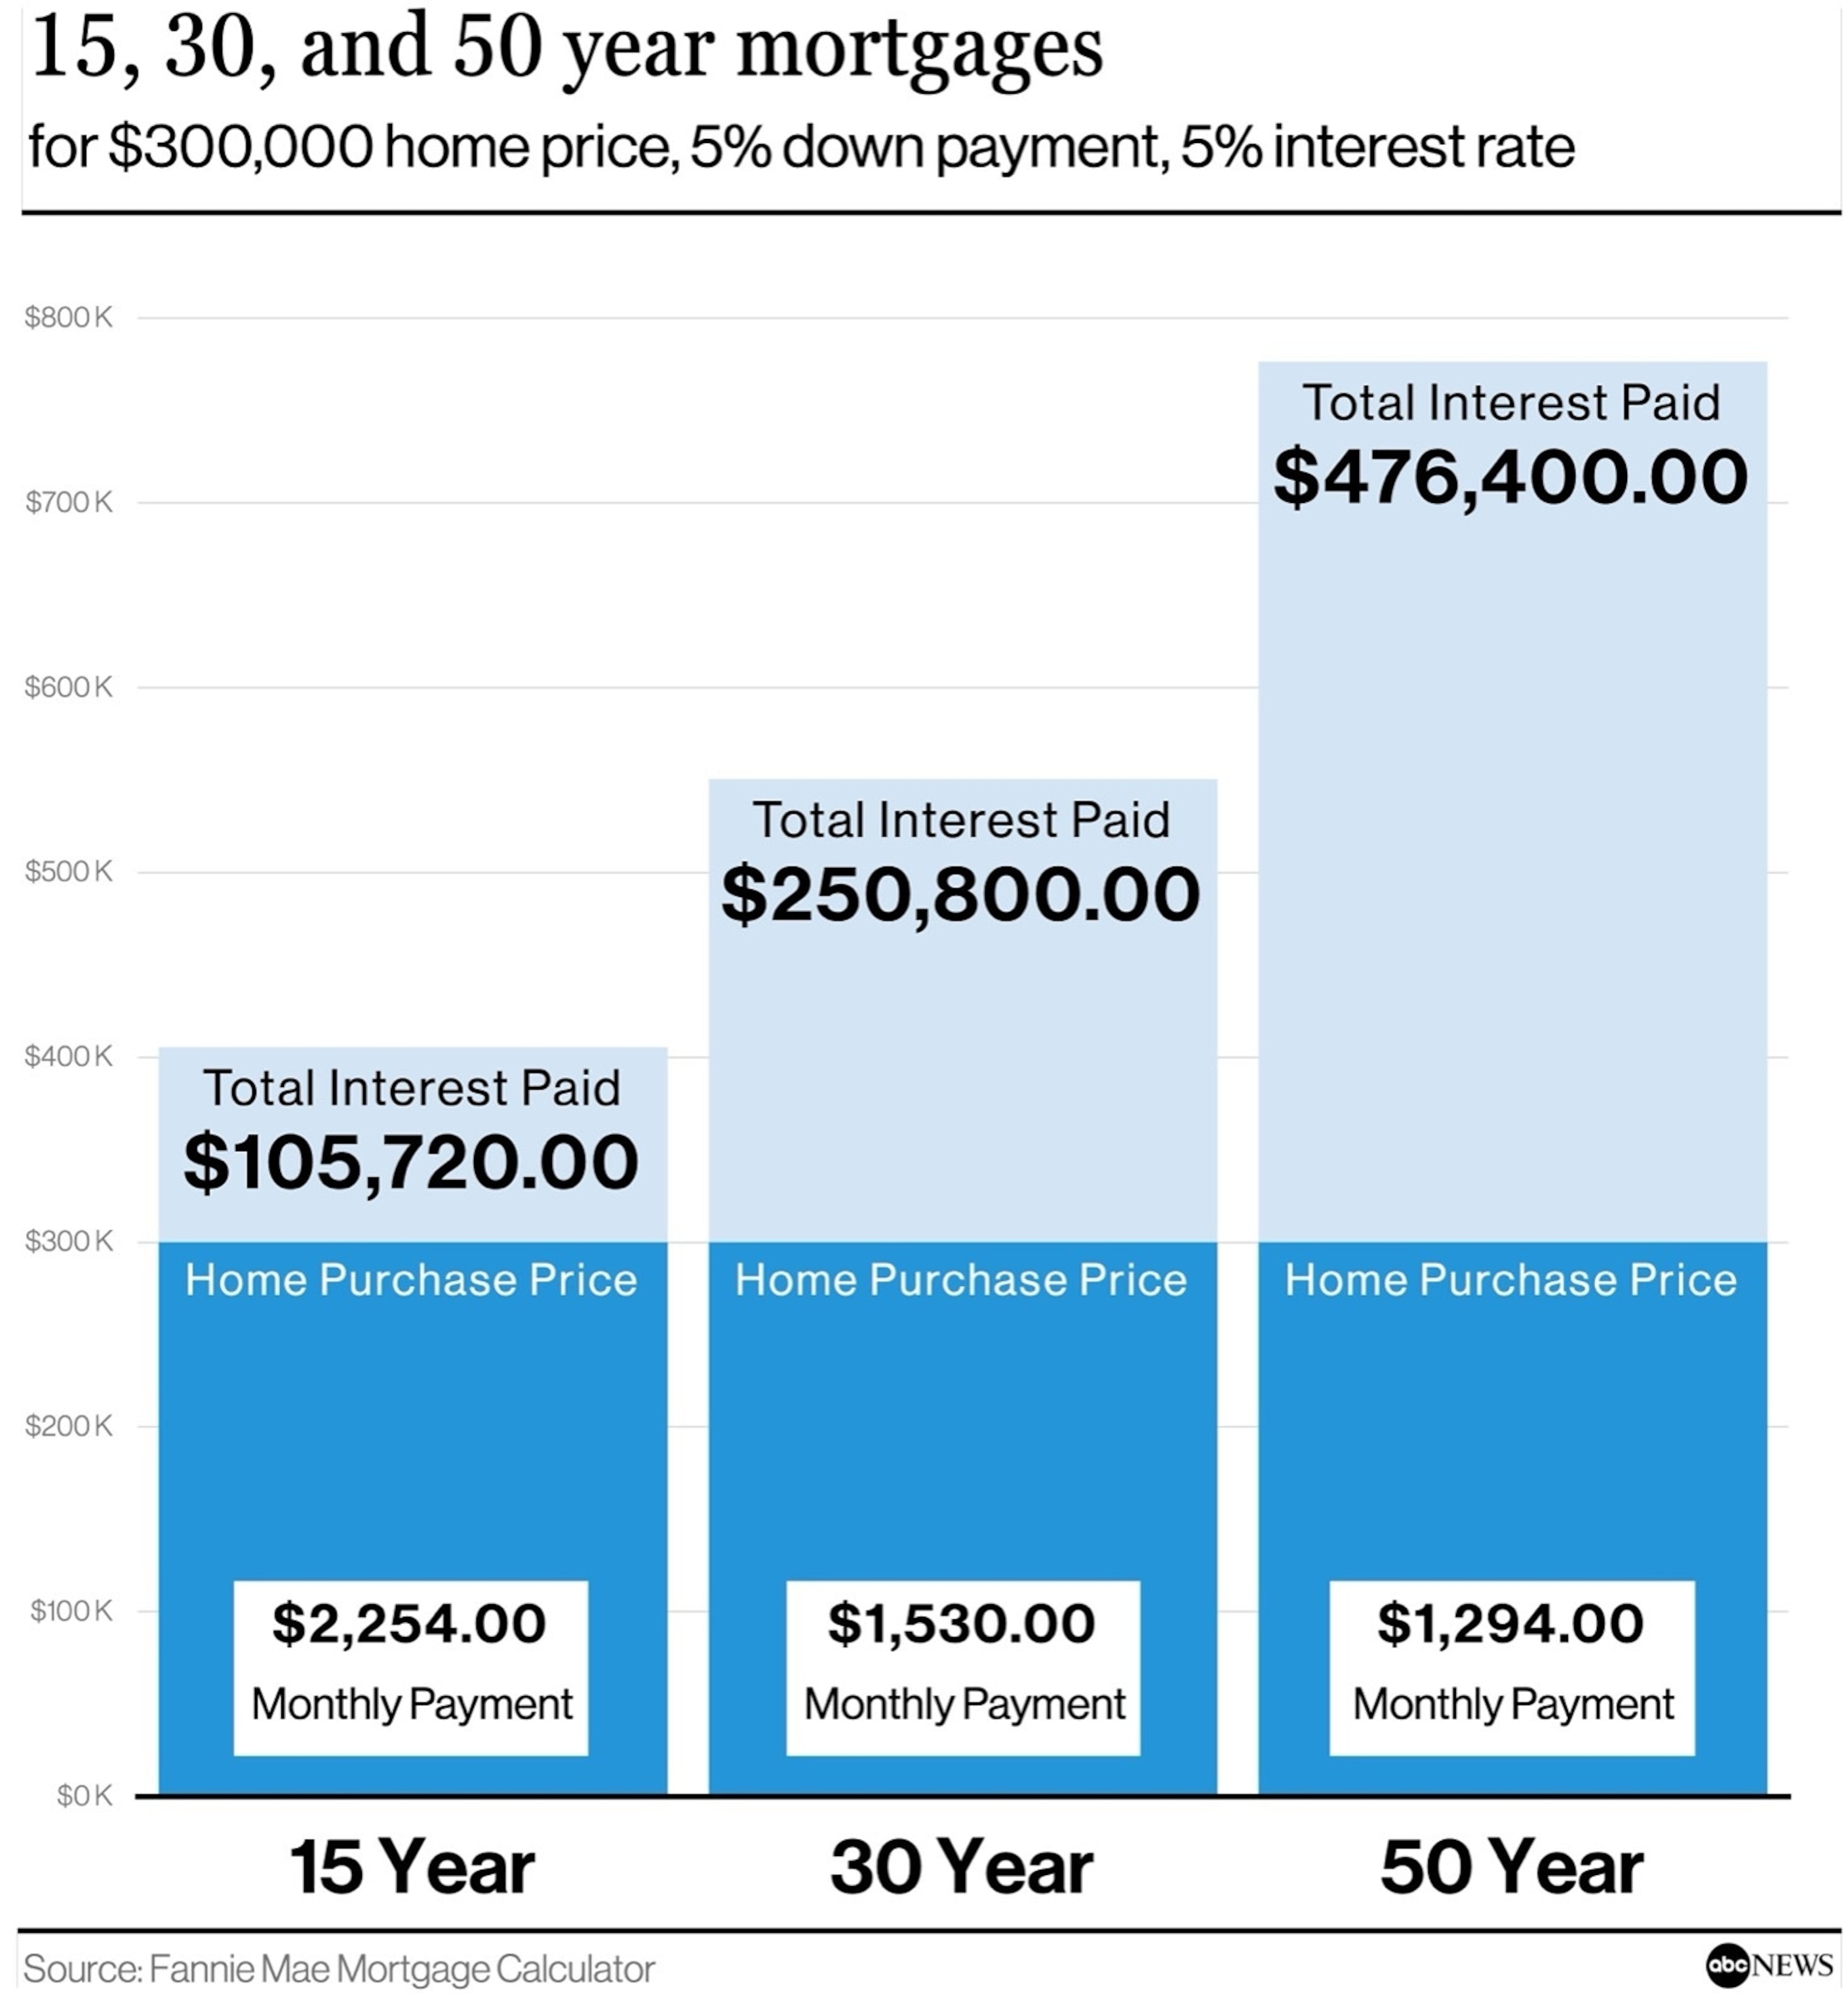
The math is straightforward. A 50 year mortgage at 6.5% on a $400,000 loan results in a monthly payment of roughly $2,383. The total interest paid over the life of the loan is about $1,029,600. That's 2.5 times the original principal. Most lenders won't touch that because the recovery period on default stretches so far out that the risk model breaks down. By year 15, you'll have paid somewhere around $214,000 in interest and only reduced the principal by roughly $62,000. You're deep in negative-equity territory with barely any upside if you need to sell. There's also the problem of collateral risk. Property values don't reliably appreciate for 50 years. Insurance, taxes, and maintenance obligations stay constant or increase. A borrower who takes on a ultra-long amortization is betting everything on real estate gaining value faster than the mortgage balance shrinks. That bet has lost more often than it wins over multi-decade spans.The one scenario where I've seen extended amortization make marginal sense is in commercial real estate with triple-net leases from investment-grade tenants. The cash flow is predictable enough that lenders will stretch to 35 or 40 years on the backend. Even then, the rate is usually 100 to 200 basis points above what you'd get on a standard term. Residential is a completely different beast.
What You Should Do Instead
If you need lower monthly payments, there are several better options than chasing an impossible 50 year mortgage.Extend to the maximum available term. In the US, that's 30 years. In Canada, 25 or 30 depending on the province and lender. In the UK, 25 to 30. Shop around. Some smaller lenders and credit unions will go to 35 years on jumbo loans. I found a regional bank in Texas that did 35 years on conforming loans for first-time buyers. The rate was 0.125% higher than their 30-year product. Worth it if your cash flow is tight. Get a shorter loan with a second lien. This is a less common strategy but it works. Take a 15-year mortgage at a lower rate and cover the rest with a home equity line of credit or a second mortgage at a higher rate. Your primary payment stays manageable and you build equity faster on the first lien. The downside is you have two payments and two sets of closing costs. Factor that in. Look at government programs. FHA loans cap at 30 years but allow lower down payments and more flexible credit. VA loans do the same for eligible borrowers. USDA loans are another option in rural areas. None of these go to 50 years, but the qualification bars are significantly lower.
Consider an adjustable-rate mortgage. An ARM with a 7-year fixed period followed by adjustments can give you lower initial payments. If you plan to sell or refinance within that window, you save on interest. The risk is payment shock after the fixed period ends. I had a client in Arizona who took a 7/1 ARM in 2021 when rates were around 2.75%. She sold in 2024 before the adjustment kicked in and saved roughly $18,000 in interest compared to a 30-year fixed. She got lucky with timing. That's not a strategy you can count on.
The Hidden Costs Nobody Talks About
Even the longest available mortgages carry costs that compound over time. PMI on loans with less than 20% down can run 0.5% to 1.5% of the loan amount annually. On a $350,000 loan with 5% down, that's $1,750 to $5,250 per year until you hit 20% equity. On a 30-year mortgage, you might not reach that threshold until year 7 or 8. Over the full term, PMI could cost you $15,000 or more.Tax deductions on mortgage interest have narrowed significantly since the 2017 tax reform in the US. You can only deduct interest on up to $750,000 of mortgage debt for most taxpayers. That cap matters less for lower-priced homes but bites hard in expensive markets. If you're relying on the deduction to make a long-term mortgage affordable, run the numbers without it first. Prepayment penalties are another trap. Some extended-term products include them. A 2% prepayment penalty on a $400,000 loan is $8,000. If you want to refinance or sell before the term ends, that fee eats into your proceeds. Always check the fine print.
Get the Full Details
When a Long Amortization Actually Makes Sense
I'm not saying every long-term mortgage is a bad deal. There are cases where it's the rational choice. Investors who buy rental properties sometimes use maximum amortization to keep cash flow positive during the hold period. The rental income covers the payment, and they plan to refinance or sell before the amortization schedule becomes a burden. This works when the property appreciates or when you can add value through renovations. It fails when vacancy rates climb or major repairs hit unexpectedly.Another scenario is purchasing in a high-cost market with limited income. A borrower making $85,000 a year in San Francisco might qualify for a 30-year mortgage at 6.75% on a $900,000 home. The payment would be roughly $5,850 per month. Without the full 30 years, the payment jumps to over $7,200. The extra $1,350 per month might make the difference between buying and renting. In that case, 30 years isn't a mistake. It's the only path that works. In the US, the closest thing is the FHA 50-year manufactured home loan I mentioned earlier. It requires the home to be classified as personal property rather than real estate in many cases. That changes your rights as a borrower significantly. You don't get the same foreclosure protections. The loan terms are less favorable. It's a narrow product for a narrow situation. If none of these work, look at rent-to-own agreements or seller financing. These aren't mortgages but they can achieve similar goals. Seller financing lets you negotiate whatever terms you want, including a 50 year payoff schedule. The catch is the seller has to be willing, and the interest rate is usually higher than conventional financing. I worked one deal where the seller agreed to 40 years at 8% with a balloon payment due in year 15. The buyer refinanced into a conventional loan three years early and closed the balloon. Both sides walked away satisfied. That kind of flexibility only exists outside the traditional banking system.
The bottom line is that a true 50 year mortgage is largely a myth in most of the world. The alternatives are imperfect but they're real. Understand your numbers, read every document, and don't let a broker sell you something that sounds good until you verify what's actually in the contract. Your future self will thank you.