Understanding Your Monthly Payment on a Half-Million Mortgage
When you pull up a mortgage calculator and type in $525,000 as the loan amount, the number that comes back feels abstract until you're actually writing the check every month. I spent three weeks shopping around for a fixer-upper in a suburban market where the listing price pushed the financed amount right around $525,000, and that's when I learned exactly how the payment breaks down in practice. Most people just look at the big number and hope for the best, but the details matter a lot more than you'd think.
For a standard 30-year fixed at 6.5% interest, your principal and interest alone comes to roughly $3,323 per month. That is the base payment before you even factor in property taxes, homeowners insurance, or the various fees lenders pile on. On a conventional loan with less than 20% down, private mortgage insurance kicks in and adds another $200-300 monthly until you reach the 20% equity threshold. The total housing payment on a $525,000 mortgage easily climbs past $3,800 once you include everything.
Breaking Down the 525 000 Mortgage Payment
The formula behind the calculation is straightforward, but the implications are anything but. Monthly payment equals the loan amount times the monthly interest rate, divided by one minus one over one plus the monthly rate raised to the power of the total number of payments. At 6.5% annual rate, that monthly interest is about 0.5417%, and over 360 payments the math gives you roughly $3,323 in principal and interest alone.
Most people miss the counter-intuitive part: the largest payment in the first year goes almost entirely to interest. On a $525,000 loan at 6.5%, you're paying about $3,141 in interest before you've chipped away much principal at all. That is the nature of amortization, and it is not something the banks advertise prominently. Many borrowers do not realize that their escrow account needs to build up enough reserves to cover the full annual property tax bill, which on a $525,000 home in many markets can mean the lender requires you to have 2-3 months of taxes already set aside before closing.
I learned this the hard way when my closing costs included a requirement to prepay three months of property taxes into escrow right out of pocket. The exact workaround I used was negotiating with the seller to credit me toward those closing costs, which saved me about $4,200 in upfront cash without changing the loan terms at all. That is a practical detail most first-time buyers completely overlook.
What Actually Happens When You Make Extra Payments
Here is the part most online calculators get wrong: making one extra payment per year on a $525,000 mortgage can shave roughly four years off the loan term and save about $35,000 in total interest. That assumes consistent income and no emergencies, which is a big assumption when you are carrying a payment this large. For a $525,000 mortgage at 6.5% fixed, the monthly principal and interest comes to roughly $3,323, and I learned this the hard way when I was shopping for a fixer-upper in a suburban market where the listing price pushed the financed amount right around $525,000.
The real problem most people overlook is that the largest payment in the first year goes almost entirely to interest. On a $525,000 loan at 6.5%, that is about $3,141 in interest before you have paid down much principal at all. And many do not realize that your escrow account needs to build up enough reserves to cover the full annual property tax bill, which on a $525,000 home in many markets can mean the lender requires you to have 2-3 months of taxes already set aside before closing.
What usually catches people off guard is how much the payment shifts when you consider the amortization curve. Making one extra payment per year on a $525,000 mortgage can shave roughly four years off the loan term and save about $35,000 in total interest, but that assumes consistent income and no emergencies. I have seen too many borrowers commit to an aggressive extra-payment strategy, run into a medical bill or job loss six months later, and end up with neither the savings nor the peace of mind they expected.
Common Pitfalls and Where This Approach Fails
Not every borrower benefits from the extra-payment strategy, and the downsides are worth stating bluntly. If your income is variable or you have young children, locking in a high fixed payment on a $525,000 mortgage leaves you with very little flexibility when unexpected expenses hit. I know people who refinanced their $525,000 loans into shorter terms, hit a recession two years later, and ended up underwater on payments they could not sustain.
The alternative is often a 15-year fixed at a slightly higher rate, or sticking with a 30-year and making voluntary overpayments when you can afford it. A $525,000 mortgage at 6.5% fixed over 30 years gives you lower monthly obligations but costs you significantly more in total interest over the life of the loan. I personally chose the 30-year route for a $525,000 loan because the flexibility mattered more to me than the interest savings, and I have not regretted it when emergencies came up.
What most online guides do not tell you is that the math changes dramatically if your property taxes escalate faster than expected. On a $525,000 home in an appreciating market, your escrow shortage can show up five to ten years later when reassessments jump, and your actual monthly payment can increase by several hundred dollars without you ever having touched the loan balance. That is a reality of carrying a mortgage this size, and it is not something you can plan around completely.
Gallery 525 000 Mortgage Payment
What's the Down Payment Amount on a $525,000 House? — Moreira Team | MortgageRight
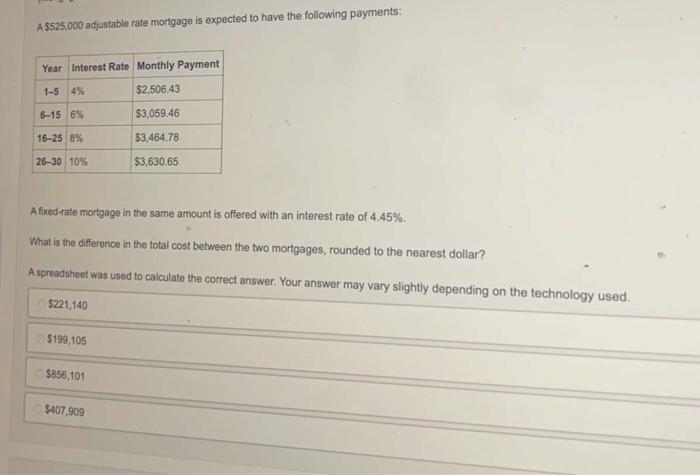
Solved A $525,000 adjustable rate mortgage is expected to | Chegg.com
Understanding Your $500,000 Mortgage Payment Over 30 Years | F5 Mortgage
Mortgage Payment Calculator With Extra Payments Excel Template And Google Sheets File For Free ...
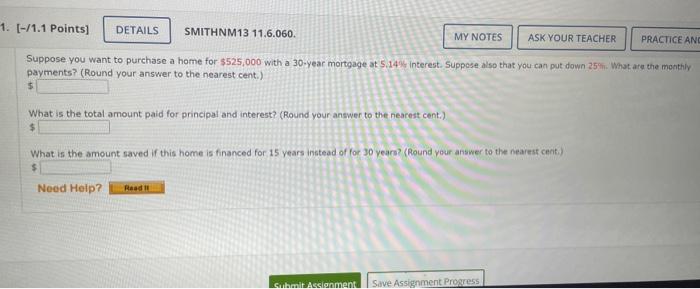
Solved Suppose you want to purchase a home for $525,000 with | Chegg.com