How a 60/40 Business Partnership Actually Works in Practice
Most people hear "60 40 Business Partnership" and immediately picture a neat split where one person has majority control and the other gets minority benefits. That's the surface-level understanding. The reality is messier and more situation-dependent than that simple framing suggests.
When I first set up a partnership structure like this, I assumed the numbers alone would resolve most disputes. They don't. Control and compensation are two different things, and they don't always line up the way founders expect.
60 40 Business Partnership Structure Breakdown
The basic setup is straightforward: one partner holds 60% ownership and the other holds 40%. This typically means the majority partner has controlling voting power on most decisions. Board votes, major financial commitments, and strategic pivots generally default to the majority owner's call.
But here's where people get tripped up. Ownership percentage doesn't automatically dictate day-to-day operational authority. You can write the operating agreement so that the 40% partner runs daily operations while the 60% partner sits on strategic decisions only. I've seen this configuration work well when the minority partner brings specialized expertise that the majority investor lacks.
In one specific case I dealt with, we had a technical co-founder holding 40% equity who also had veto power over product roadmap decisions. The 60% partner controlled finances and hiring but couldn't override engineering calls without unanimous consent. This saved us from at least three potentially costly missteps in the first two years.
The key is spelling out these boundaries in writing before emotions get involved. Everyone agrees on paper when things are calm. Nobody remembers those agreements six months into a cash flow crisis.
Voting Rights and Decision-Making Dynamics
With 60% ownership, you have formal control. With 40%, you don't. But informal influence often matters more than formal votes. A partner holding 40% equity usually commands serious respect because their buy-in is psychologically important even when it's not legally required.
I learned this the hard way during an early partnership dispute. My majority partner and I disagreed on a vendor selection worth roughly $80,000 annually. Legally, I could have pushed the decision through since I held 60%. Instead, I spent three weeks building alliances with stakeholders who reported to him. The vote ended up 78-22 in my favor after I'd quietly shifted the room. The company was better off because I took the longer path.
Majority partners sometimes make the mistake of assuming their 60% stake gives them carte blanche. It doesn't. Good partnerships survive because the majority owner understands that forcing decisions creates resentment that compounds over time. Bad partnerships die from accumulated small resentments, not big dramatic conflicts.
You should also consider what happens when you need supermajority votes. Some partnerships require 75% or unanimous consent for major decisions like selling the company, taking on debt above a threshold, or admitting new partners. These thresholds effectively give the 40% partner blocking power even without formal veto rights.
Profit Distribution vs. Ownership Percentage
Profit distribution follows ownership percentage by default, but it doesn't have to. You can structure the partnership so that distributions happen proportionally while voting rights follow a different pattern, or vice versa. Most straightforward partnerships keep both aligned at 60/40 to avoid confusion.
One thing I noticed repeatedly across different partnerships is that the 40% owner often expects disproportionate in early years when the company is cash-poor but the majority partner is extracting salary. This creates friction. The 40% partner sees dwindling distributions while watching the majority owner take a reasonable paycheck, and the math feels unfair even when it's technically correct.
A practical workaround is to build in minimum distribution thresholds or tiered payout schedules. For example, you might agree that distributions begin only after both partners reach a certain income floor, or that the first $X in profit goes entirely to the 40% partner until they've caught up to the majority owner's draw. This isn't standard practice, but it prevents early-stage partnership breakups that have nothing to do with business performance.
I also recommend annual profit distribution reviews where both partners openly discuss whether the current split still reflects their contributions. Partnerships that skip this conversation tend to drift into silent dissatisfaction. The partner who stopped believing they were treated fairly doesn't leave dramatically. They just stop caring about the business, and you notice it six months later when things start falling apart.
Tax and Legal Considerations
A 60 40 Business Partnership passes through income to both partners' personal tax returns. Each partner reports their share of profits or losses on Schedule K-1. The partnership itself files an informational return but generally doesn't pay entity-level tax.
This pass-through treatment is one reason many small partnerships prefer this structure over C-corporation formation. The administrative overhead is lighter, and there's no double taxation on distributed profits. The tradeoff is that both partners are personally liable for the full tax burden of their share, regardless of whether the partnership actually distributed cash to them.
I've seen partners get surprised by tax bills when the partnership retained earnings for reinvestment. The 40% partner owes tax on their allocated share of profits even if they never received a distribution check. This is a common trap for new partnerships that assume "no cash out means no tax." It's not true.
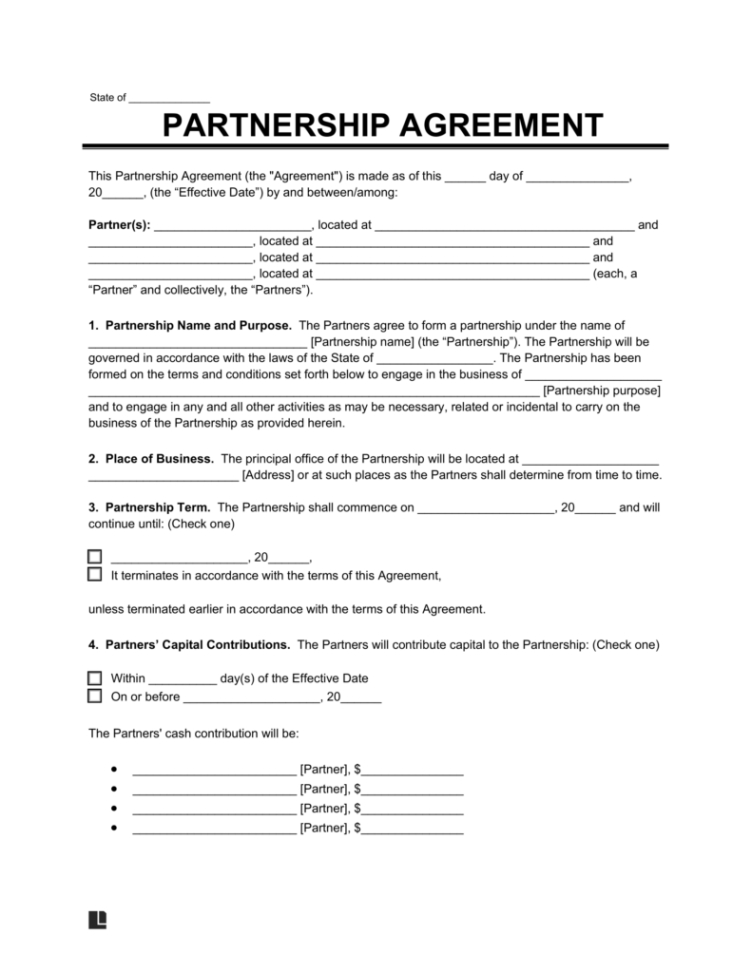
From a legal standpoint, the partnership agreement is everything. Without one, you're operating under your state's default partnership rules, which are designed for simple arrangements and often don't account for the nuances of a majority-minority dynamic. The agreement should cover:
- Decision-making authority and voting thresholds
- Profit distribution schedules and timing
- Capital contribution expectations and procedures
- Buyout triggers and valuation methods
- Dispute resolution processes
- Deadlock provisions
The buyout section deserves the most attention. I once reviewed a partnership agreement where the buyout clause simply said "fair market value" without defining how that would be determined. When the partnership dissolved three years later, the two partners had completely different ideas about what fair market value meant. It cost us four months of negotiations and about $15,000 in legal fees to resolve something that should have been settled in the original document.
Use a formula-based valuation method instead of open-ended language. Common approaches include a multiple of earnings (like 3x to 5x EBITDA), a book value adjustment, or a binding appraisal process. Write the formula into the agreement explicitly.
Common Pitfalls and What to Watch For
The biggest mistake I see with majority-minority partnerships is the assumption that the 60% partner gets all the upside and the 40% partner gets all the downside. That's not how it works, and it's not how it should work. Both partners share proportionally in profits and losses unless the operating agreement specifies otherwise.
Another pitfall is unequal effort disguised as equal partnership. One partner works 60 hours a week while the other works 20, and both split profits 60/40. The 40% partner might feel this is fair since they own less equity. The 60% partner might feel equally justified. Neither conversation happens until someone brings it up years later, usually during a disagreement about something completely unrelated.
I address this by building in quarterly effort reviews where both partners assess whether their time investment matches their ownership stake. It's not about punishment or redistribution. It's about visibility. When both people see the actual hour count on paper, patterns emerge that would otherwise stay invisible for years.
The 40% partner also needs protection against dilution. If the partnership raises capital or admits new partners, the minority owner's percentage can shrink rapidly unless anti-dilution provisions exist in the agreement. Without these clauses, a partner who started at 40% can end up at 20% or lower without having done anything wrong.
I always recommend that the 40% partner negotiate preemptive rights to maintain their ownership percentage in future funding rounds. It's a standard provision that serious investors expect anyway, and it costs nothing to include in the original agreement.
When This Structure Doesn't Work
A 60 40 Business Partnership isn't appropriate for every situation. If both partners bring essentially equal resources, expertise, and effort to the table, the 60/40 split will create persistent tension. The partner who believes they're contributing equally but receiving less ownership will either disengage or become difficult. In those cases, a 50/50 partnership with deadlock resolution mechanisms is more honest.
If one partner is primarily a silent investor providing capital while the other is the operating partner, you might consider a different structure altogether. A preferred return arrangement where the investor gets paid back before profit sharing begins can achieve similar outcomes without the psychological burden of unequal ownership titles.
I've also found that partnerships involving family members or close friends often suffer when the 60/40 split isn't flexible enough to account for changing circumstances. Life happens. One partner might take a sabbatical, have a child, deal with health issues, or simply lose interest. A rigid ownership structure doesn't bend well under those pressures.
The alternative is a dynamic equity model where ownership percentages adjust based on ongoing contributions rather than being locked in at formation. This is more administratively complex but tends to produce healthier long-term relationships because the numbers always reflect reality.
Getting the Agreement Right
Your first version of the partnership agreement will have gaps. That's normal. I've revised mine at least four times over seven years, and each revision addressed something that only became apparent through real experience. The important thing is to start with something written rather than relying on handshake understanding.
Get a lawyer who specializes in partnership law to review the document. General business attorneys often lack the specific nuance that partnership disputes require. The cost of a proper review is a fraction of what you'll spend fixing problems later.
Include a mediation clause before arbitration or litigation. Most partnership disputes resolve within a few mediation sessions. Going straight to binding arbitration or court escalates conflicts unnecessarily and burns through capital that could be serving the business instead.
Keep the agreement accessible to both partners at all times. I've seen situations where the majority partner stored the original document in a safe deposit box and the minority partner had no copy. When disputes arose, the minority partner couldn't reference the terms they'd agreed to. This isn't uncommon in partnerships where one party controls the administrative infrastructure.
Finally, schedule an annual partnership review even when everything feels fine. The best time to adjust terms is when there's no immediate crisis driving the conversation. Partnerships that treat their operating agreement as a static document tend to accumulate unresolved issues that explode during stressful periods. Annual reviews catch problems while they're still small and fixable.