Working with Economic Indicators for Your 63 Assignment
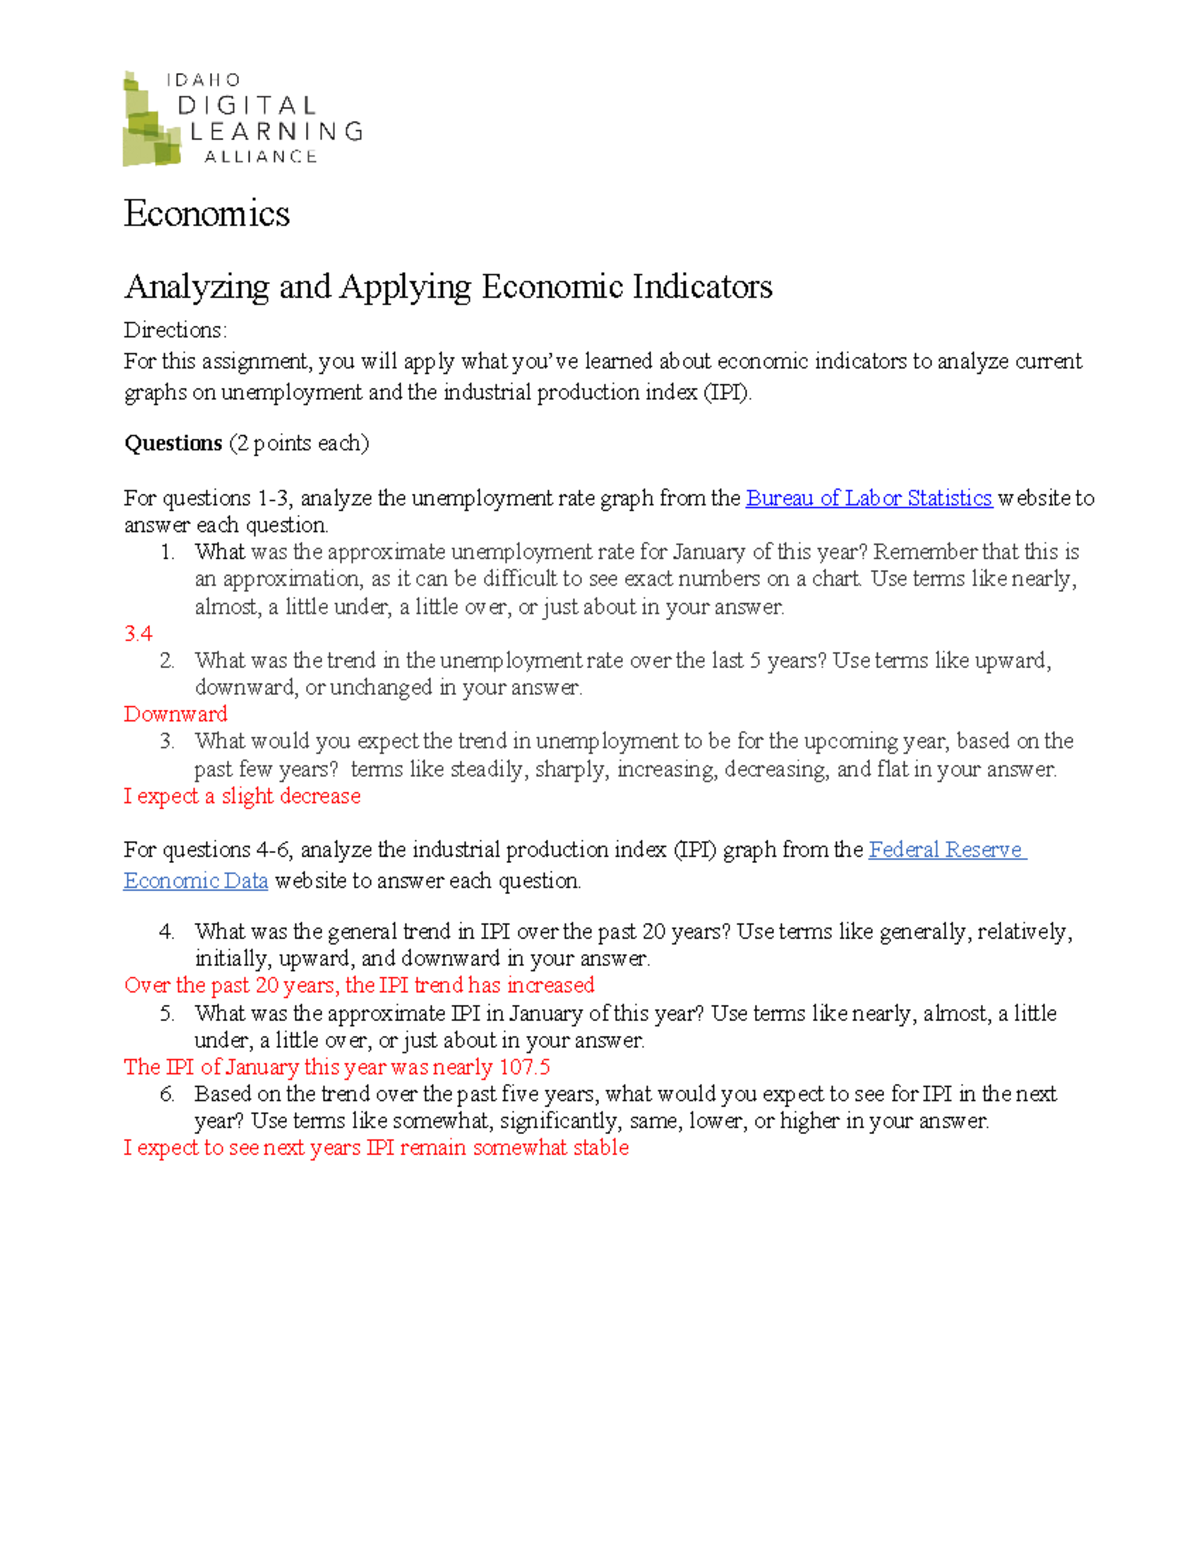
Economic indicators are data points that show the health of an economy. They come from government agencies, central banks, and private research firms. When you're putting together a 63 Assignment Economic Indicators project, the hardest part isn't finding the data — it's knowing which ones actually matter for your question and how to read them without misinterpreting the numbers. I worked on a project last semester that looked at how leading indicators could predict regional recession timing. The FRED database had everything I needed, but the problem was that GDP revisions kept shifting my conclusions three times before the paper was finalized. Seasonally adjusted data sounds reliable until you realize the adjustment factors get recalibrated every year, and your 2019 numbers from two years ago are not the same as what comes out now.
63 Assignment Economic Indicators: What You Actually Need to Know
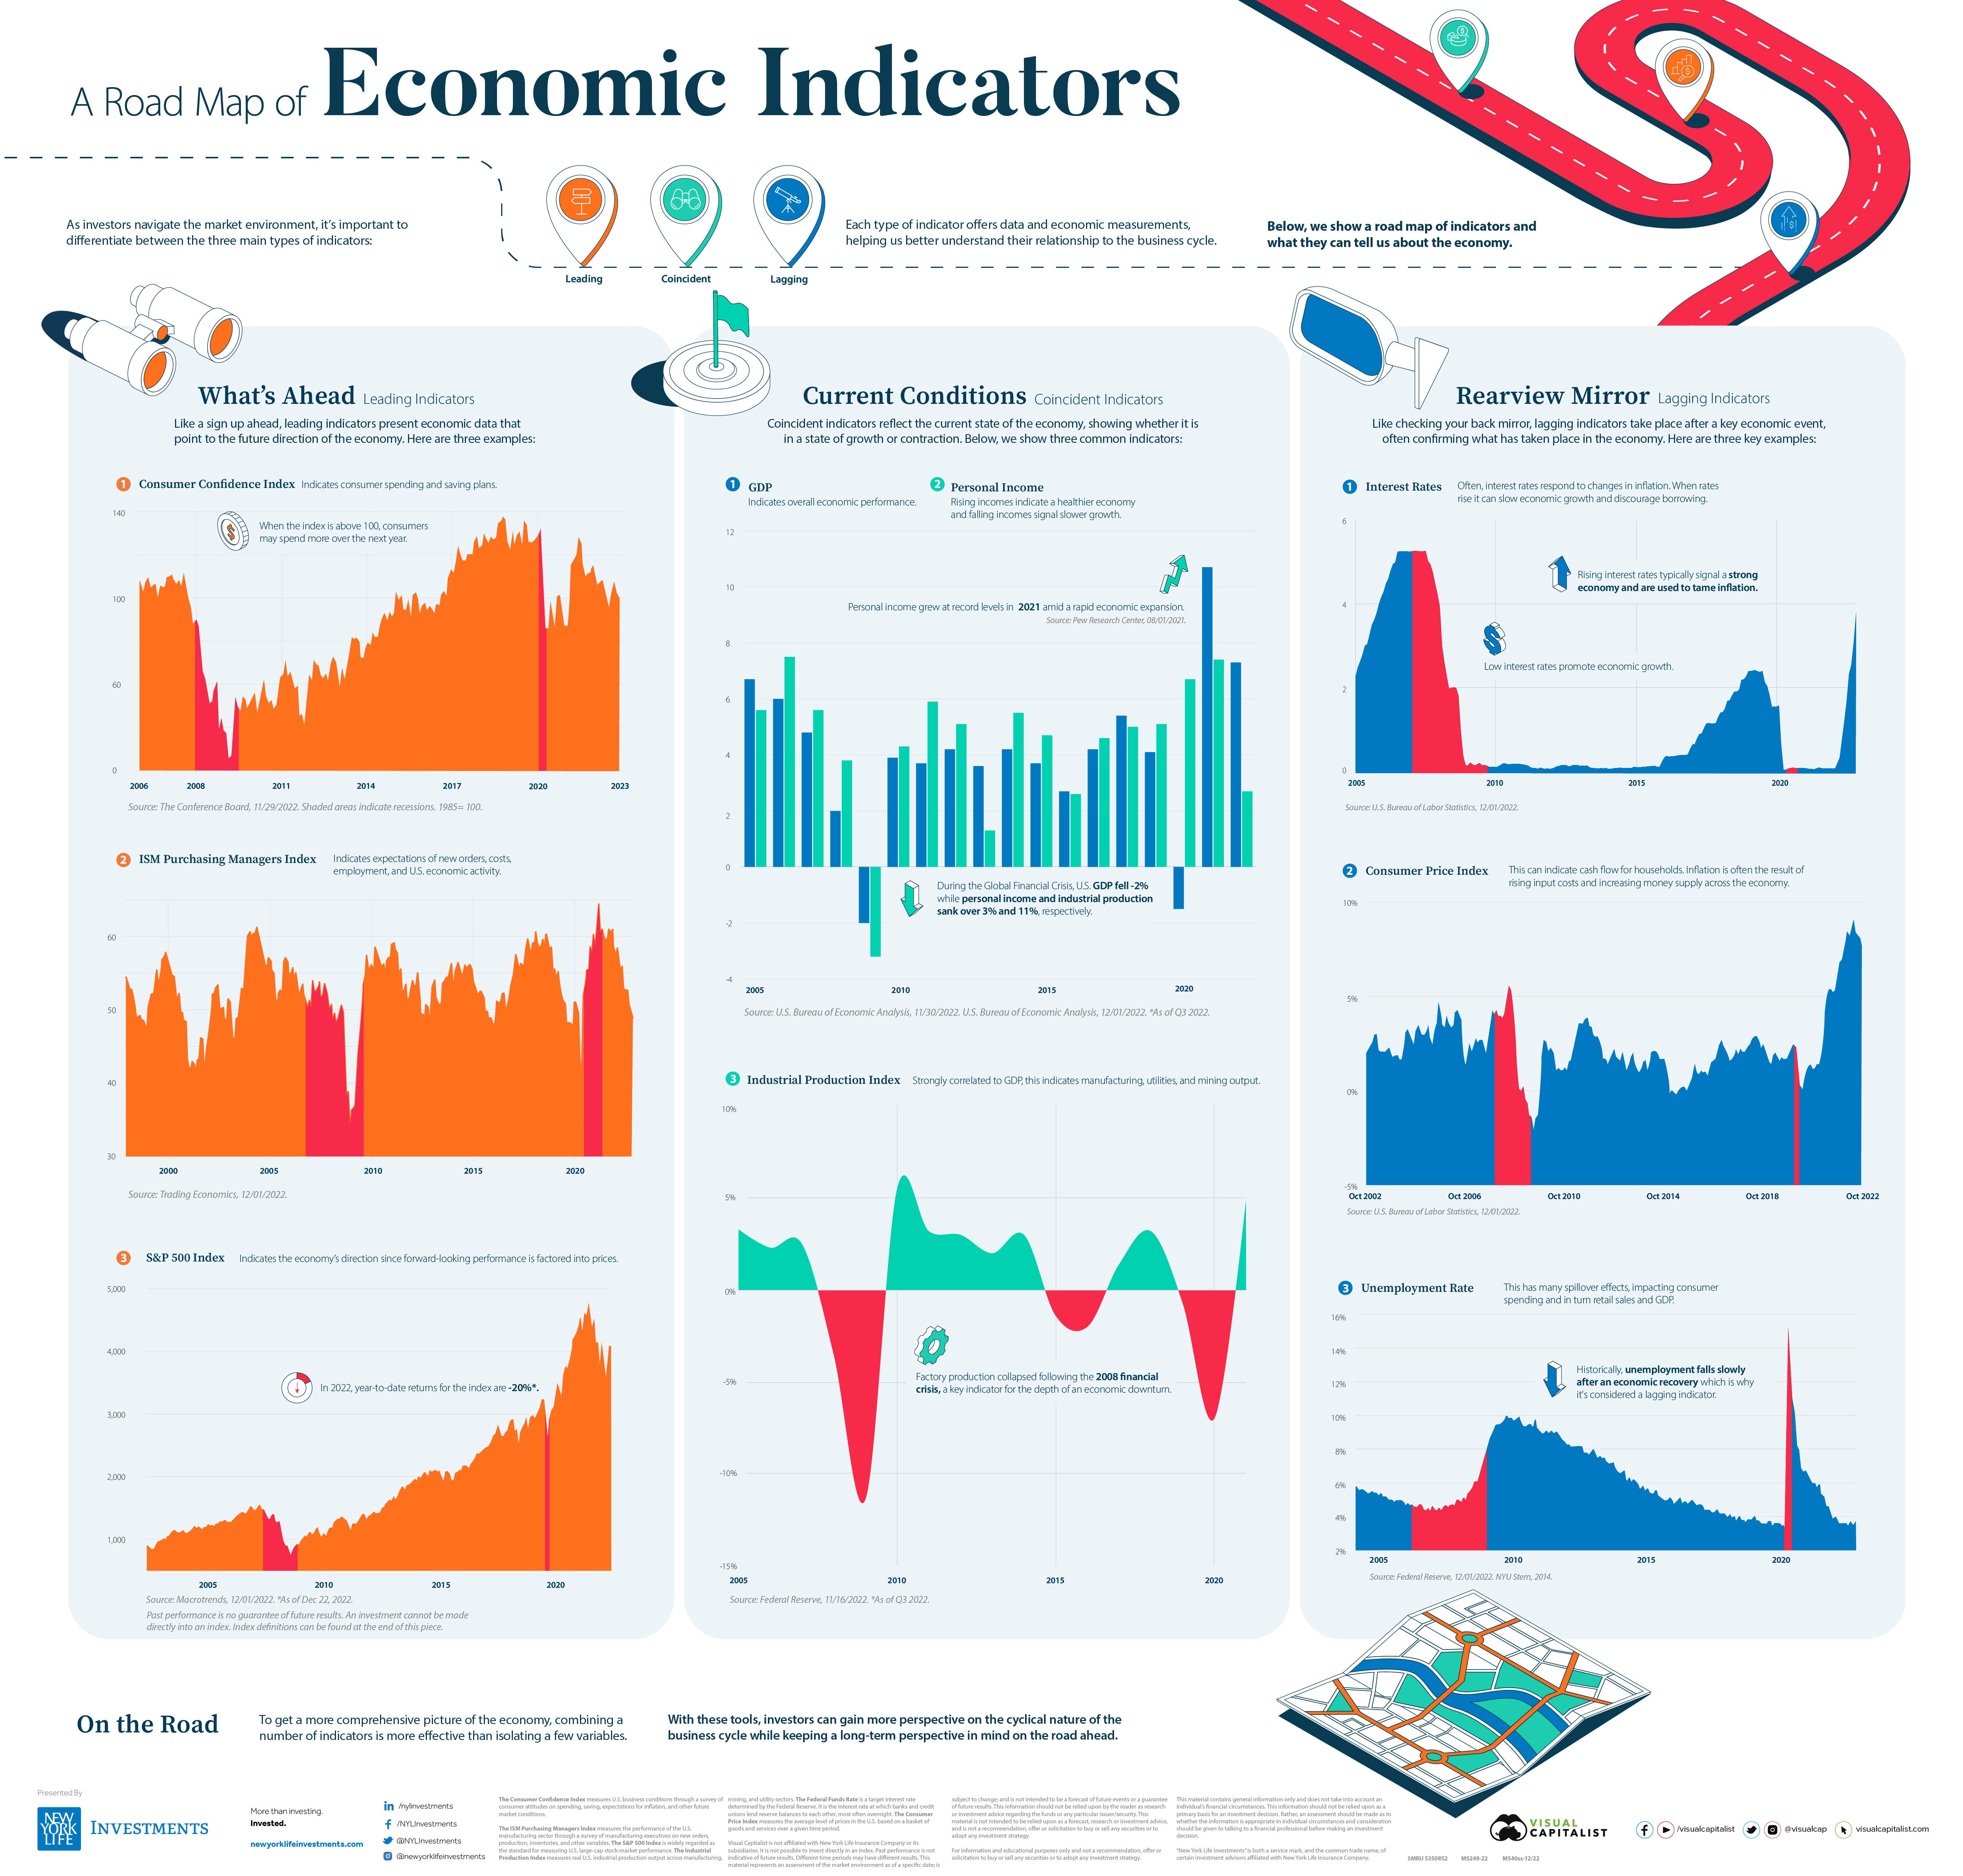
There are three categories you should understand: leading indicators, coincident indicators, and lagging indicators. Leading indicators change before the economy does. Things like the yield curve, building permits, and stock market performance fall here. Coincident indicators move with the economy right now — employment figures, industrial production, retail sales. Lagging indicators confirm what already happened, like unemployment rates and corporate profits. Most students treat all indicators equally. That is a mistake. If your assignment asks about current economic conditions, focusing on leading indicators will make your analysis look speculative. If it asks about forecasting, lagging indicators give you nothing useful. Match the indicator type to what the question is actually asking. The yield curve is one of the most discussed indicators and also one of the most misunderstood. A normal upward-sloping curve means longer-term rates are higher than short-term rates. An inverted curve — where short-term rates exceed long-term rates — has preceded every U.S. recession since 1970. But the signal is not instant. It typically inverts months before a recession and then the economy enters one somewhere between 12 and 24 months after inversion. Treating inversion as an immediate warning sign leads to bad recommendations.
Another thing people get wrong is how they use the Consumer Price Index. CPI measures changes in prices paid by urban consumers. It is not a perfect measure of inflation because it uses a fixed basket of goods, and that basket gets updated only every couple of years. When shelter costs spike, CPI reflects that quickly. When technology makes electronics cheaper, the effect shows up more slowly. During the 2021 to 2023 period, core CPI stayed elevated while asset prices told a different story. Reading just headline CPI would have given you an incomplete picture of what was happening. For your assignment, here is how I would approach the data gathering. Start with FRED, the Federal Reserve Economic Data database run by the St. Louis Fed. It is free, reliable, and lets you download series in CSV or Excel format. Pull at least two leading indicators, two coincident indicators, and one lagging indicator to give your analysis some balance. The Conference Board's Leading Index is a good single composite to include alongside individual series. I used to export data manually for every project, which took about forty minutes for a standard set of indicators. I switched to using the FRED API with a Python script, and the same job now takes about three minutes once the script is running. The catch is that the API has rate limits — six calls per minute for the free tier. If you are pulling fifty series in one go, you need to add delays between requests or batch your downloads. Writing the script initially took me about two hours, but it paid off by the third assignment.
Get the Full Details
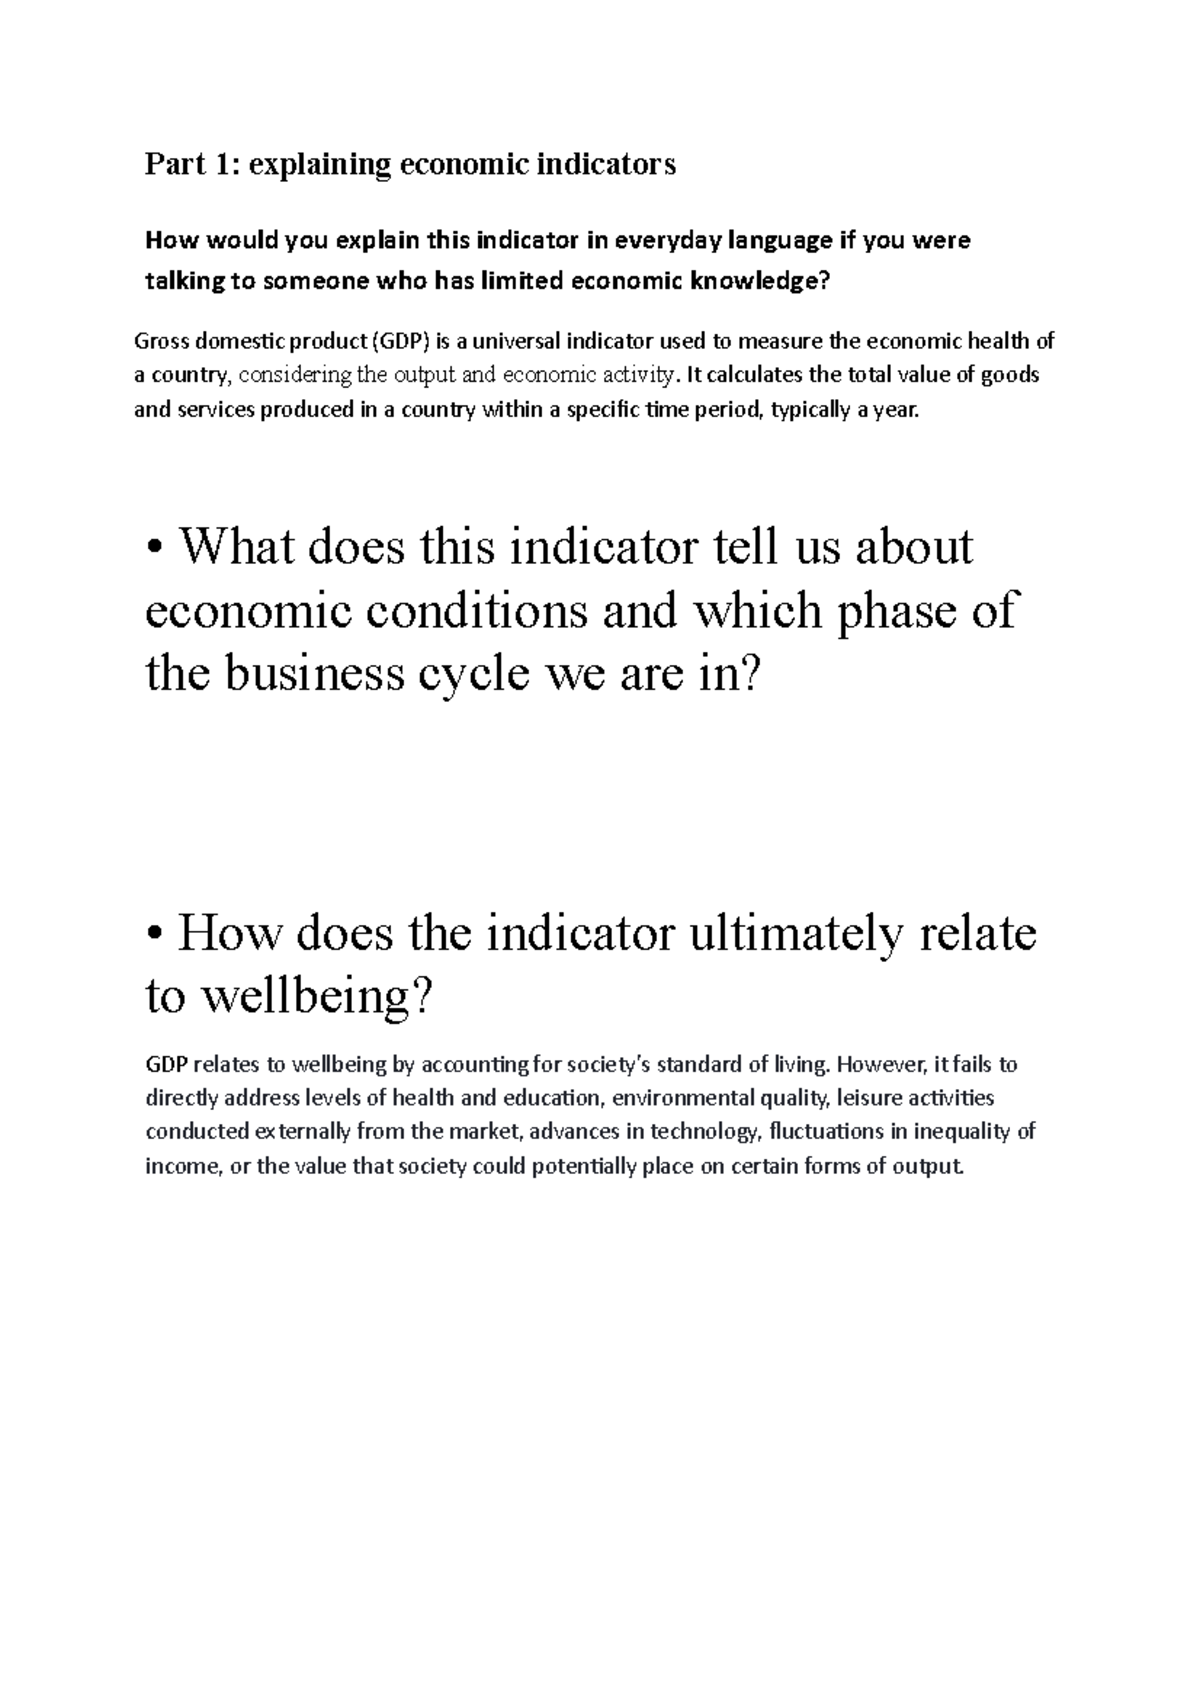
One edge case that cost me a grade once: I used non-seasonally adjusted data for a comparison across quarters without noting it. My professor marked me down because retail sales data with holiday spikes looks wildly different from the seasonally adjusted version, and the distortion made the trend line look erratic. Always specify whether your figures are SA or NSA, and use SA data for anything involving quarterly or monthly trend analysis. Another pitfall is confusing levels with growth rates. An indicator showing a level of 150 is not inherently better or worse than one at 50. You need to look at the percentage change or the first difference depending on the indicator. GDP at a level of 23 trillion does not tell you much on its own. The year-over-year growth rate of 2.4 percent is what tells you whether the economy is expanding or contracting. When interpreting the unemployment rate, remember that it understates labor market weakness because it does not include discouraged workers or people who have dropped out of the labor force entirely. The broader U-6 measure tracked by the Bureau of Labor Statistics includes those groups and was around 8.5 percent during the post-2020 recovery while the headline rate sat near 4 percent. Using only the headline figure gives an overly optimistic reading. Your assignment will look stronger if you acknowledge this gap.
Some indicators simply do not work well together. Mixing a high-frequency daily indicator like stock prices with a low-frequency quarterly indicator like GDP and then trying to correlate them statistically produces noisy results with little meaning. Stick to indicators at similar frequencies when doing correlation analysis, or aggregate the high-frequency data to match the lower frequency first. If your assignment allows it, include a chart or two. Visuals help readers see trends faster than tables of numbers. FRED's charting tools are decent for quick exports, but if you want something more polished, I used Google Sheets with the FRED data I downloaded. It took a bit longer to set up but gave me control over colors, labels, and axis formatting. A clean chart showing the yield curve inversion timeline alongside GDP growth rates makes a stronger argument than a paragraph describing the same relationship. The main limitation of relying on published economic indicators is that they are backward-looking or forward-looking at best, and even the best leading indicators have a false signal rate. The yield curve inversion has never produced a false positive for a U.S. recession, but it has occasionally predicted a recession that was shallow or did not materialize within the expected window. Indicator models break down in unusual circumstances — during the early pandemic months of 2020, most indicators collapsed simultaneously and then recovered in a V-shape that no model anticipated. Do not present indicator analysis as predictive science. Present it as informed observation with acknowledged uncertainty.
Download links for the data sources: FRED is at research.stlouisfed.org/fred, the Conference Board Leading Index is at theconferenceboard.org/data/leadingindicators, and BLS labor statistics are at bls.gov. All of these are free. No paid subscription is necessary for a standard assignment. The process usually takes me about an hour and a half from start to finish once I know which indicators to pull. The first time through a new topic, expect closer to two and a half hours because you will spend time deciding what to include and double-checking definitions. After that, the workflow tightens up significantly.