I spent six years doing cost modeling for a logistics company before I ever really understood why my spreadsheets looked right but the decisions they supported were consistently wrong. The gap wasn't in the math. It was in the framework underneath the numbers.
Economic thinking is one of those skills that sounds simple until you try to actually use it. The 7 Principles Of Economic Thinking give you a scaffold for that, but they don't automatically make you better at any of it. I learned that the hard way.
The 7 Principles Of Economic Thinking — What They Actually Mean In Practice
The first principle is opportunity cost. Everyone knows the definition. Few people apply it correctly because they calculate opportunity cost as if the alternative is free. It never is. When you allocate a resource, you are not just spending money. You are giving up whatever that resource could have produced in its next best use, and that value is rarely obvious from a spreadsheet.
The second principle deals with marginal analysis. This is where most business decisions fail. People optimize for the average instead of the margin. If your current unit costs ten dollars and your next one costs twelve, you don't raise prices on everything because of one expensive unit. You look at the twelfth dollar, not the average. I've seen companies throw away margin by making pricing decisions based on average cost curves instead of marginal cost data.
Trade creates value, and this is the third principle. Not just international trade. Any exchange where both sides expect to be better off. The principle explains why voluntary transactions happen, but it doesn't explain why some trades collapse even when both sides should benefit. Information asymmetry, transaction costs, and commitment problems can kill mutually beneficial exchanges before they start.
Incentives matter more than intentions. This fourth principle is the one people resist most because it conflicts with how we like to see ourselves. Good people make bad decisions when the incentive structure rewards the bad outcome. I worked with a supply chain manager once who genuinely believed he was minimizing costs while his bonus structure pushed him toward bulk purchasing that created inventory carrying costs three times higher than the savings he was chasing.
The fifth principle is about comparing alternatives, not absolutes. Nothing is good or bad in isolation. A warehouse is expensive somewhere and cheap somewhere else. The comparison has to be between two realistic options, not between your option and some imaginary frictionless alternative.
Prices send signals. This sixth principle connects everything back to markets. When you see a price change, you are looking at a compressed summary of supply conditions, demand conditions, and expected future states. Ignoring price signals because they feel unfair is like ignoring a thermometer because you think the temperature is wrong.
The seventh principle is about gains from trade and specialization. The more you specialize, the more productive you become, but specialization creates dependency. This is the tension that most beginners miss. Deep specialization wins until a shock hits and you realize you cannot pivot because everything you own is optimized for one outcome.
Where These Principles Break Down
I need to be honest about the limitations here. These seven principles work well in market contexts where prices exist and transactions are voluntary. They fall apart quickly in planned systems, in monopoly situations where the price signal is manufactured, and in cases where behavioral economics shows people systematically violating their own preferences.
There is also a time cost. Applying all seven principles rigorously to every decision takes significant cognitive effort. In practice, I found that using them on high-stakes decisions while letting low-stakes ones go unexamined gave me roughly 80 percent of the benefit with about 20 percent of the overhead. That tradeoff is worth making consciously instead of pretending you are applying all seven principles to everything.
Another blind spot is cultural variation. The incentive structures that drive behavior in one organizational culture produce completely different outcomes in another. The principles are universal, but their application is not. A bonus structure that optimizes for short term margin in one company will destroy long term value in another with different time horizons and risk tolerances.
A Real Problem I Faced With Opportunity Cost Modeling
Two years ago I was building a capacity planning model for a manufacturing plant. The straightforward approach would have been to calculate the opportunity cost of each production line based on current market prices. But the market prices didn't reflect the true alternative value because the plant had long term contracts that locked in below market rates for half its output.
The workaround was to build a dual pricing model. I calculated opportunity cost using market prices for the uncontracted portion and using contract-adjusted values for the committed portion. This gave me a more accurate picture of what each line was actually costing the company in forgone alternatives. The difference in the final recommendation was significant enough that the plant changed its expansion timeline by eight months based on the revised analysis.
This kind of adjustment comes up frequently. The 7 Principles Of Economic Thinking tell you to look at opportunity cost. They don't tell you what to do when the data you need to calculate opportunity cost accurately doesn't exist in a single source. You have to construct it yourself, and that construction process introduces its own errors.
How To Actually Use These Principles Without Wasting Time
Start with the decision at hand. Don't try to apply all seven principles to everything. Pick the one or two that are most likely to change your conclusion and focus there. Most decisions are not sensitive to all seven principles equally. Some are only sensitive to one.
Check for incentive misalignment first. This is the fastest way to identify where a decision might go wrong even if the numbers look good. If the person making the decision doesn't bear the consequences, the economic logic doesn't matter as much as the incentive structure does.
Use marginal analysis for scaling decisions. When you are deciding whether to expand, contract, or maintain, look at the margin. Average costs are useful for historical analysis. They are misleading for forward looking decisions about scale.
When you hit a situation where prices don't exist, construct proxy prices from comparable transactions. I have done this for internal transfer pricing, for allocating shared infrastructure costs, and for valuing non market assets. The proxies are never perfect, but they are usually better than treating the absence of a price as evidence that the price is zero.
Track your predictions against outcomes. This is the practice that separates people who use economic thinking from people who just repeat economic definitions. After you make a decision based on these principles, note what you expected to happen and compare it to what actually happened. The gap between prediction and outcome is where you learn. The learning is what improves your application of the principles over time.
The principles don't guarantee correct decisions. They reduce the probability of certain categories of error. That is a meaningful improvement, but it is not certainty. The best economic thinkers I know still make mistakes. They just make different mistakes than people who don't use the framework at all.
Gallery 7 Principles Of Economic Thinking
7 Economic Principles - 7 Principles of the Economic Way of Thinking Principle Summary ...
7 Principles of Economic Thinking by Sir Snyder's Shack of Scholarly Pursuits
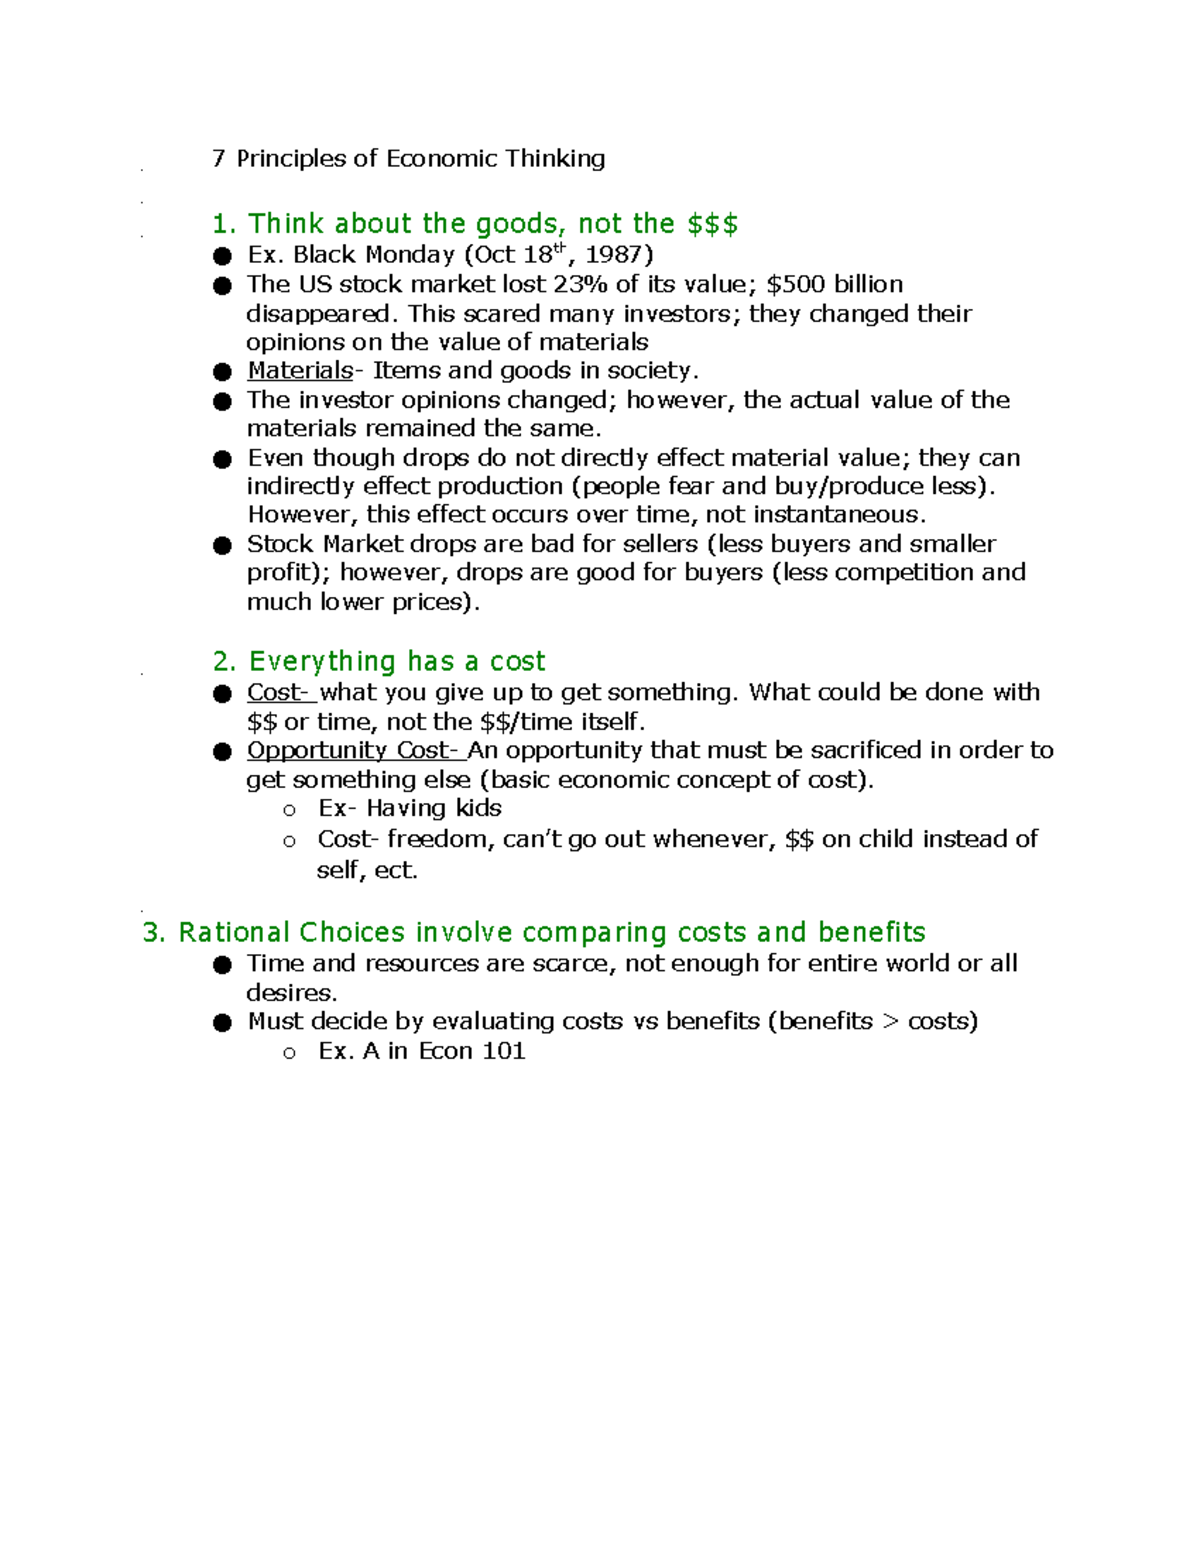
EC 101 Notes - 7 Principles of Economic Thinking 1. Think about the goods, not the $$$ Ex. - Studocu
PPT - The 7 Principles of Economic Thinking PowerPoint Presentation, free download - ID:2863744
7 Principles of Economic Thinking by Sir Snyder's Shack of Scholarly Pursuits