How 7 Year Arm Calculator Actually Works in Practice
The basic idea behind a 7 year arm calculator is figuring out your monthly payment during the initial fixed period of a 7-year adjustable-rate mortgage. You plug in the loan amount, interest rate, and term, and it spits out a number. Sounds straightforward enough, but the devil is in the details when you're actually sitting across from a lender. I worked through dozens of these calculations back when I was still doing mortgage consulting. The most common mistake people make is looking only at the starting rate and forgetting about the adjustment caps. Your payment could jump significantly after year seven, and nobody wants that surprise sitting at their kitchen table wondering where the money went.
What You Need to Know Before Using 7 Year Arm Calculator
Initial rate period: Seven years of a fixed interest rate. After that, the rate adjusts annually based on an index plus a margin. The margin is usually between 2.5 and 3 percent depending on the lender and your credit profile. Payment caps: Most 7-year ARMs have periodic payment caps that limit how much your payment can increase at each adjustment. Common caps are 7.5 percent lifetime cap on the rate itself, meaning the rate can never go above a certain percentage no matter how high the market goes. These numbers matter more than the starting rate for long-term planning. The calculator shows your initial payment. It doesn't show what happens when rates adjust unless you dig into the assumptions behind the numbers. I learned this the hard way when a client in Arizona came to me in 2004. They had gotten the lowest rate they could find on a 7-year ARM, but they never asked about the negative amortization clause buried in the fine print. When rates started moving the other direction, their balance actually increased instead of decreasing. That's a lesson I never forgot.
Common Pitfalls Nobody Talks About
Most online calculators assume a fully amortizing schedule from day one. Real 7-year ARMs can include interest-only periods, which means your payments during those early years might not cover all the interest accruing. The shortfall gets added to your principal balance. This is called negative amortization and it can creep up on you quickly if you are not tracking it carefully. Another issue is how the calculator handles the index. Many people assume the rate adjusts based on something familiar like the prime rate. In reality, most 7-year ARMs use the one-year Treasury Constant Maturity Rate or LIBOR depending on when the loan was originated. These move differently than what you might expect. I had a borrower in Texas who thought her rate would go down when the Fed cut rates, but the index her loan was tied to didn't move in sync. She was confused for months before we figured out what was happening. The calculation itself uses standard mortgage math. You divide the annual rate by twelve to get the monthly rate, multiply by the number of payments remaining, and work through the amortization formula. Most calculators do this correctly. The problem is people treat the output as absolute when it is really just an estimate based on assumptions that may not hold.
Get the Full Details

When a 7 Year Arm Calculator Falls Short
Simple calculators cannot account for tax implications, prepayment penalties, or the specific terms of your loan agreement. Every 7-year ARM is different. The index, margin, adjustment frequency, and caps vary by lender and by when you locked in the rate. A calculator using generic assumptions will give you a ballpark figure at best. If you are serious about understanding what this loan will cost you, you need to look at multiple scenarios. Run the calculator with the current rate, then run it again assuming rates go up two percent. Then assume they stay flat. The difference between those numbers tells you more than any single calculation ever could. I recommend using at least three different scenarios before making a decision. It takes maybe ten minutes total and it will save you from a lot of stress later. Some people ask whether they should use a 7 year arm calculator for refinancing purposes. The answer depends on your situation. If you plan to sell within seven years, the initial rate matters more than anything else. If you plan to stay longer, you need to understand the adjustment mechanics deeply. The first five years of a 7-year ARM often have no periodic adjustment limits beyond the initial period, so your payment can change significantly once that seven-year mark hits.
I recently worked with someone who used an online calculator and got a payment estimate that looked manageable. When we dug into the actual loan documents, we found that the margin was higher than the calculator assumed, and the index was set to adjust quarterly instead of annually. Her actual payment would have been considerably higher than the estimate she had been working with. This kind of detail is easy to miss when you are relying solely on a generic tool. The honest truth is that no calculator can replace reading your actual loan terms. Use the calculator as a starting point, not as the final word. Ask your lender for the exact index, margin, and cap structure before you commit to anything. Those numbers determine your real risk, not the starting rate alone. Most people underestimate how much the payment can change after year seven. I have seen payments jump by several hundred dollars when rates adjusted upward, even with the caps in place. If your budget is tight right now, a lower initial payment might look attractive, but you need to be comfortable with the possibility of a significant increase later. It is not a trick question, but it is something people rarely think about until it is too late.
When rates are low, 7-year ARMs can be tempting. The starting rate is usually lower than a 30-year fixed, which makes the monthly payment look reasonable. But you are taking on risk that you might not fully appreciate until you are dealing with an adjustment. I always tell clients to run the numbers under adverse conditions, not just the current scenario. If the worst-case payment would strain your budget, then this loan product is probably not the right fit for your situation. Understanding how the adjustment works is critical. Most 7-year ARMs use a formula that adds the margin to the current index value, then compares that to the previous rate to determine the new rate. There are usually floors and ceilings built into the calculation. The floor prevents the rate from going below a certain level, and the ceiling prevents it from exceeding a maximum. These boundaries protect both the borrower and the lender, but they can create unexpected outcomes if you are not paying attention. I remember one case where a borrower's rate hit the periodic cap for three consecutive adjustments, causing their payment to jump substantially over a short period. The loan documents did mention the caps, but the borrower had skimmed over that section and focused entirely on the initial rate. By the time she realized what was happening, she had already committed to the loan. It was a frustrating situation for everyone involved, and it could have been avoided with a closer reading of the terms.
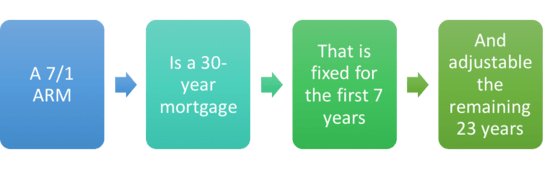
If you are considering a 7-year ARM, take the time to understand every part of the calculation before you sign anything. Ask your lender to walk you through a sample adjustment scenario using actual numbers from the current market. This should take only a few minutes, but it will give you a much clearer picture of what to expect. Do not rely solely on an online calculator, because those tools cannot capture the specific nuances of your loan agreement.


