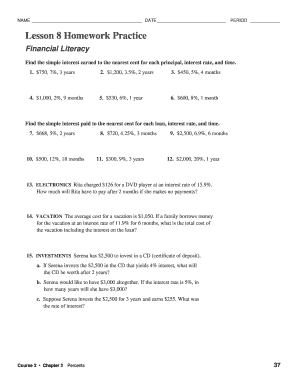
What 8 Homework Practice Financial Literacy Actually Looks Like
The name sounds like a curriculum guide from a school district meeting nobody attended, but the concept behind 8 Homework Practice Financial Literacy is practical enough. It's a set of structured assignments designed to walk students through core money management topics over an eight-part sequence. The framework typically covers budgeting, saving, understanding interest rates, credit basics, debt management, insurance fundamentals, investing introduction, and financial goal setting. I've reviewed enough of these programs across middle school and high school levels to know what works and what ends up sitting in a drawer. The key difference between a program that actually changes student behavior and one that gets completed and forgotten comes down to how realistic the scenarios are.
Getting Started With 8 Homework Practice Financial Literacy
The most common mistake I see is treating the assignments as academic exercises rather than simulation tools. Students will plug numbers into formulas and move on without really processing what those numbers mean in a real-world context. The work only becomes useful when the student is forced to make decisions with constrained resources. Here is how the typical eight-module sequence breaks down in practice: Module 1: Budgeting basics. Students receive a fictional income scenario and must allocate dollars across fixed expenses, variable costs, and savings. This seems straightforward until you introduce an unexpected expense in Module 4 and watch how many students have zero buffer built in. That friction point is where the actual learning happens.
Module 2: Compound interest and savings. The math here matters, but the lesson that lands is the time component. I had a student who calculated that saving two hundred dollars a month at seven percent would reach a certain number by age thirty. When she recalculated starting at age forty instead of twenty-five, the difference was so large she actually paused and said something different out loud. That moment is what the assignment is supposed to create. Module 3: Credit scores and reports. This section tends to drag because the data feels abstract. Students don't carry credit reports yet. The workaround I found was to have them research their own local credit union's membership requirements and minimum opening deposit, then compare that to a big bank's offers. The numbers become real when they're looking at products they could actually use within a year. Module 4: Debt and minimum payments. This is where most programs lose students because the calculations get heavy. A common pitfall is showing the total interest paid on a minimum-payment-only approach and expecting students to feel motivated. The more effective approach is having them model two repayment scenarios side by side and track the difference in months required to clear the balance. The emotional weight comes from seeing eighteen months turn into five years on a single credit card.
Get the Full Details

Module 5: Insurance fundamentals. Most students skip this section because it feels like adults talking about adult problems. The practical hook is auto insurance, since anyone planning to drive needs it. Have them compare quotes from two real insurers using a sample profile. The premium differences between coverage levels often surprise them, and the deductible tradeoff becomes tangible rather than theoretical. Module 6: Introduction to investing. The danger here is oversimplifying. Don't present the stock market as something you just do. Show the difference between a index fund and an individual stock pick, explain expense ratios, and mention that most people who try to time the market underperform a simple buy-and-hold strategy over ten years. Keep it honest. Module 7: Financial goals and planning. This is where everything connects. Students take their budget from Module 1, factor in debt from Module 4, add savings targets informed by Module 2, and build a three-year plan. The exercise falls apart if the earlier modules were done carelessly, which is intentional. The plan should reflect the actual constraints the student discovered earlier.
Module 8: Review and application. The final module should ask students to audit a complete financial profile, identify the weakest link, and propose changes. A strong submission here shows the student can connect all eight topics rather than treating them as isolated quizzes.
Where These Programs Fall Apart
I've watched schools adopt 8 Homework Practice Financial Literacy materials and then abandon them halfway through because the assignments don't account for students who already work part-time or manage household budgets. The fictional income scenarios assume a baseline experience most teenagers haven't had. The program still has value, but the teacher or facilitator needs to offer alternatives that let working students analyze their actual pay stubs and spending patterns instead of a generic example. Another hard limitation: these materials rarely address digital financial tools. A student finishing an eight-module program on paper budgeting will struggle the moment they try to use a spreadsheet or a budgeting app. The gap between the homework and real tools is significant. I solved this in my own sessions by having students replicate one assignment in Google Sheets or a free budgeting tool after completing the paper version. The time investment doubled, but retention improved noticeably because the skill transferred to something they could actually use. Credit literacy deserves more attention than most programs give it. Students walk away understanding that late payments hurt scores, but few grasp how credit utilization ratio actually works in practice. I once had a student who thought paying off the full balance every month was sufficient and didn't realize that carrying a small balance relative to the limit mattered too. We pulled a sample credit report, looked at the utilization numbers, and recalculated what different spending patterns would show. It took twenty minutes and fixed a misconception that a typical four-page worksheet never touches.

The biggest bottleneck with this type of curriculum is time allocation. Eight modules sounds manageable until you factor in that realistic financial literacy homework requires reflection, not just calculation. Students need space to question assumptions and adjust scenarios. Rushed through in two-week sprints, the program delivers surface-level awareness. Spread across a semester with periodic check-ins, the same material produces substantially better outcomes. There is no way around that tradeoff. If you are looking for the actual 8 Homework Practice Financial Literacy assignments, they are typically distributed through school districts or published educational platforms rather than as standalone public downloads. Check with your curriculum coordinator or the education publisher's resource page. Some third-party sites host adapted versions, but those often omit the solution walkthroughs that make the exercises actually teachable. An incomplete answer key turns a structured assignment into a guessing game, and students learn the wrong habits doing that. The bottom line is that 8 Homework Practice Financial Literacy is a framework, not a cure. It gives structure to a subject that otherwise gets zero attention in standard curricula. The assignments work best when an instructor pushes past the numerical answers and forces students to sit with the implications. That push doesn't happen automatically, which is why programs that include facilitator notes and discussion prompts tend to outperform the bare-bones worksheets by a wide margin.


