How Short-Term Financial Policies Actually Work in Practice
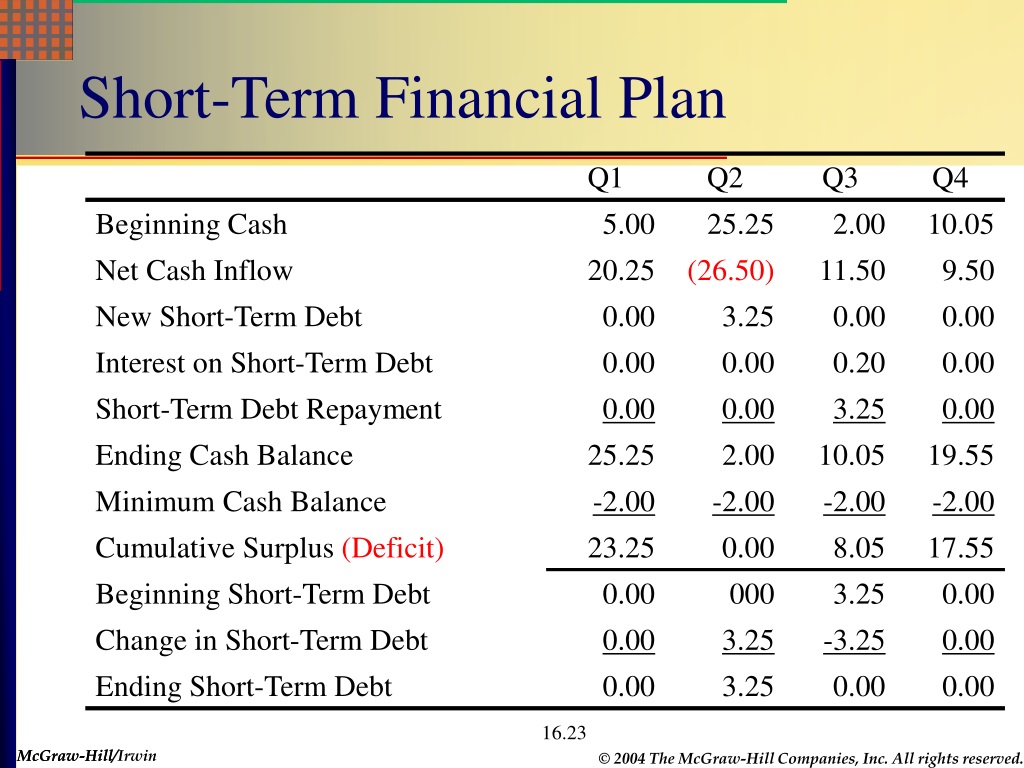
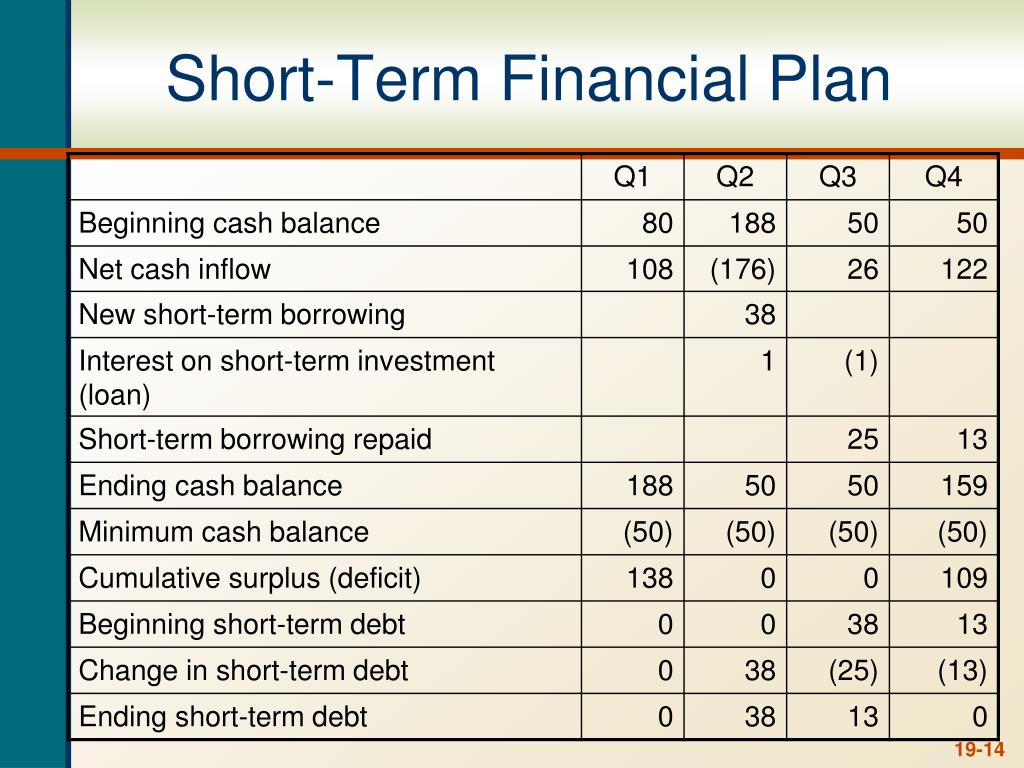
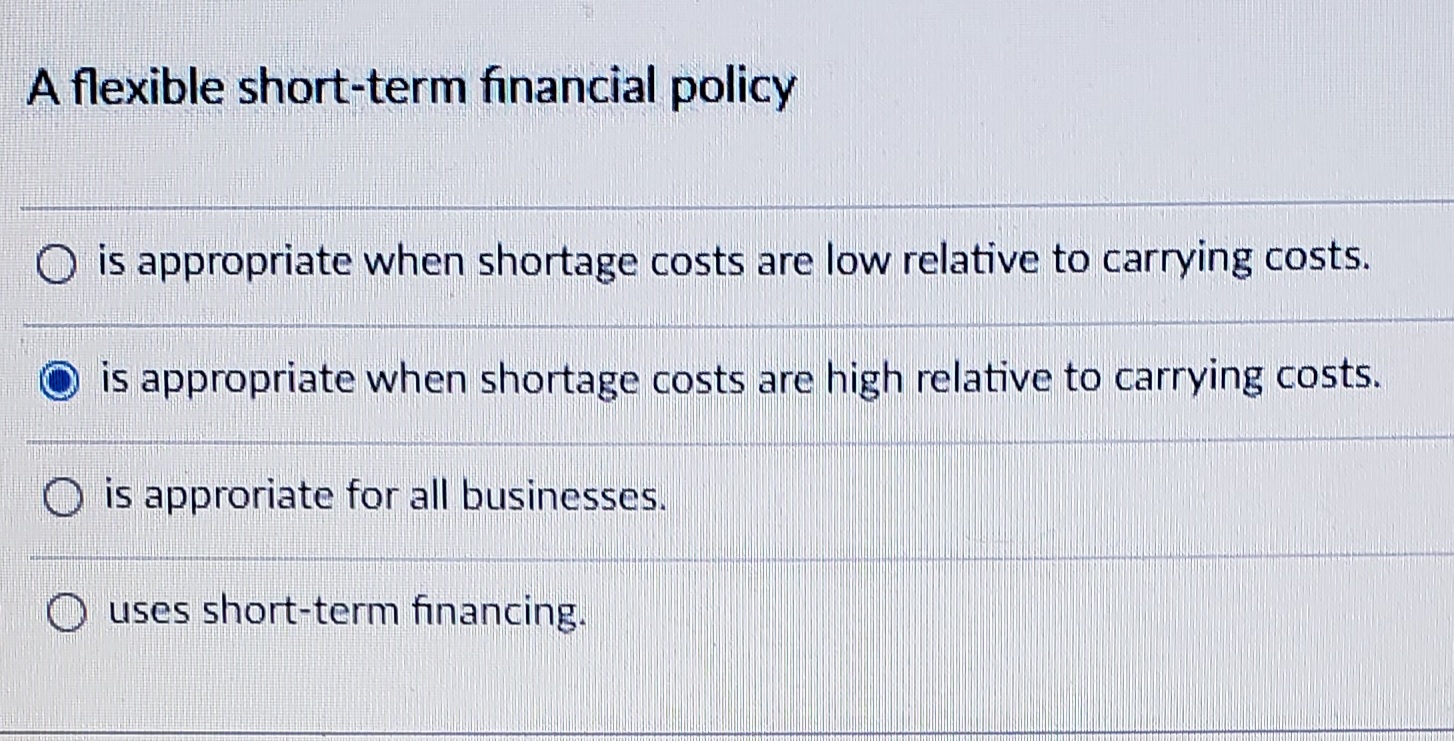
Most companies treat short-term financial policy like it is something you write once and frame. That approach breaks within six months. The reality is that your working capital cycle, cash conversion period, and receivable collection habits shift with seasonality, vendor renegotiations, and the occasional surprise from accounts payable. You need a system that can bend without snapping. I spent years fixing the mess that comes from treating liquidity management as a static spreadsheet. At its core, this is a structured approach to managing current assets and current liabilities where the thresholds, targets, and backup liquidity options adjust based on real operating conditions rather than arbitrary quarterly budgets. You set minimum targets for the current ratio and quick ratio, but you also build in triggers that tell you when to tighten or loosen credit terms, when to draw on a line of credit, and when to accelerate collections. The flexible part is the decision framework, not the willingness to move money around whenever something looks tight. I usually start by mapping the cash conversion cycle for the business. Days inventory outstanding, days sales outstanding, and days payable outstanding form the backbone. When those three numbers move together you have a stable operation. When they diverge, you have a signal. For example, if DSO creeps up while DPO stays flat, someone is letting invoices sit unpaid internally or customers are extending their own payment cycles. That is the point where most flexible policies activate their first response: adjust credit terms or start early payment discounts before the next quarter close.
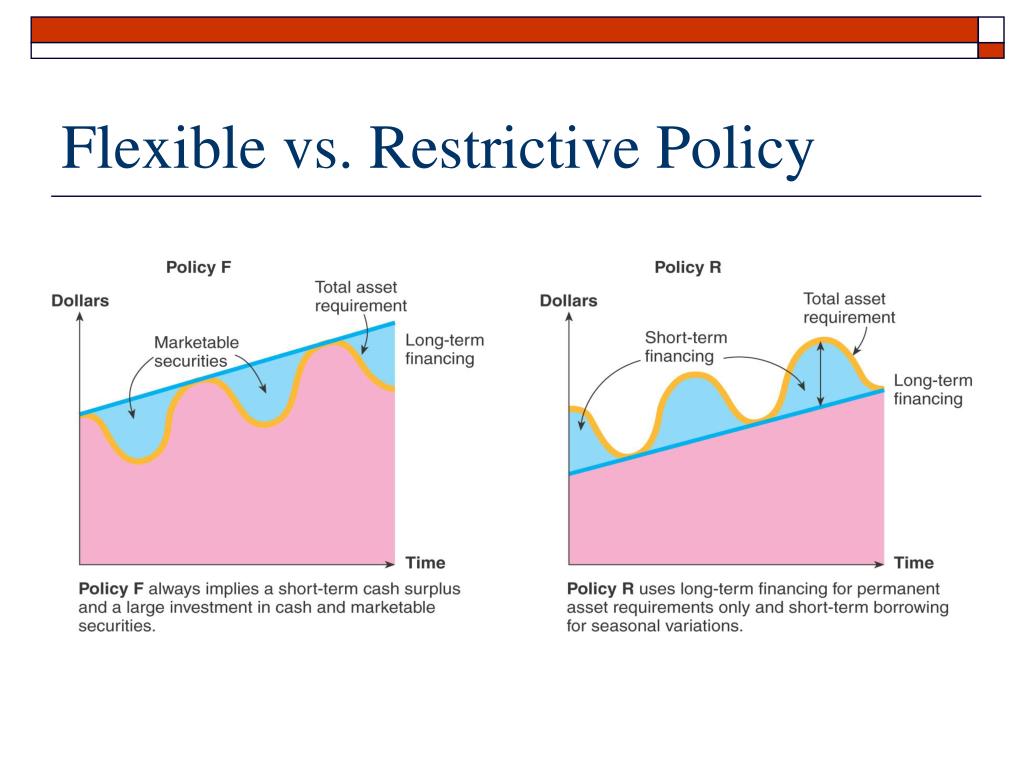
Here is the practical side: build a monthly dashboard that tracks three rolling windows. A thirty-day window for immediate actions like chasing overdue invoices or tapping your credit line. A sixty-day window for medium adjustments like renegotiating supplier payment terms or adjusting inventory reorder points. A ninety-day window for structural moves like refinancing short-term debt or altering your customer payment policy. The numbers on the dashboard tell you which window to act in. If your current ratio drops below one point two for two consecutive months, the sixty-day window activates. If it drops below one point zero, you go straight to the ninety-day window and start looking at long-term alternatives. One edge case that still catches people off guard involves seasonal revenue recognition versus actual cash collection. I worked with a client whose revenue spiked in November and December due to holiday demand, but their customers were on net sixty terms. The financial statements looked healthy through Q4. Cash flow was negative from October through February. Their bank line was maxed out because they had been borrowing to cover payroll and inventory every month, assuming the year-end revenue would cover it. It did not, because the revenue was booked but the cash was still in transit. The workaround was switching their top five customers to net thirty terms with a two percent discount for early payment, which brought in about four hundred thousand dollars in cash three weeks earlier than expected. That single change prevented a breach of their credit covenant. It also meant I had to sit down with the sales team and explain why discounting was cheaper than penalty interest on a blown line of credit. Salespeople do not always see the math until you show them the actual cost of the alternative. Another counter-intuitive point that beginners miss is that maintaining a higher cash balance is not always the safer move. There is a trade-off between profitability and liquidity that most people handle poorly. Keeping excess cash sitting in a low-interest account destroys returns. But running too lean means you are one delayed shipment away from a crisis. The flexible policy approach finds the middle by using dynamic targets rather than a fixed number. Your target cash balance should scale with your average monthly burn rate and your shortest possible receivable cycle. If your burn is two hundred thousand per month and your fastest collections take twenty days, your minimum liquid buffer should be around one hundred and thirty-three thousand. Anything below that is risk. Anything far above that is idle capital that could be working elsewhere.
The implementation details matter more than the concept. Start with your current ratio and quick ratio targets. Most textbooks say keep the current ratio above two and the quick ratio above one. That is outdated advice for modern businesses with reliable receivables and just-in-time inventory. A current ratio between one point four and one point eight is usually sufficient if your DSO is under forty-five days. If your DSO is over sixty days, push the target higher to around two point zero because your liquidity is tied up in uncollected invoices. The quick ratio works similarly but strips out inventory. If your inventory is easily liquidated at close to book value, the quick ratio target can be lower. If your inventory is specialized or seasonal, treat it like it might not sell and keep the quick ratio target conservative. You also need a set of triggers for using short-term borrowing. The common mistake is borrowing only when you are already short. The flexible approach has you drawing on your credit line proactively when the indicators suggest a gap will form in the next thirty to sixty days. This means you negotiate the terms upfront with your bank, including commitment fees and interest rate structures, so that when you do draw, it does not come as a surprise to anyone. I had a situation where a client drew on their line late because they were waiting to see if a large customer would pay on time. The customer paid two days late. The late fee on the line and the penalty interest cost them more than the discount they would have gotten for paying early. The lesson was simple and expensive to learn: borrow on the signal, not on the crisis.
Common Pitfalls and Where This Approach Breaks Down
Get the Full Details
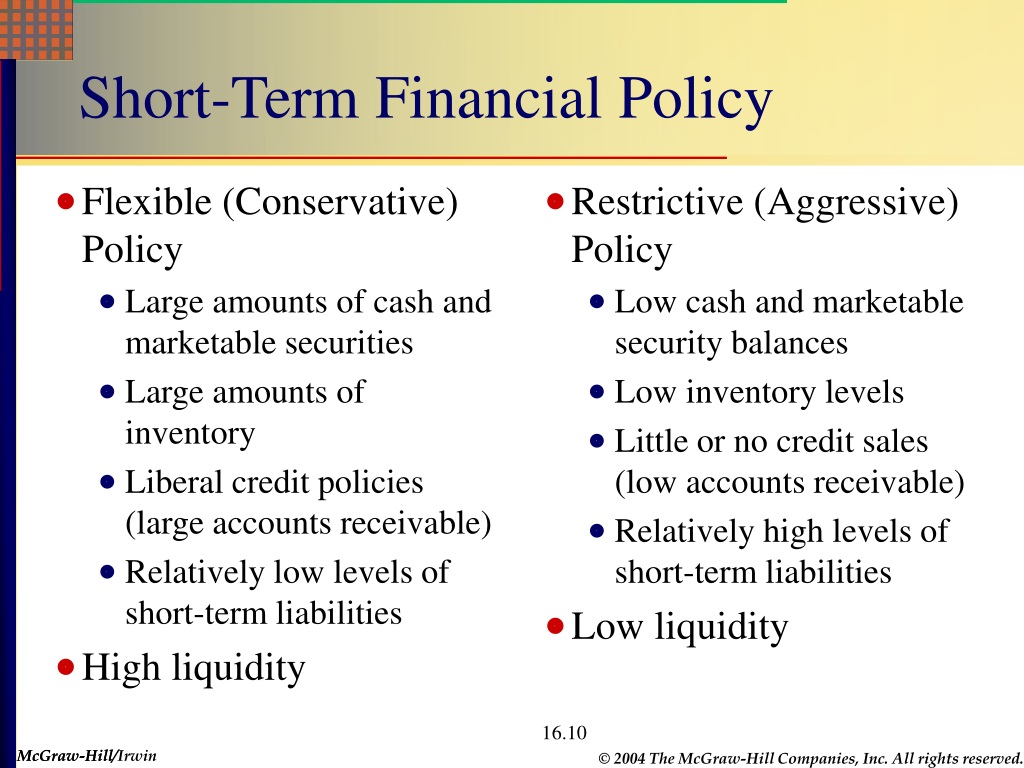
Even a well-designed flexible short term financial policy has limitations. The biggest one is data quality. If your accounts receivable aging report is inaccurate or your inventory counts are stale, every trigger and threshold in your system is pointing at the wrong thing. I have seen companies spend weeks tuning their models only to discover the underlying data was wrong. Fix the data first. Then fix the model. Building a flexible policy on garbage input just gives you a faster way to make bad decisions. Another limitation is that this approach assumes you have access to short-term credit. If your business is in an industry where banks will not extend a line, or if your credit history is poor, the flexibility options shrink dramatically. In those cases, the policy becomes more about managing what you can control internally: faster collections, slower payables where relationships allow it, and inventory optimization. You can still build the trigger system, but your response toolbox is smaller. Invoice factoring becomes an option in some cases, though the cost is significant. A typical factoring advance runs around eighty to eighty-five percent of the invoice value with fees that can add up to two to five percent depending on volume and creditworthiness of your customers. That is expensive liquidity, so it should be a last resort, not a regular part of your policy. There is also a human factor that nobody talks about enough. A flexible policy requires someone to actually monitor it and take action when triggers fire. If you build a sophisticated system but the person responsible for acting on the alerts is overwhelmed, on vacation, or simply ignores the dashboard, the system is useless. I recommend assigning clear ownership for each trigger level. The person who sees the thirty-day window activation should be the one who makes the call, not the CFO who gets a weekly summary. Speed matters in short-term liquidity management. Delays of even a week can turn a manageable gap into a covenant breach.
The policy also does not help when the problem is structural rather than cyclical. If a company's business model inherently requires more working capital than it generates, no amount of flexible policy design will fix that. You need either higher margins, faster turnover, or different customer terms. The policy can buy you time, but it cannot change the underlying economics. I encountered a case where a manufacturing firm kept running short on cash despite having a perfectly tuned flexible policy. The root cause was that they were pricing their products based on cost plus a thin margin while their competitors were pricing based on value. The cash flow gap was structural. The flexible policy helped them survive quarter to quarter, but the real fix came from a pricing overhaul that took eighteen months to implement. The policy kept them alive during that transition. It did not replace the need for the transition.
Building the System Without Overcomplicating It
Start with the three metrics that matter most: cash conversion cycle, current ratio, and quick ratio. Track them monthly for at least six months to establish a baseline. Once you have the baseline, set your trigger thresholds based on historical patterns rather than textbook ideals. If your current ratio has naturally hovered around one point six for the past year, setting a trigger at one point four makes sense. Setting it at one point zero would be reactive instead of proactive. The goal is to catch problems before they become problems, not to react after the damage is done.Next, define your response options for each trigger level. Write them down. Make them specific. Not "consider borrowing" but "draw twenty percent of available credit line if current ratio falls below one point four for two consecutive months." Specificity reduces decision latency when pressure is on. Under stress, people default to the options they have already rehearsed. If you have not written the options down, you will waste time deliberating when you should be acting. Finally, review and adjust the policy quarterly. Business conditions change. Seasonality shifts. Customer payment behavior evolves. A policy that worked last year may not work this year. The flexible part of a flexible short term financial policy is not just about day-to-day adjustments. It is also about periodic revision of the triggers and responses themselves. I review mine every January and July, aligning with most fiscal year planning cycles. The review takes about an hour if the data is clean. If the data is messy, it takes longer, which is why I emphasized data quality earlier. The whole process is unglamorous. There is no clever trick or secret formula. It is mostly about knowing your numbers, setting reasonable thresholds, and having the discipline to act when the signals appear. Most companies fail at the discipline part, not the math part. The math is straightforward. The discipline is the hard part.