Interest Calculation Is Where Most People Lose Money
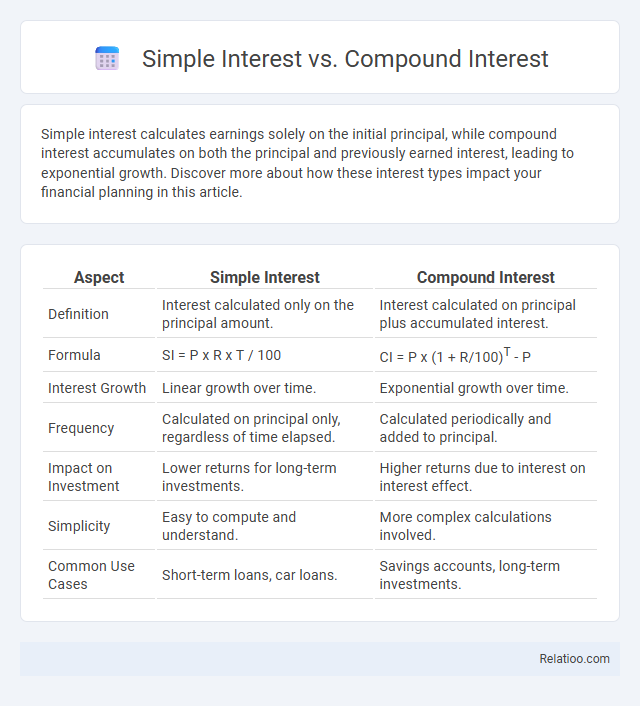
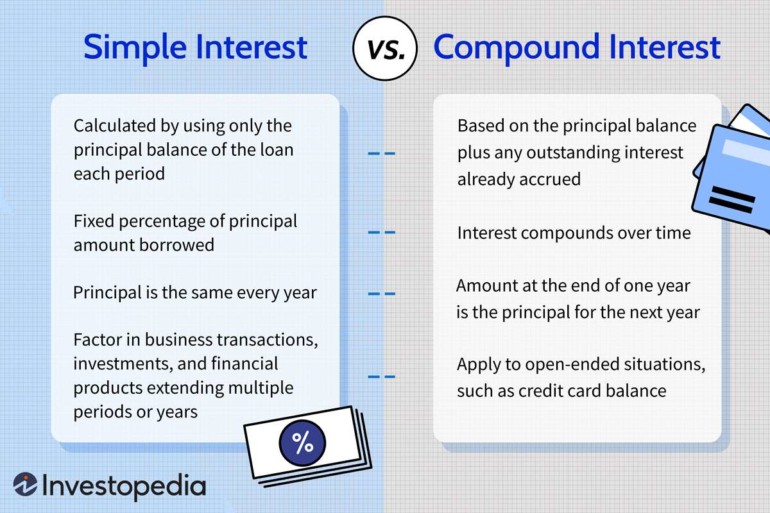
I spent years working in banking operations before moving to fintech consulting, and the single most common source of client complaints isn't fraud or hidden fees. It's simple versus compound interest confusion. People do not read the fine print because they genuinely believe the two work the same way. They do not. Simple interest charges only on the principal amount. You borrow $10,000 at 5% simple interest per year for 3 years. Your total interest is $1,500. That is it. No surprises, no compounding, no sneaky additions to the base. The calculation is linear and predictable. Compound interest adds the interest earned in each period back to the principal, so the next period charges interest on a larger amount. Same $10,000 at 5% compounded annually for 3 years gives you $1,525 in interest. The difference looks small here. Scale it to a mortgage or a long-term investment and the gap becomes significant enough to alter financial outcomes.
A Matter Of Interest Simple Vs Compound
The technical distinction matters because both are used simultaneously in different products, often by the same institution. A personal loan might advertise a "flat rate" of 6%, which is simple interest presented in a way that sounds reasonable. A savings account might advertise 4% APY, which is compound interest calculated monthly or daily. The APR and APY numbers can look similar while the actual cost or return diverges substantially over time. Here is what nobody tells you about the compounding frequency. A 5% nominal rate compounded annually, monthly, and daily produces three different effective yields. Annual gives you exactly 5%. Monthly gives you about 5.12%. Daily gives you about 5.13%. The difference between monthly and daily is marginal, but the jump from annual to monthly is where people get surprised. If your loan compounds annually instead of monthly, you save money. If your investment compounds annually instead of monthly, you lose money. The direction of the compounding frequency flip determines who wins. I ran into a specific edge case once that took me about three weeks to resolve for a client. They had a cross-border loan where the contract specified simple interest but the repayment schedule was structured with monthly installment payments. The bank's internal system automatically applied compound interest logic to the declining balance, charging interest on interest that was never supposed to accrue. We had to go through 47 months of transaction history and manually recalculate every payment using the simple interest formula on the remaining principal. The discrepancy was roughly 2.3% of the total amount paid, which translated to about $4,200 on a $180,000 loan over four years. The workaround was to export the full amortization schedule, rebuild it in a spreadsheet using the correct simple interest method, and present the side-by-side comparison to the bank's disputes department. They conceded after the second audit.
For anyone trying to work this out themselves, the practical approach is straightforward. Write down the principal, the stated rate, the compounding frequency, and the term. Then calculate using the correct formula. For simple interest: I = P × r × t. For compound interest: A = P(1 + r/n)^(nt), where n is the number of compounding periods per year. Do not trust the advertised rate alone. Ask for the APR or APY and the compounding schedule. If the lender refuses to disclose the compounding frequency, walk away. That is not a normal request and they should have no problem answering it. One counter-intuitive point that beginners miss is that simple interest loans can actually be more expensive than they appear if the repayment structure front-loads principal payments incorrectly. With a declining balance simple interest loan, paying extra toward principal early reduces the base on which future interest is calculated. But some lenders structure simple interest loans with fixed monthly payments that do not adjust when you make extra payments. You end up prepaying principal that should have been reducing interest, and the loan term does not shorten as much as you expect. Always verify whether extra payments actually reduce the principal balance or just adjust the payment allocation. Another nuance involves the day-count convention. Some institutions use 360 days for interest calculations, others use 365. On a large loan over many years, this convention shift can change the total interest paid by a noticeable amount. I have seen cases where a 360-day basis added several hundred dollars in extra interest compared to a 365-day basis on the same nominal terms. It is a small detail that compounds over time, which is unfortunately ironic given the topic.
Get the Full Details

There are scenarios where neither simple nor compound interest formulas apply cleanly. Floating rate loans that reset periodically based on a benchmark index require a different approach. You need to model each rate adjustment period separately and recalculate the balance after every reset. This is where spreadsheets become essential rather than optional. Fixed formulas will not capture the variability of a floating rate product over a multi-year horizon. The honest limitation of all interest calculations is that they assume perfect compliance with the payment schedule. Late payments, partial payments, grace periods, and fee waivers all disrupt the mathematical model. The clean formulas break down the moment real-world payment behavior enters the equation. This is why automated payment reminders and payment scheduling tools exist, even though they are not foolproof. Missing a single payment on a compound interest loan can set you back significantly because the missed payment does not just add a late fee, it changes the compounding trajectory for the entire remaining term. If you are comparing loan offers, demand the full amortization schedule in writing. Look at the total interest paid across the entire term, not just the stated rate. If you are investing, check how frequently interest compounds and whether reinvestment is automatic or manual. These details determine whether you are getting the mathematical outcome you expect or something materially different.