What This Book Actually Does For You
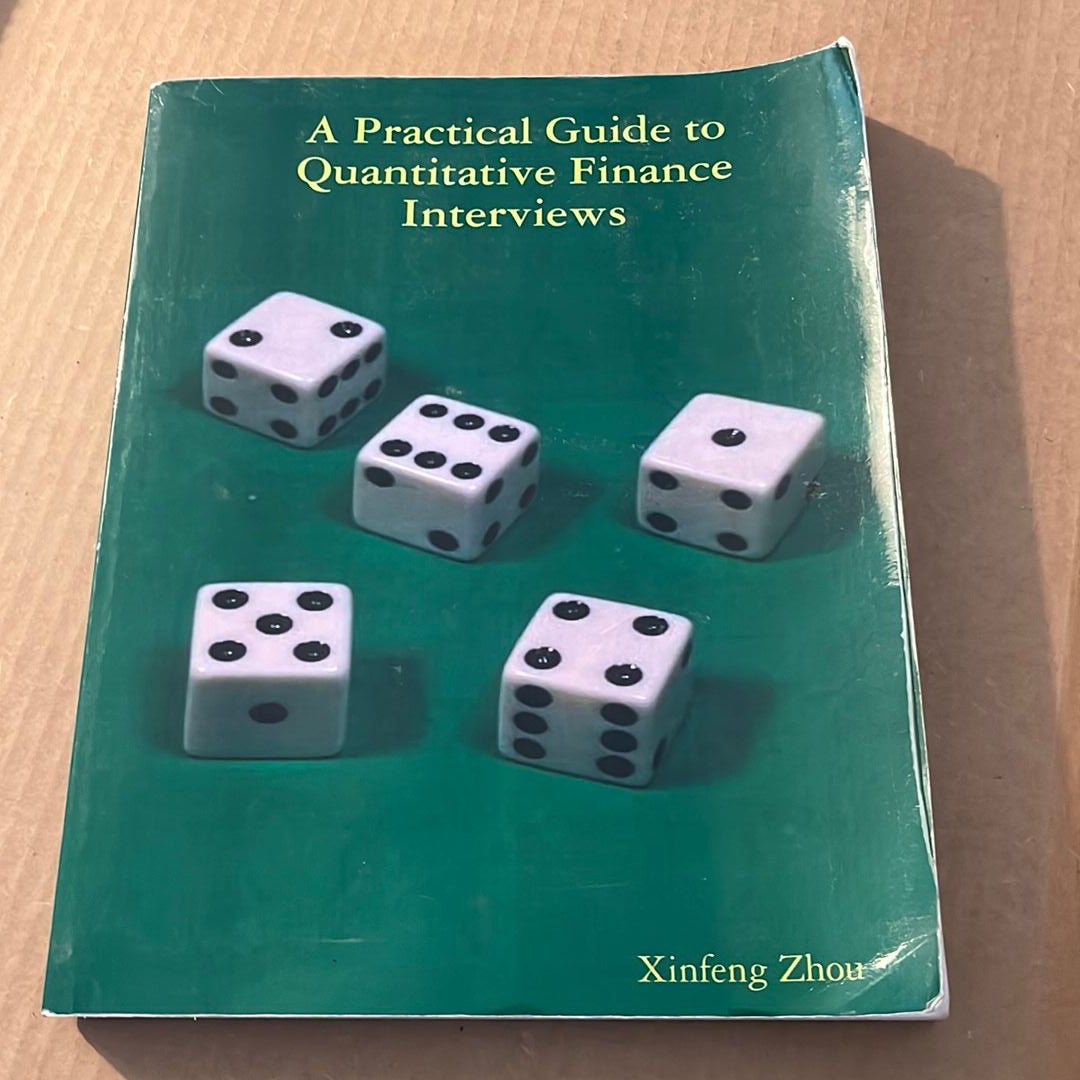
A Practical Guide To Quantitative Finance Interviews Paperback April 9 2008 is one of those books that most quants will tell you about but won't necessarily recommend unless you push them for an honest answer. The core premise is straightforward. It compiles real interview questions asked by hedge funds, prop trading shops, and investment banks, then walks through the solutions step by step. If you're preparing for a quant interview, you've probably seen the same list circulating on forums. This book collects many of those questions in one place with detailed answers instead of leaving you to piece together forum posts and Stack Exchange threads. The book is organized into sections covering probability, statistics, stochastic calculus, coding, brainteasers, and some finance-specific questions. The probability section is where most of the value sits. Questions like "what is the expected number of flips to get two consecutive heads" appear frequently enough that knowing the general method matters more than memorizing the specific answer. The brainteaser section is less useful than people make it seem. I have interviewed candidates who spent thirty minutes solving a riddle and still didn't get the role because they couldn't set up a basic Monte Carlo simulation afterward.
Working Through A Practical Guide To Quantitative Finance Interviews Paperback April 9 2008
Here is how I actually used this book when I was on the other side of the interview table. I did not read it cover to cover. That is a waste of time. I went through the probability and stochastic calculus chapters first, worked every problem on paper without looking at the solution, then compared my approach against the book's. The difference between getting it right and understanding it shows up almost immediately. Most candidates will arrive at the correct numerical answer through a shortcut they do not fully justify. Interviewers know this. They will ask a follow-up question that exposes the gap. I remember one specific candidate who solved a question about the expected hitting time of a one-dimensional random walk using a formula they had memorized from this book. The answer was correct. I asked them to derive it from first principles using the Markov property and conditional expectation. They froze. Not because the derivation was hard, but because they had never actually done it. They had recognized the problem type and applied a stored result. That distinction matters in an interview. The book gives you the result. You need to understand the derivation well enough to reconstruct it under pressure. The coding questions in the book are decent but somewhat dated. Several of the problems assume familiarity with older programming conventions or languages that are less common now. I would pair this book with actual coding practice on platforms where you write and submit working solutions, not just think through the logic. The gap between writing code on paper and writing code that runs is real and it shows up in the technical screening round.
What the Book Gets Wrong or Skips
The biggest limitation is that it does not cover machine learning or modern data science questions, which have become standard in many quant interviews since the book was published. If you are interviewing for a role that involves predictive modeling, feature engineering, or basic ML theory, this book will not help you with that section. You will need separate preparation for that. It also does not address salary negotiation or the logistics of the interview process itself, which some candidates find more stressful than the technical questions. Another issue is the treatment of stochastic calculus. The book assumes you already know Itô's lemma and can manipulate stochastic differential equations comfortably. If you are weak on that foundation, the worked examples will feel like magic tricks rather than logical steps. I would go back to a proper textbook like Shreve for the derivations before returning to this book. The book is better used as a problem set with solutions than as a primary learning resource for the more advanced material. The brainteaser chapter has some genuinely good questions, but several of the answers rely on assumptions that are either unstated or debatable. In an interview setting, pointing out an ambiguity in the problem statement is often more impressive than producing the expected answer. Interviewers are testing whether you can think critically about the framing, not whether you can guess what they had in mind. This book does not explicitly teach that skill. You have to pick it up from watching how other people handle those questions in mock interviews or discussion forums.
Get the Full Details
How to Use This Without Wasting Time
The most efficient approach takes about two to three weeks if you are already comfortable with undergraduate-level probability and calculus. Start with the probability section. Set a timer for twenty minutes per problem. If you cannot solve it within that window, look at the solution, close the book, and redo it from scratch without peeking. If you still cannot reconstruct the logic after looking at the answer, you do not actually understand it and you need to review the underlying theory. Move on. Do not spend more than an hour on a single problem. The goal is breadth of exposure, not deep mastery of every question. For the stochastic calculus problems, allocate more time. These questions tend to compound quickly if you miss a subtlety in one step. I usually spent forty-five minutes to an hour on each one, working through the derivation carefully. If you are not confident with change of measure arguments or Girsanov theorem applications, those are the areas that will trip you up. The book's treatment of those topics is abbreviated. Supplement it with lecture notes or a dedicated text before attempting the harder problems. The brainteaser section can be rotated into your preparation as a warm-up exercise. Ten to fifteen minutes a day is enough. Do not treat these as a significant portion of your study time. They are the least predictive part of the interview process and spending excessive hours on them gives diminishing returns. Most firms ask maybe two or three brainteasers in a full interview cycle. The probability and coding questions dominate the actual evaluation.
There is no official download link for this book since it is a published paperback. You can find it on Amazon, Barnes & Noble, and used book sites. The Kindle edition exists but some candidates report that the typesetting of mathematical formulas is unreliable on that format, which makes working through derivations frustrating. I would recommend the physical copy or at minimum verifying the digital version before relying on it for study.
When This Book Will Not Save You
If you have zero background in probability theory, this book will not bring you up to speed. It is not a textbook. It assumes you know what a martingale is and can compute a conditional expectation without prompting. Same with stochastic calculus. If those are unfamiliar terms to you, spend time on the fundamentals first. The book is a review and practice resource, not an introduction. Similarly, if the role you are targeting is heavily focused on implementation or infrastructure rather than research and modeling, this book may not align with what you actually need to prepare for. Some shops prioritize system design, low-latency optimization, or distributed computing questions that this book does not address. Know what kind of quant role you are applying for before deciding how much time to invest. The interview format varies significantly across firms and even across teams within the same firm.