How to Actually Use a Worksheet in Accounting
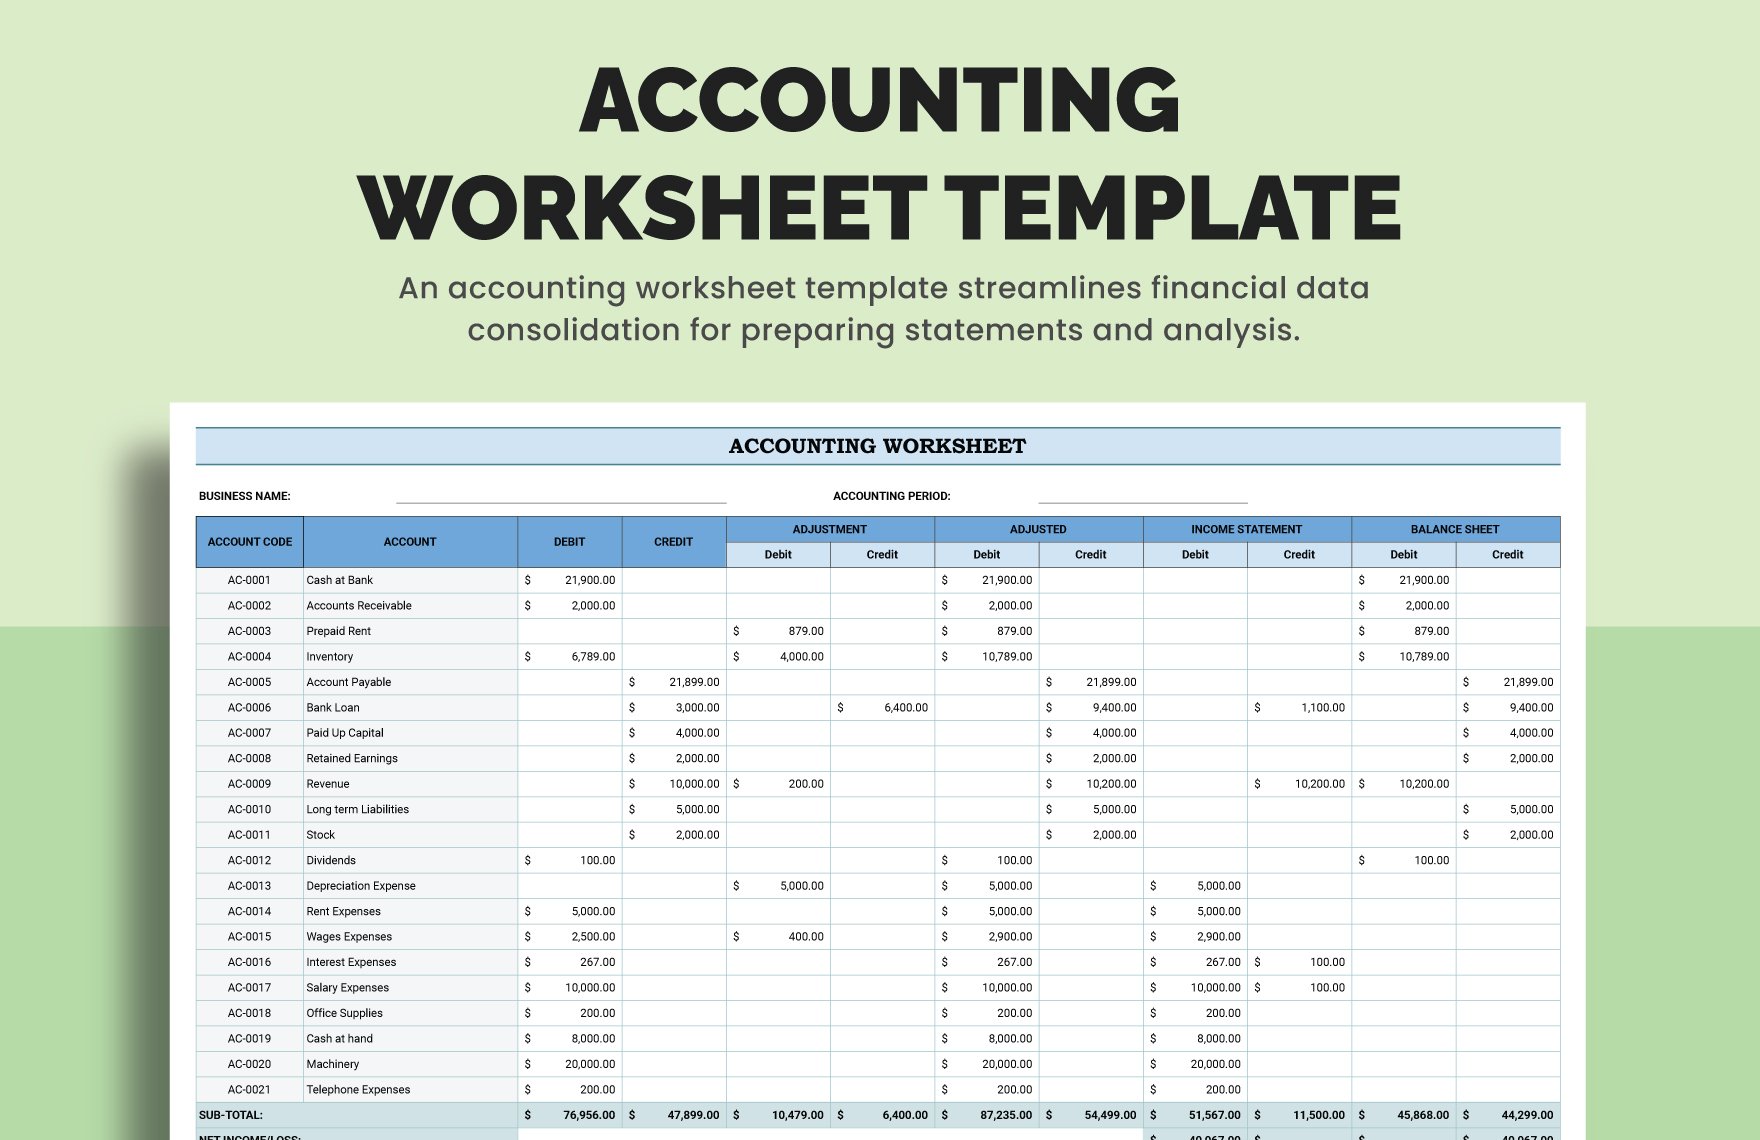
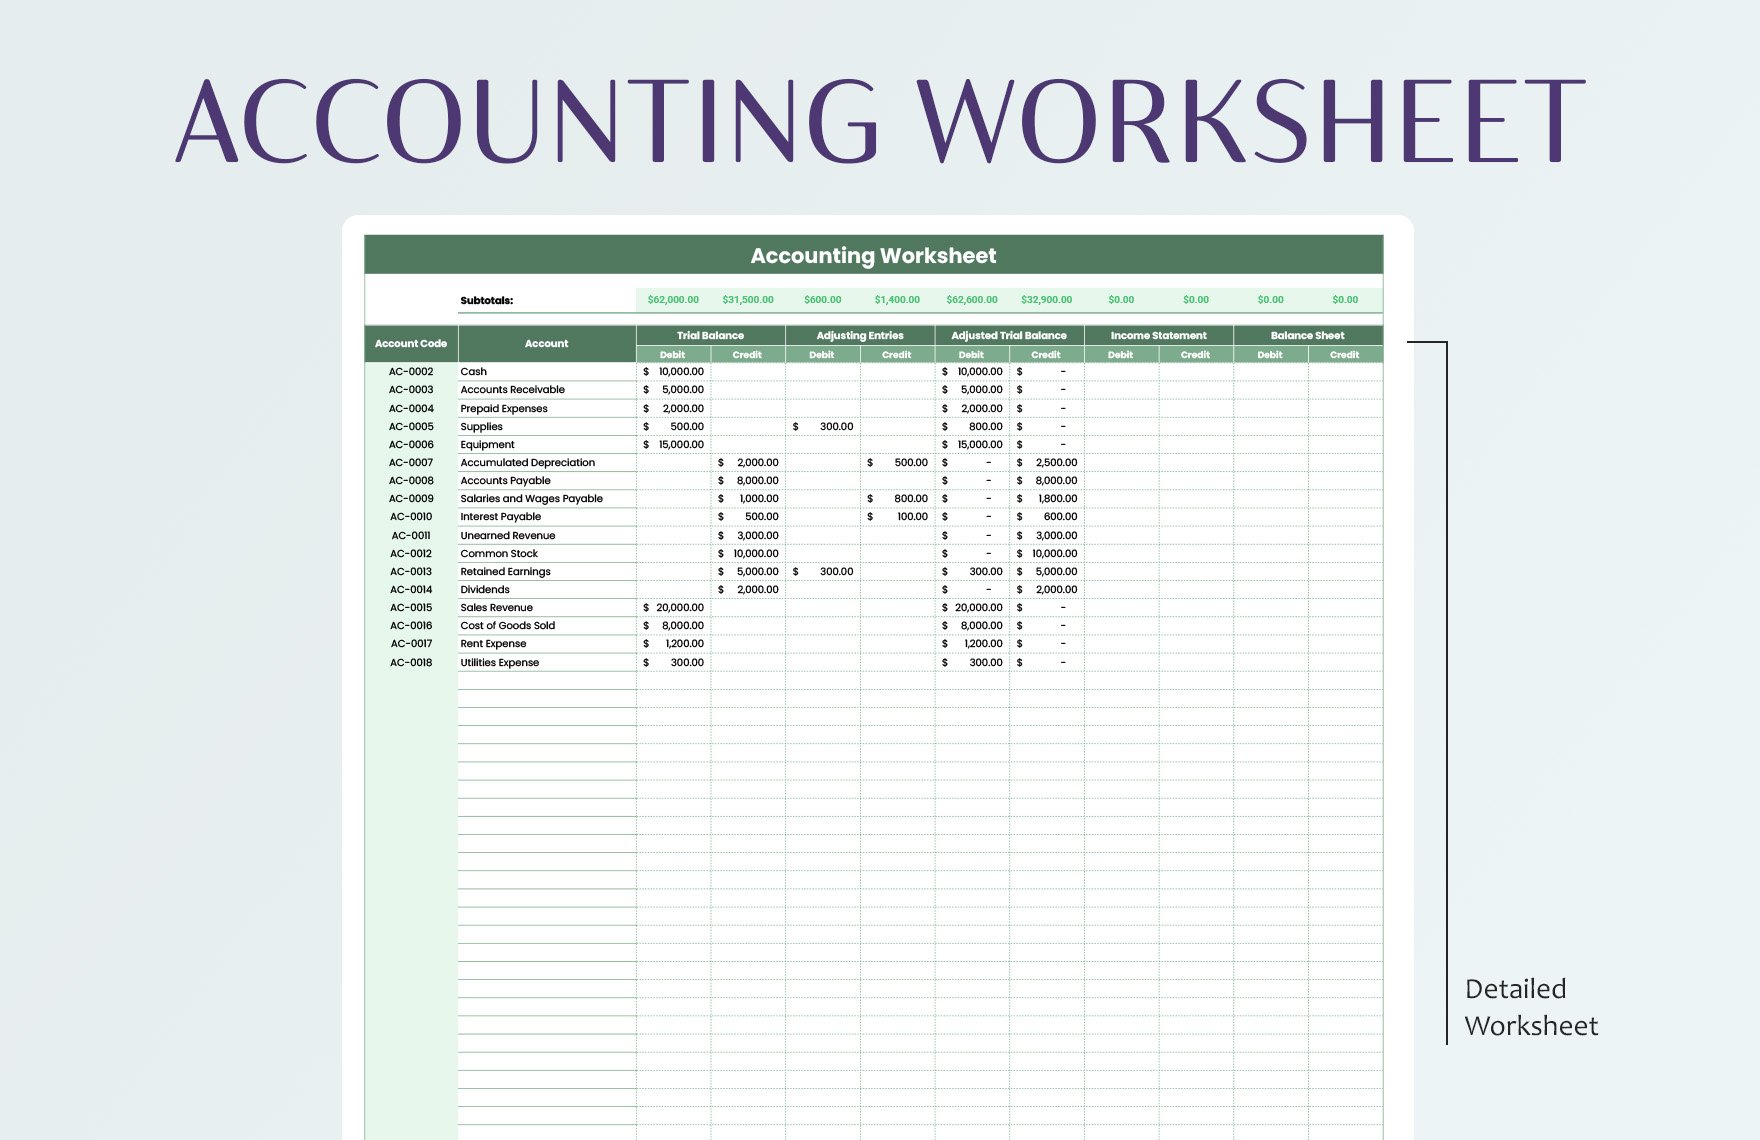
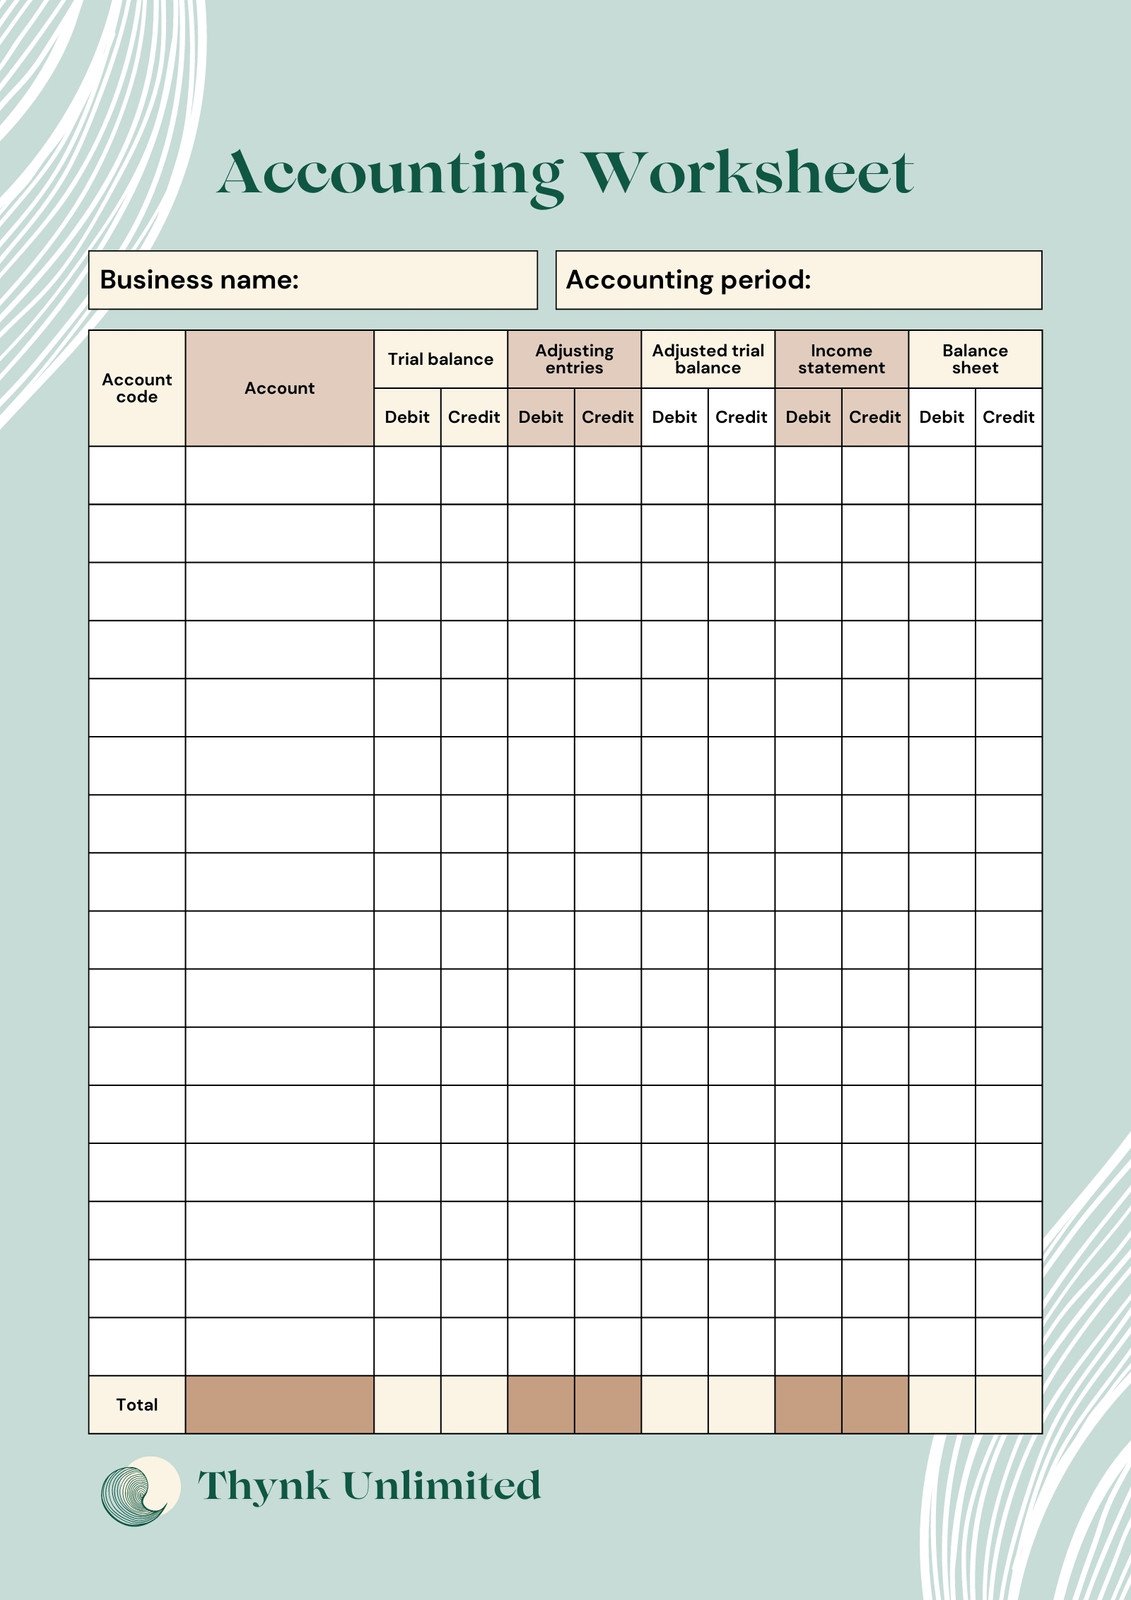
A worksheet is just a blank grid you use before you touch the actual accounting software. It's where you dump all your trial balance figures, run your adjustments, and verify that debits equal credits before anything gets posted to the general ledger. Most firms use Excel for this, though some still do it on paper. I use Excel. It's faster and easier to audit later. Here's how I actually build one from scratch when a client comes in with messy books. First, I lay out the columns. You need four sets: Adjusted Trial Balance, Income Statement, and Balance Sheet. Each set gets a debit and credit column. That's twelve columns minimum. Sometimes I add two more for prior-year comparisons if the engagement requires it. The layout is standard, but getting it right in the first try saves me from reformatting later. I start with the trial balance. Pull it directly from the ledger or have the bookkeeper send it over. If it doesn't balance, stop there. Don't adjust numbers to make it work. Call the client and explain the discrepancy. I had a situation once where the AP subledger was $3,400 short because a vendor payment was recorded in two different periods. The worksheet wouldn't balance no matter what I did. I traced it back through the bank reconciliation and found the duplicate entry. Fixed that and moved forward.
Steps for Creating A Worksheet In Accounting
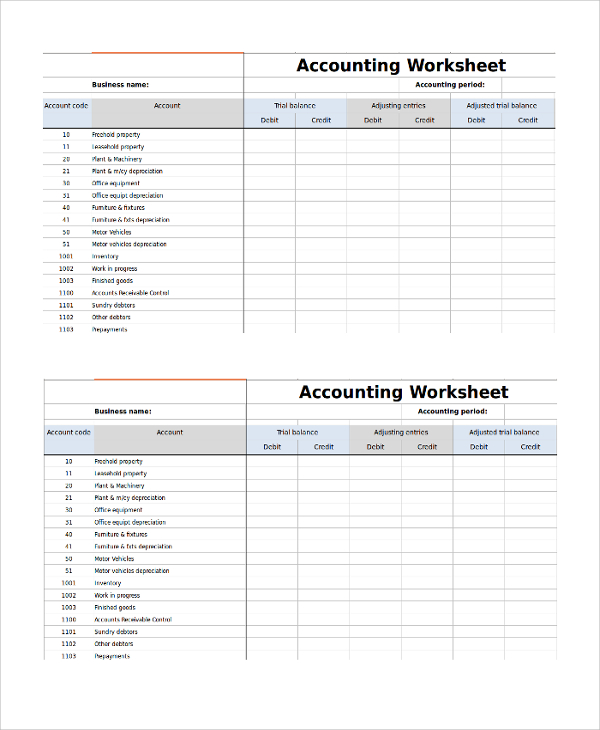
Column one lists every account from the chart of accounts. Assets, liabilities, equity, revenue, and expenses in that order. Don't skip accounts even if the balance is zero. Leave space between major categories so you can spot things faster later. I leave two blank rows between current and non-current sections. Next column is the unadjusted trial balance. Debits on the left, credits on the right. Double-check your totals. They must match. If they don't, you have an error somewhere in the ledger. Go back and find it before proceeding. Then come the adjustment columns. This is where most people mess up. I list each adjusting entry separately with a reference number. Depreciation, accruals, deferrals, bad debt reserve. Whatever the period requires. I keep the reference numbers consistent with the journal entries so auditors can trace everything without frustration.
After adjustments, I calculate the adjusted trial balance. Same format as before but with new numbers. Once again, verify debits equal credits. Then I split those numbers into the income statement columns and the balance sheet columns. Revenue and expense accounts go to the income statement. Everything else goes to the balance sheet. The final check is net income or loss. It should be the same number whether you calculate it from the income statement columns or by subtracting total liabilities and equity from total assets. If they differ, you made a classification error somewhere. I've seen people put a revenue account in the balance sheet section by accident. It happens more often than you'd think. One thing nobody tells beginners: worksheets don't replace proper journal entries. They're a working document, not a permanent record. I've seen firms try to use worksheets as the basis for posting entries without going through the actual journal. That creates audit trails that fall apart under scrutiny. Always create formal journal entries and post them to the ledger. The worksheet just helps you verify the math.
Get the Full Details

Another nuance: when you handle intercompany eliminations or consolidation adjustments, the worksheet becomes essential. Standard trial balance procedures won't catch those. I build a separate elimination column in my worksheet layout. It keeps things organized instead of spreading adjustments across multiple grids. This setup took me about three months to refine properly. Before that, I was wasting time cross-referencing between sheets and missing entries. The main downside of worksheets is that they're manual. Human error is always a risk. If you're working with high transaction volumes, spreadsheets can slow down significantly. I've had files lag on anything over 500 rows. For those cases, I recommend using accounting software with built-in worksheet functionality. QuickBooks Enterprise and Sage 300 both handle this well. You lose some flexibility compared to Excel, but you gain speed and fewer mistakes. If you want a template, search for "accounting worksheet template Excel" and pick one with pre-formatted columns. Don't build from scratch every time. The structure never changes. Just update the account names and numbers for each period. I keep a master file with my standard layout and copy it for each new engagement. Cuts my setup time to about ten minutes per client.