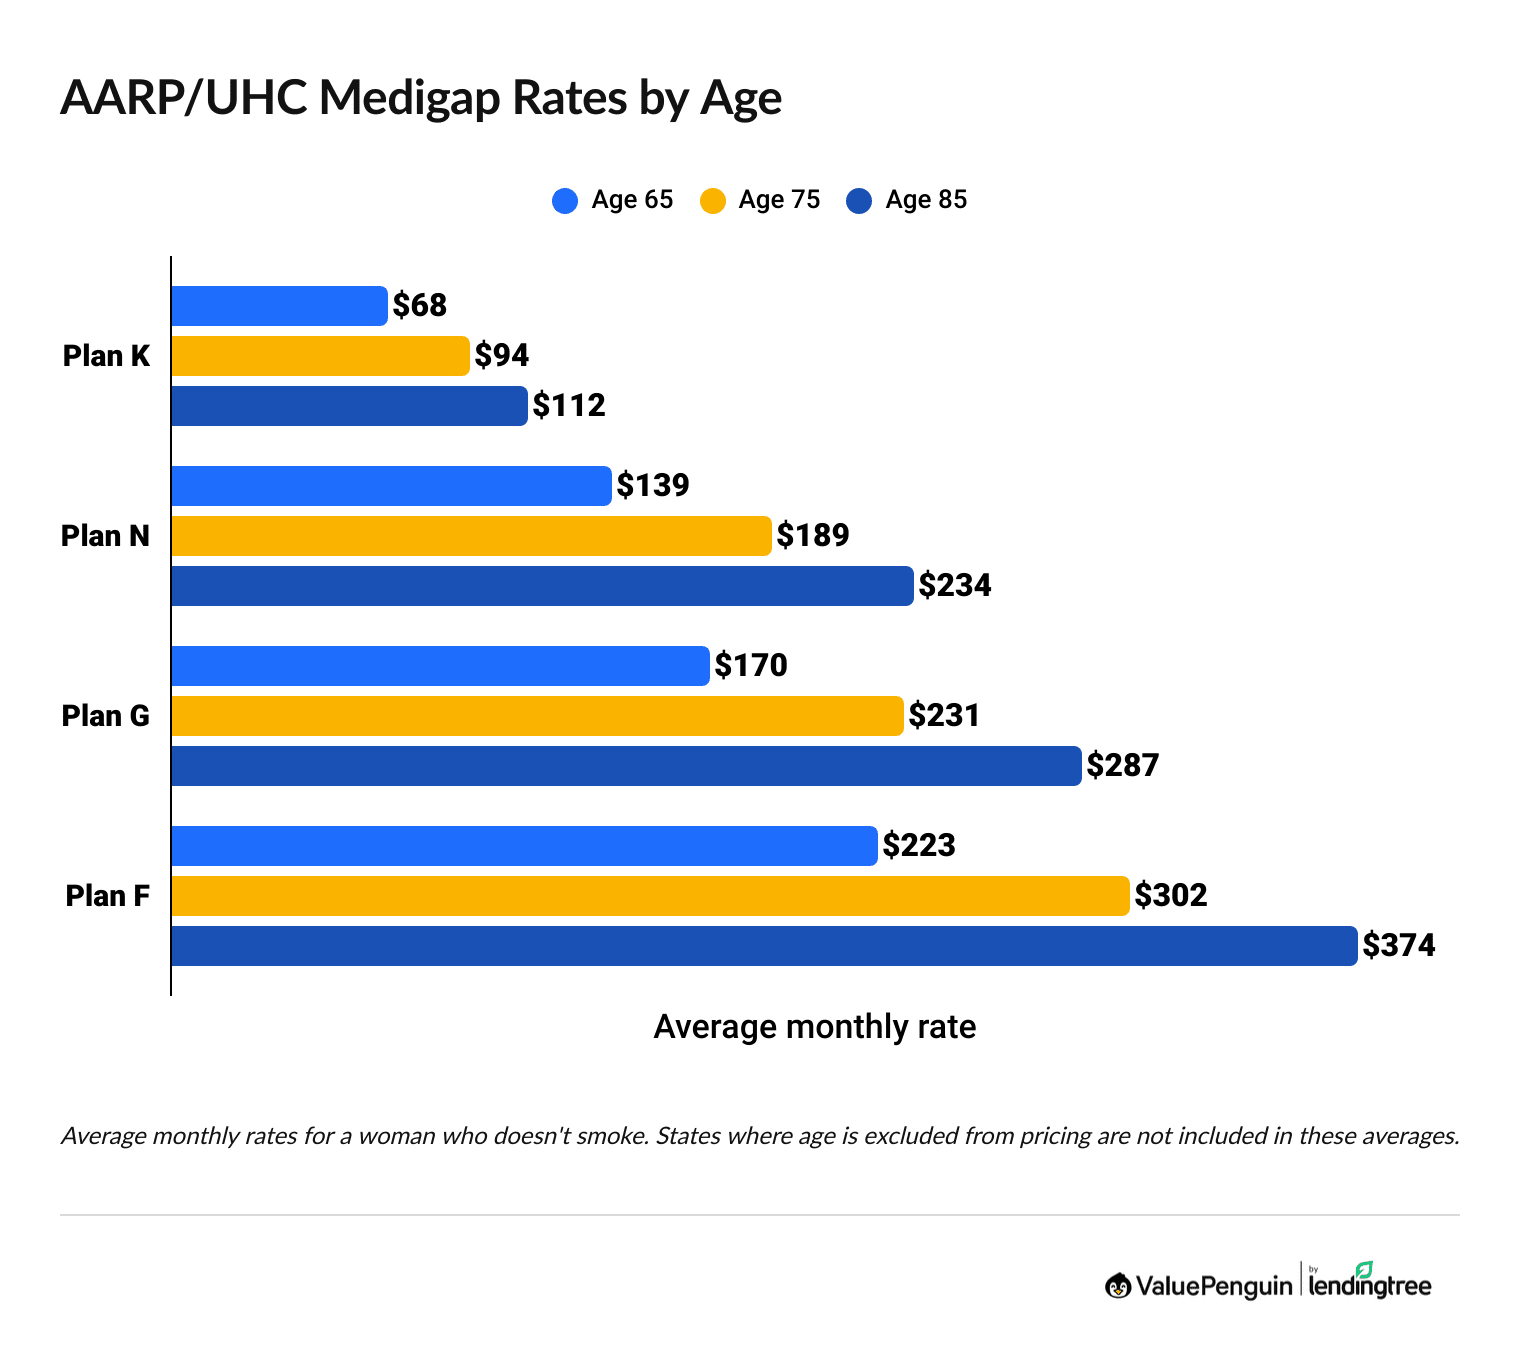
How to Track Your AARP Medicare Supplement Rate Increase History
If you've ever opened a Medicare Part B statement and seen a premium that looked nothing like last year's, you already know the basics of how AARP Medicare Supplement (Medigap) premiums work. These are not fixed rates. They're individually priced based on several variables that change from state to state and from policyholder to policyholder. The history you're looking for lives in your billing records and in state insurance department filings. This is a practical walkthrough. The most important thing to understand first is that AARP doesn't set rates. The actual carrier behind your policy does. WellCare currently administers AARP-branded Medigap policies in most states. What you see on your mailer comes from a company filing actuarial data with your state's insurance department, not from AARP headquarters. This distinction matters because it determines where you look for historical rate data.
Aarp Medicare Supplement Rate Increase History
Here's what most people don't realize when they try to pull their own rate increase history: your specific increase amount is rarely visible in any single public database. Insurance companies file aggregate rate requests, not individualized rate change notices for each policyholder. You'll typically find three types of documentation that, when combined, give you a complete picture. First, pull your own billing history. Log into your WellCare member portal or check your paper statements going back at least three to five years. Record the premium amount, the effective date of any change, and the reason cited in the correspondence. Some carriers include a brief narrative. Most don't. Just the dollar amounts and dates give you enough to map the trajectory. Second, check your state's insurance department website. Most states publish annual or biannual rate filings for Medigap policies. Search for "medigap rate filing" plus your state name. In California, for example, the Department of Insurance posts every rate request for standardized Medigap plans, including the filing company, the proposed increase percentage, and whether the request was approved, modified, or denied. Other states vary widely in how much they publish. Some post nothing beyond confirmation that a filing was received.
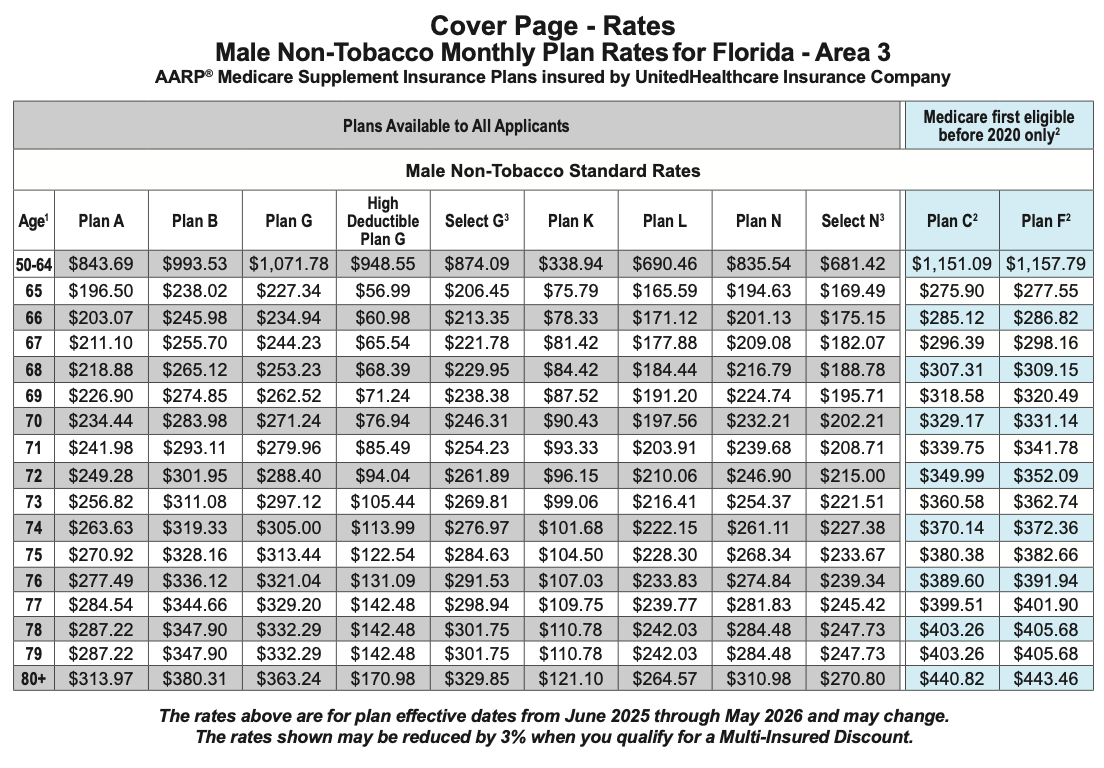
I ran into a specific edge case last year that illustrates why relying on just one source fails. A client in Florida had a WellCare AARP Plan G policy. The rate increase letter mentioned a 7.3% adjustment but gave no breakdown. Her state's insurance portal showed the overall Plan G rate filing for that quarter, which was 6.8%. The 0.5% gap came from an age-tier realignment that affected her particular cohort but wasn't broken out in the public filing. The workaround was straightforward. I pulled the actuarial justification document attached to the state filing, which detailed the three separate rate drivers — medical cost trend, utilization patterns, and the age-tier realignment — then cross-referenced each driver against her policy anniversary dates. The 7.3% total broke down into 4.1% for medical trend, 1.2% for utilization, and 2.0% for the tier shift. Without that document, she would have had no idea why her increase was higher than the published Plan G average. Third, request your policy-specific rating history from WellCare directly. This is a right under most states' insurance codes. You can submit a written request through the member services line or via certified mail. The carrier must provide your individual rate history, including all increases, effective dates, and the regulatory basis for each adjustment. This is usually the most reliable source because it ties every increase to a specific regulatory filing number. The timeline for typical increases follows a pattern, though no pattern is guaranteed. Rate increases on AARP Medigap policies usually occur on the policy anniversary date or on a calendar-quarter boundary. About 60 to 70 percent of annual increases fall in the January renewal window. The remaining increases are scattered across April, July, and October filings. This timing is administrative convenience, not actuarial necessity. The carrier could technically file at any point, but January gives them the most time to process changes before the next Open Enrollment period begins.
Get the Full Details
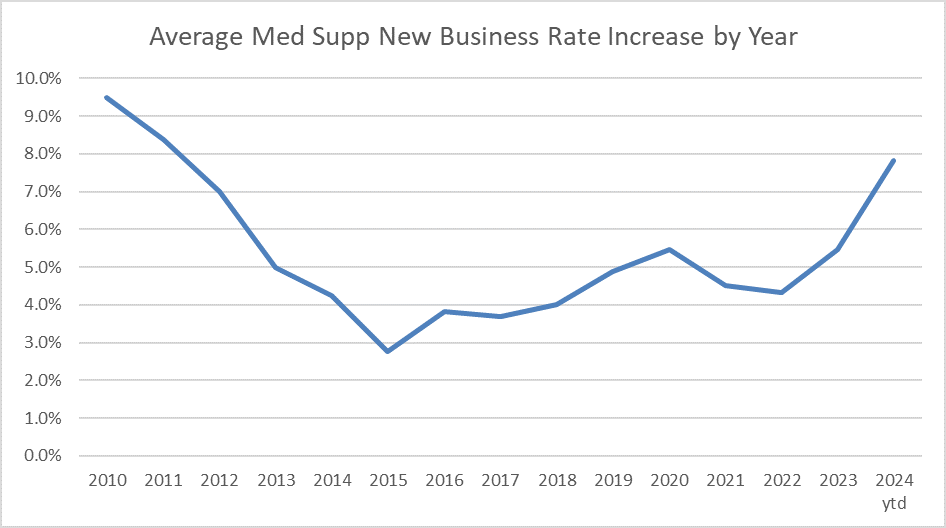
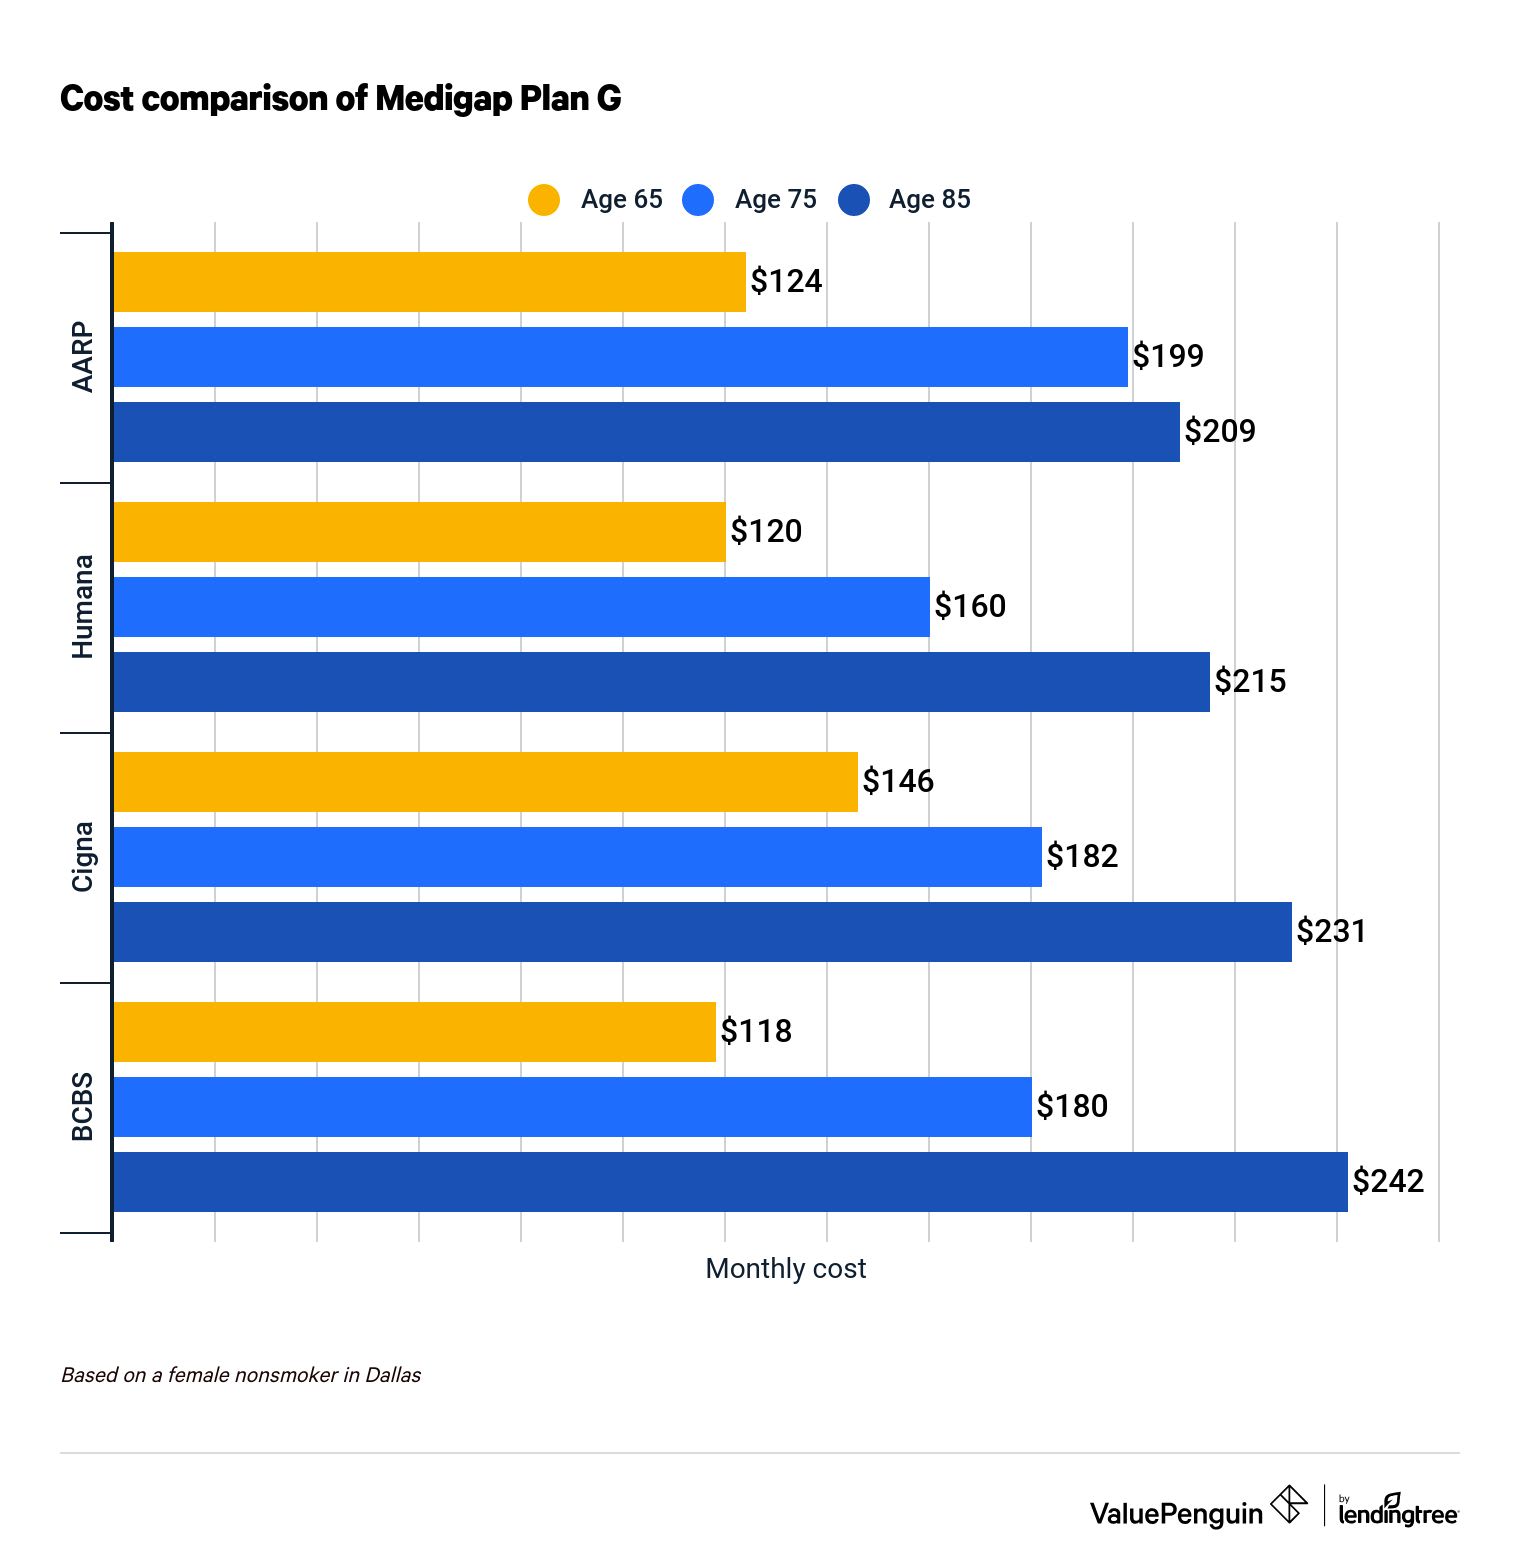
Here's a counter-intuitive point that catches people off guard: a rate increase on your Medigap policy does not necessarily mean your total healthcare costs went up. If your Part B premium increased by the same dollar amount, your combined spend may have remained flat. I've seen this multiple times. In 2024, a policyholder in Arizona noticed a 5.4% increase on her Plan N premium of about $42 per month. She assumed her total healthcare spending had risen significantly. But her Part B premium had decreased by roughly $38 per month due to a lower income-related monthly adjustment amount. The net effect was a $4 increase — barely noticeable, but the rate increase letter made it look like a major jump. Always calculate the total change across all premiums, not just the Medigap portion. Another nuance beginners miss involves the difference between plan-specific rate changes and broad portfolio changes. When you see a headline saying "AARP Medigap rates increasing 5 percent," that figure is a weighted average across all plan types and all policyholders in a given state. Your specific plan — say, Plan F versus Plan G — may have experienced a completely different percentage change. Plan F saw larger increases in some states during 2023 and 2024 because it remained popular among newer enrollees despite no longer being available to people newly eligible after January 2020. Plan G, by contrast, saw more moderate increases in several states as carriers shifted their product mix. The headline number is almost never your number. The practical method for building your own rate increase history takes about 45 minutes to an hour if you have your documents organized. Start by collecting three years of billing statements. Create a simple spreadsheet with columns for date, premium amount, percentage change from prior month, and source document. Fill in the billing data first. Then supplement it with state filing data from your insurance department's website. Finally, add any policy-specific details from your WellCare correspondence. If you're missing a period, submit the formal request to WellCare and note the gap. They usually respond within 15 to 30 business days, though some states require faster turnaround.
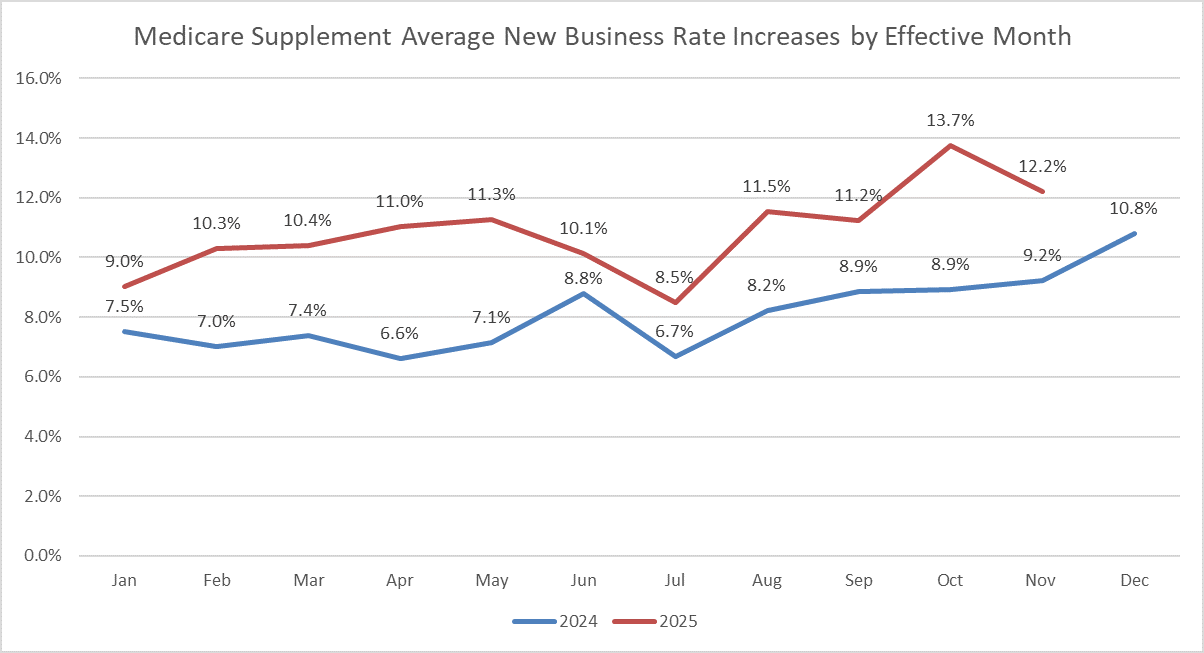
There are real limitations to this approach that you should be aware of. Some states do not publish detailed actuarial justifications for rate filings. In those states, you may get the approved percentage increase but not the underlying cost drivers. North Carolina and Illinois are examples where the published information is relatively thin. In those cases, your WellCare request becomes the primary source, and you may find that the carrier's documentation is more detailed than the state's public filings. This inversion — where the insurer knows more than the regulator makes public — is frustrating but not uncommon. Another limitation is the time lag. State filings are often published months after the rate change takes effect. If you're trying to verify a change that happened six months ago, the filing may still be in draft status or not yet uploaded. I've encountered this with Wisconsin filings in particular, where the Department of Financial Institutions posts rate requests asynchronously and sometimes removes drafts without notice. If a filing disappears, it may have been withdrawn or revised. Your policy remains valid at the increased rate unless the state formally denied the filing, so don't assume a missing posting means your increase was unlawful. For most people, the useful outcome of tracking rate increase history is not regulatory action but financial planning. Knowing whether your premiums have been trending at 4 percent annually versus 8 percent annually helps you budget for the next decade of retirement healthcare costs. AARP Medigap policies historically increase at rates that track closely with medical inflation, which has averaged between 5 and 7 percent per year over the past decade, with spikes above 9 percent in certain years. If your personal history shows consistent increases above 8 percent, it may warrant a comparison quote from another carrier during your next eligible enrollment period. You cannot switch Medigap policies without medical underwriting in most states unless you're in a guaranteed issue window, so price shopping requires timing.
The alternative to manual tracking is using a third-party comparison service, but these tools have significant gaps. Most aggregate publicly available rate data without access to policy-specific documents. You'll get current rates but not historical increases. If your goal is to understand what you've already paid and why, the manual approach described here is the only reliable method. If your goal is simply to find a lower rate now, a comparison tool may save you time even though it doesn't give you the full history. One final piece of advice that isn't obvious: keep every rate increase notice you receive, even the ones that look minor. A 1.5 percent increase seems negligible. But when you're twelve years into a policy, those small increases compound. A 1.5 percent annual increase on a $200 monthly premium grows to a $3.60 difference in year one, $7.29 in year two, and roughly $14.63 in year five. Over a ten-year horizon, that compounds to a meaningful sum. The notices also serve as your primary evidence if you ever need to dispute a calculation error or appeal an increase you believe was applied incorrectly. Without the original correspondence, you're working from memory, which is unreliable for figures that were set months or years earlier.