Getting an Absorption Through Without Losing Your Mind
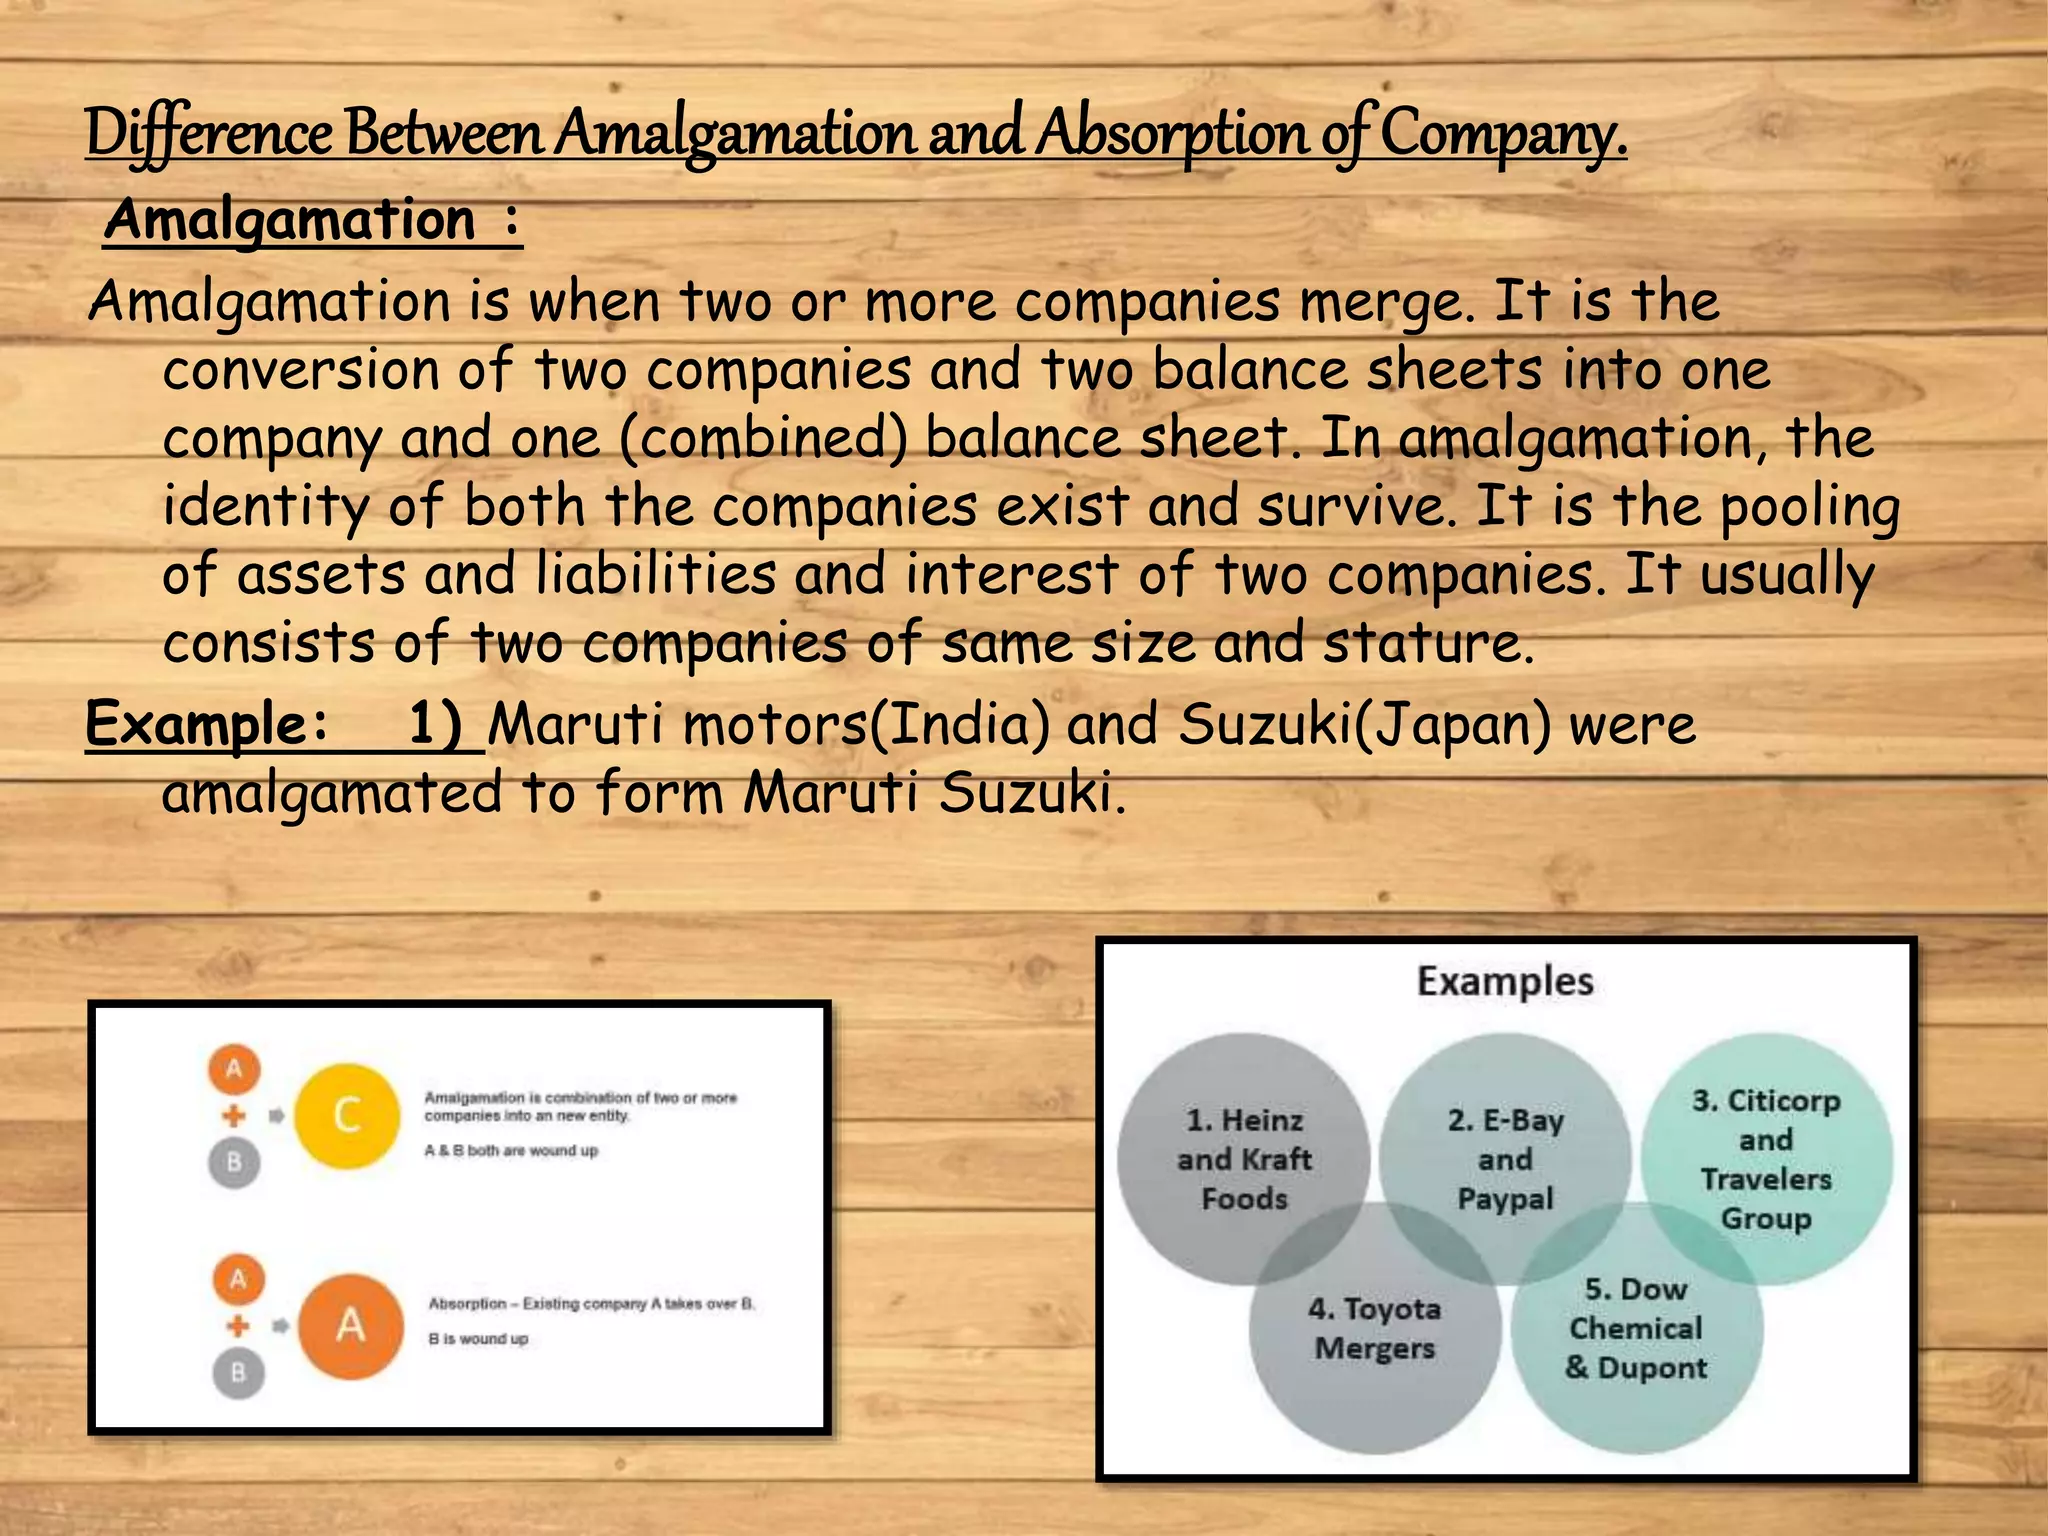
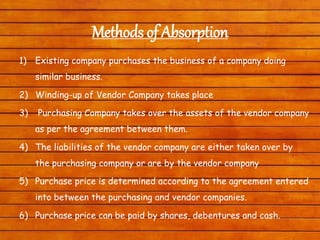
Absorption Of A Company is just one company taking over another and the absorbing entity continues while the target ceases to exist. It sounds simple on paper. It is not simple in practice. The Companies Act, Section 230 to 232, covers it, along with the NCLT procedures, but the real work happens in the gaps between sections. You start with a petition filed before the National Company Law Tribunal. Both companies need to be parties to it. The petitioner submits a draft scheme, along with explanatory statements, valuation reports, and notice to creditors. The NCLT then issues a direction for a committee of creditors and shareholders meeting, if applicable. After that comes the hearing, objections, and finally the sanction order. Then you file with the Registrar of Companies. The usual timeline runs about four to six months if nothing goes wrong. I have seen it drag to fourteen months when a single dissenting creditor raises a procedural objection about how the valuation was done.
I remember a case where the absorbing company assumed all liabilities of the target but failed to specifically list a contingent liability attached to an ongoing arbitration case. The NCLT almost rejected the entire scheme because the disclosure was incomplete. We added a supplementary affidavit from the target's legal counsel confirming the arbitration exposure was covered under the general assumption of liabilities clause, and the tribunal accepted it. That saved the filing. You learn quickly that every liability needs to be explicit. One thing most people get wrong is thinking the scheme is about the share exchange ratio alone. It is not. The ratio matters but the real risk lives in the liability schedule and the employee transfer terms. If you mess up either, creditors will object and the tribunal will not push through. Another counterintuitive point: the valuation report does not need to come from a SEBI registered valuer if the absorption is between two unlisted companies and no public funds are involved. But using one anyway makes the NCLT process smoother. Judges see the report and move on without asking follow-up questions. It costs more upfront and saves weeks later.
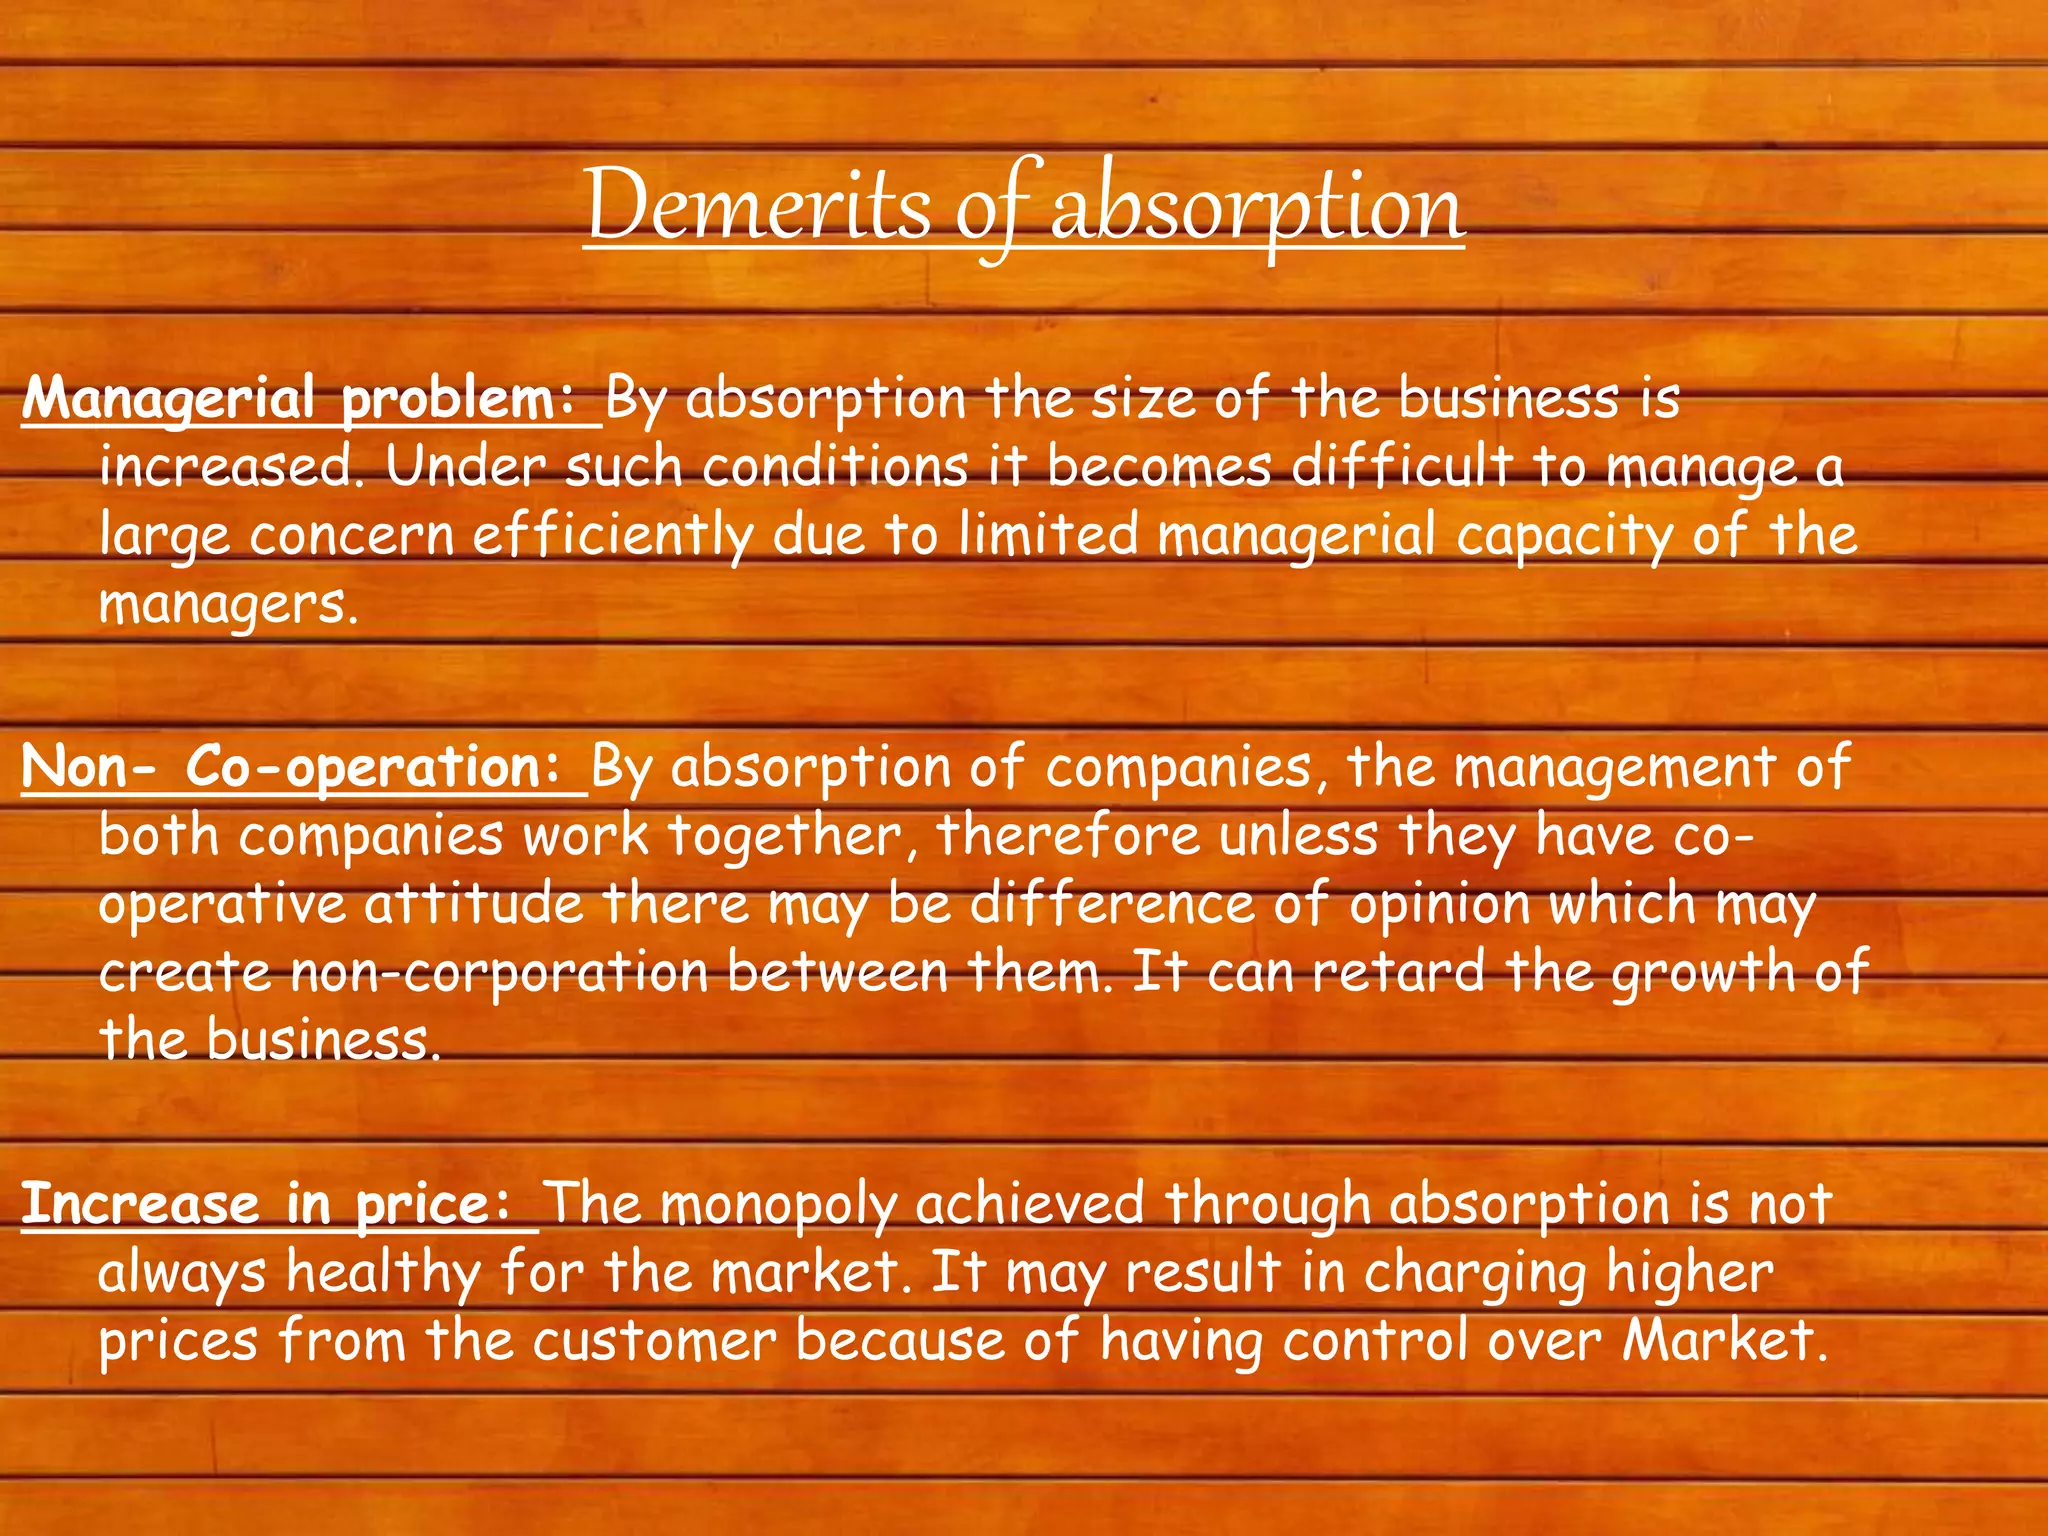
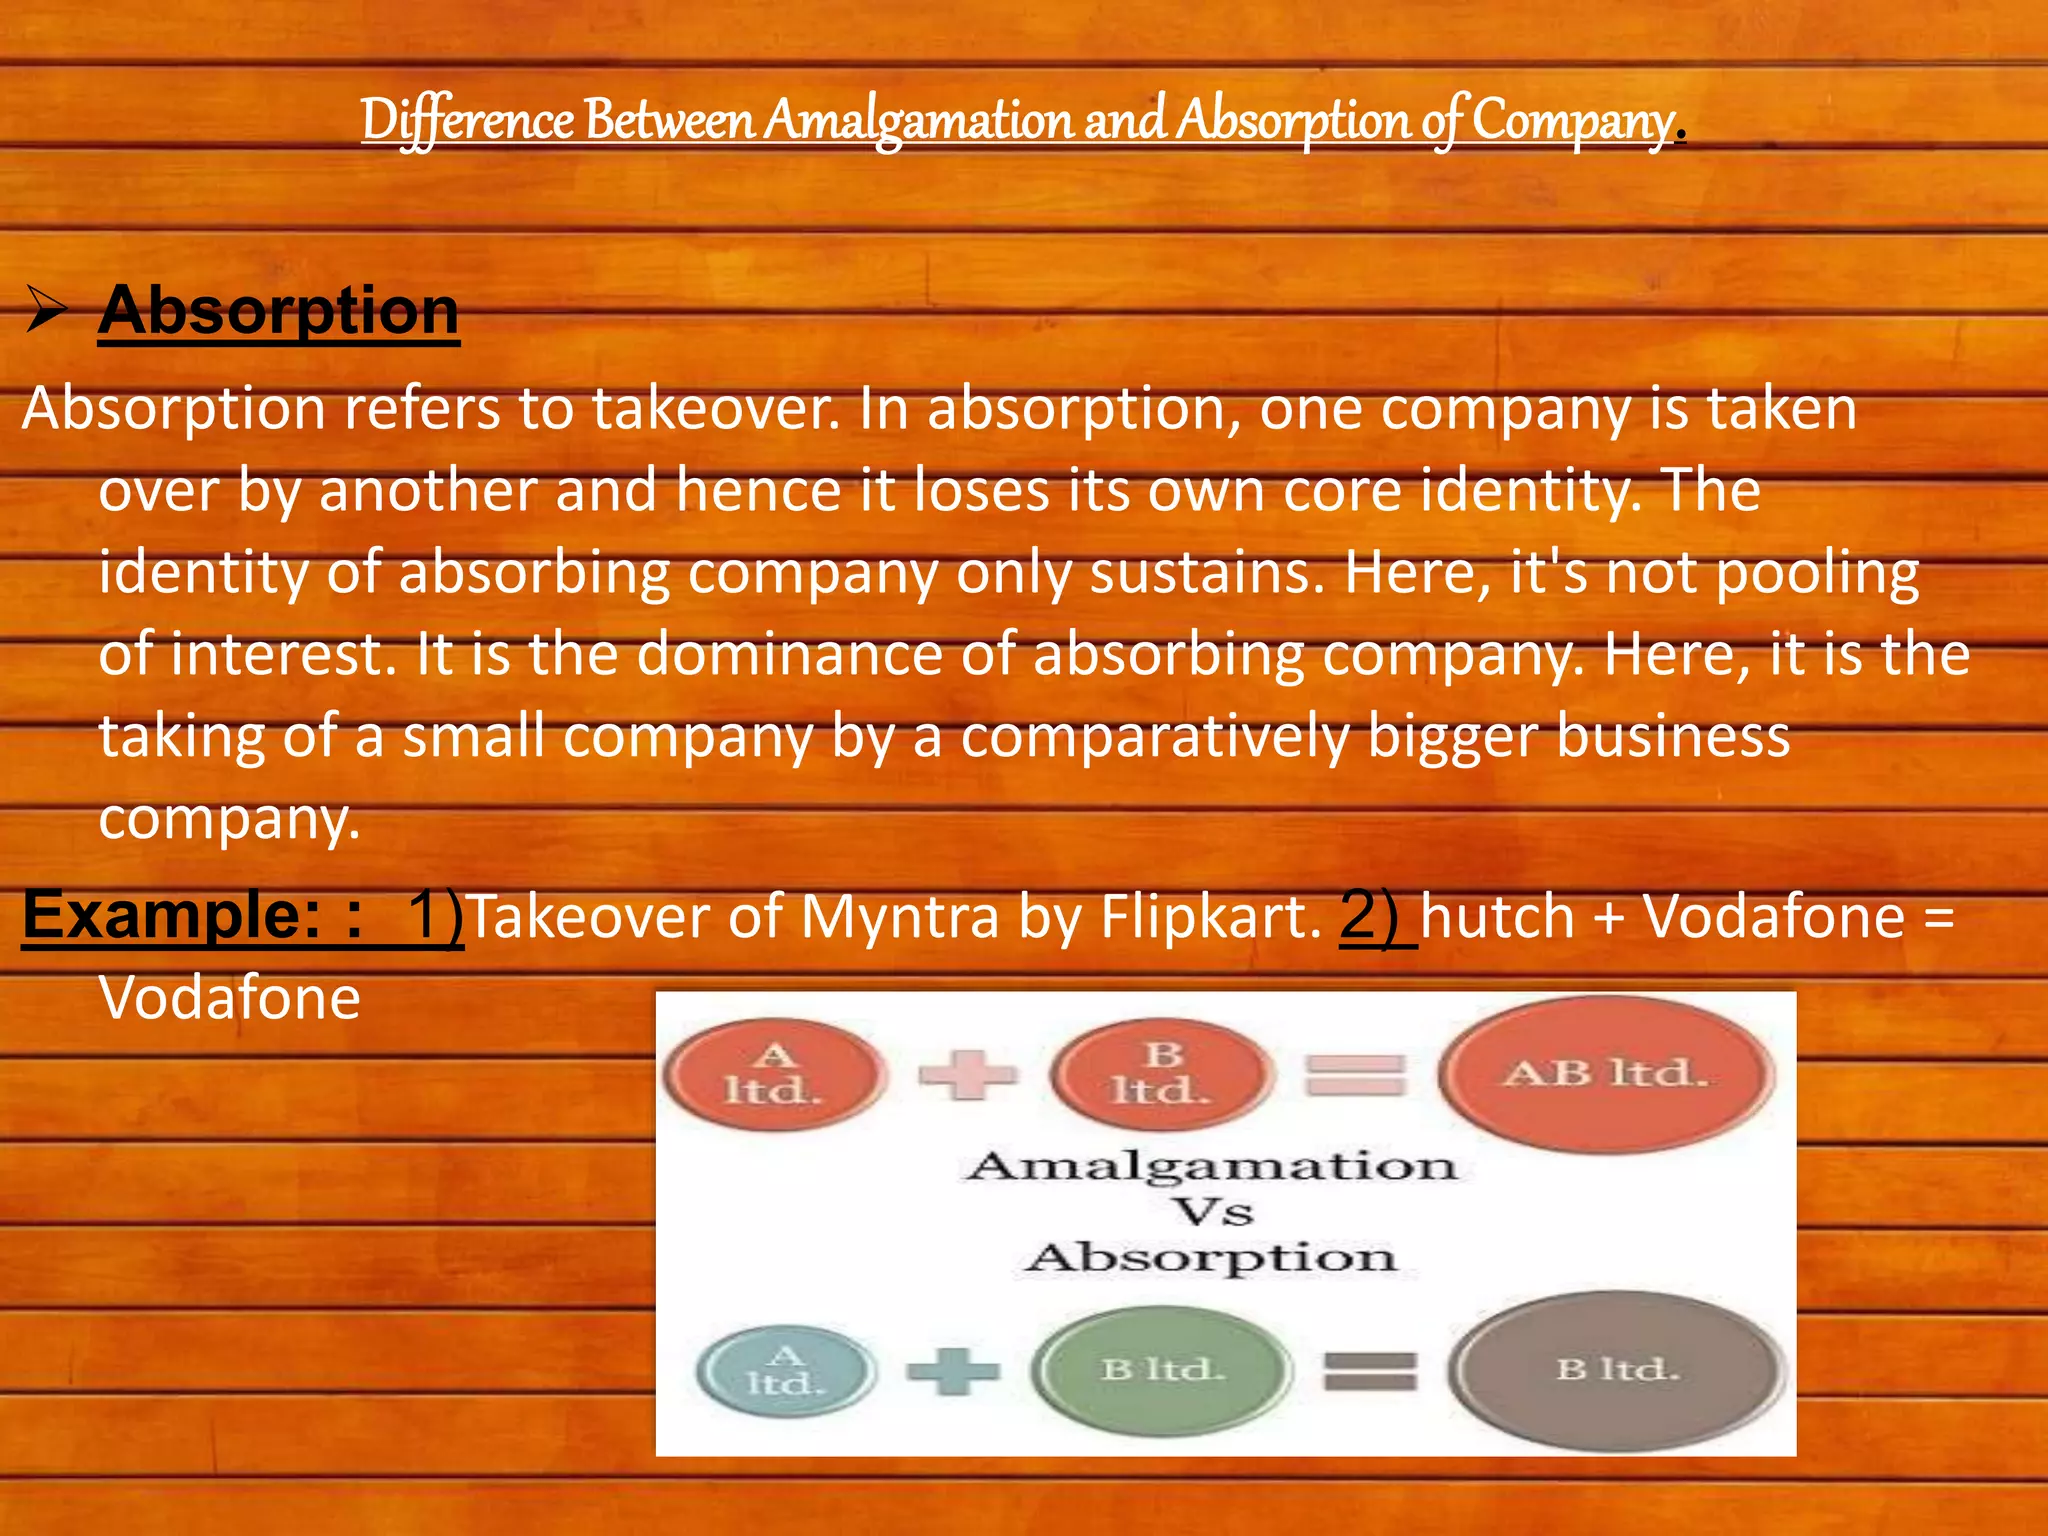
There is also the tax angle that people forget until it is too late. Under Section 47(viia) of the Income Tax Act, a transfer of capital assets in an absorption is not treated as a transfer, so capital gains tax does not apply. But this only works if the scheme satisfies the conditions laid out in the section and if the assets being transferred qualify as capital assets. Inventory or stock in trade does not get the same treatment. I once had a client who tried to absorb a company holding mostly raw material inventory and expected the tax exemption to cover everything. It did not. The inventory portion attracted GST and income tax consequences that inflated the cost by nearly eighteen percent. We restructured the scheme to split the asset classes into two separate transfers and handled the inventory through a standard sale agreement instead. Cleanly resolved. The downsides of absorption are worth listing plainly. It is expensive, legally rigid, and the NCLT has wide discretion to modify your scheme if they find issues. You also lose the ability to negotiate terms after the petition is filed. Once the application is before the tribunal, any change requires a fresh hearing and possibly another round of creditor approval. That is not theoretical. I watched a company try to adjust the consideration amount by twelve percent mid-process and the tribunal made them restart the entire creditor meeting procedure. If the two companies are in the same industry and the goal is purely operational consolidation, a merger might actually be cleaner. Absorption is better when one company is clearly dominant and the other is being dissolved. If both entities need to survive in some form, look at amalgamation instead.
Get the Full Details
The documentation you should have ready before you even think about filing includes the latest audited financials of both companies, the board resolutions approving the scheme, the valuation report, the explanatory statement for shareholders and creditors, and a statement showing how the existing shares will be converted. Missing any of these will delay the first hearing and the tribunal does not tolerate sloppy submissions. After the scheme is sanctioned, you file the order with the ROC within thirty days. The ROC registers it and the absorbing company issues new shares if consideration involves equity. Then you update the charge register if any securities were transferred. The whole post-sanction process usually takes about ten to fifteen working days if your filings are in order. I will say this once: do not treat absorption as a quick fix for debt restructuring. It is a formal legal mechanism with serious compliance requirements. If you are looking for something faster and less cumbersome, examine whether a compromise and arrangement under Section 230 alone might serve your purpose without dissolving the target company entirely. Not every situation needs a full absorption.