How to Actually Use an Accelerated Mortgage Payoff Calculator
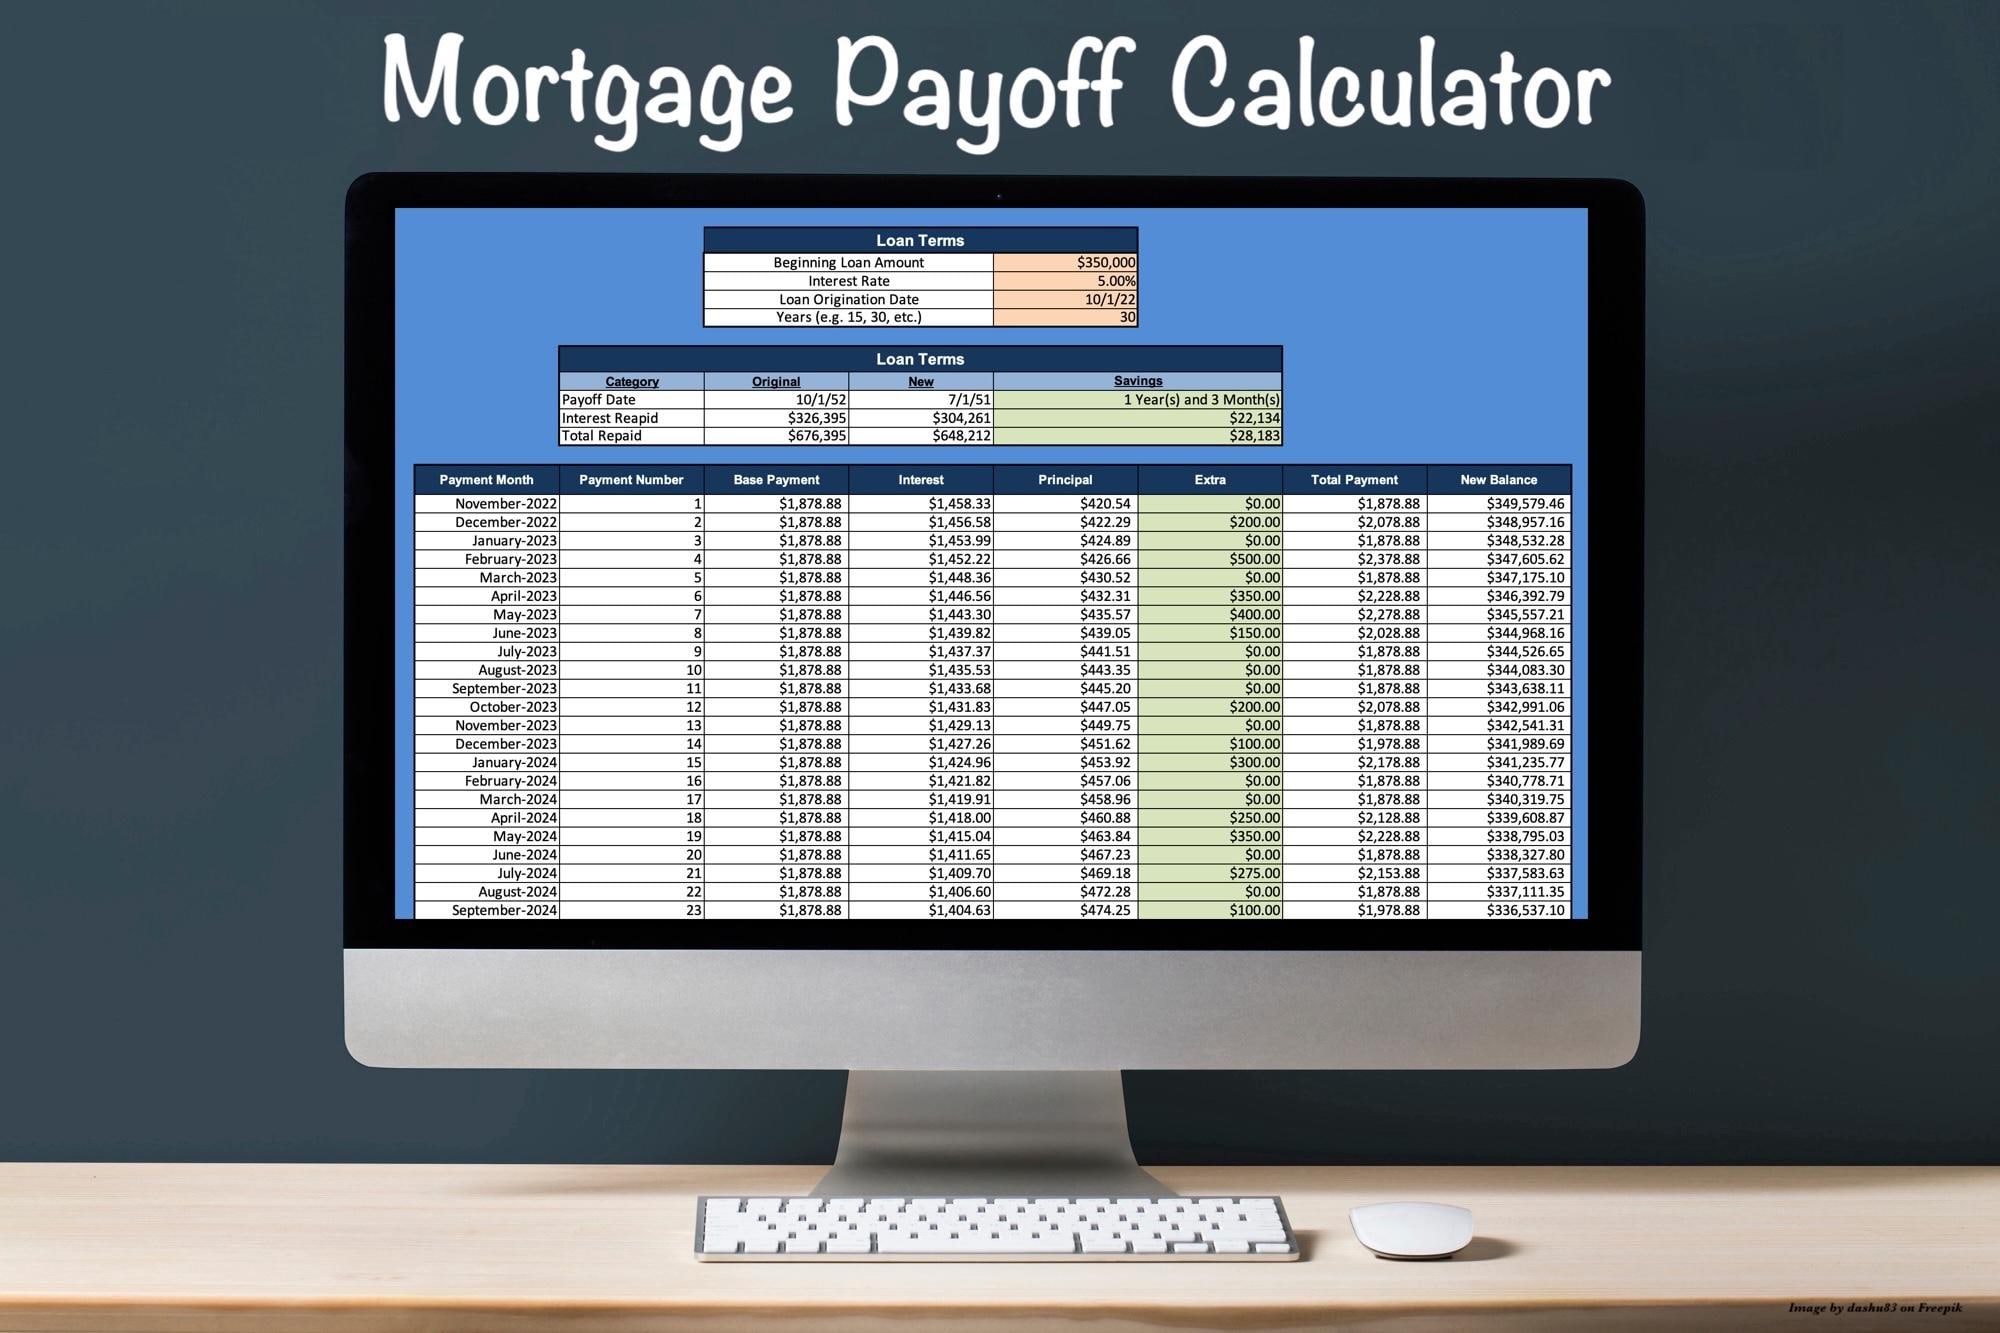
Most people treat these tools like magic boxes. They're not. They're just compound interest calculators wearing a mortgage-specific suit. The basic input is straightforward: current balance, interest rate, remaining term, and whatever extra payment you're planning to throw at it monthly. That's it. The calculator spits out a new payoff date and total interest savings. You read it, and then you realize you've been paying more interest than you thought. I ran into a specific issue last year when a client brought me a calculator output that didn't match their lender's payoff statement. The numbers were close but off by about $3,400 in interest. Turned out the lender was using a 360-day year method while the online calculator assumed a 365-day year. For a $320,000 loan at 6.5%, that difference adds up fast over fifteen years. The workaround was simple: pull your actual amortization schedule from your lender's portal and feed those exact numbers into the Accelerated Mortgage Payoff Calculator instead of guessing from memory or the original closing documents.
Getting Accurate Numbers Before You Start
Log into your mortgage servicer's website and grab three things: current principal balance, your exact interest rate (not the rate from fifteen years ago when you closed), and remaining payment count. Then decide on a realistic extra payment amount. Not the fantasy number from a viral TikTok. The actual number you can sustain for twelve months straight without missing anything else. Most people I talk to pick $500 monthly extras and give up after four months. Put in $200 you can actually maintain instead. The math still crushes the standard schedule. The counter-intuitive part nobody tells you: making extra payments doesn't always save as much as you think if your rate is already low. I had someone in their forties with a 3.25% loan who wanted to pay off the house in six years by throwing an extra $1,200 a month at it. The calculator showed she'd save roughly $41,000 in interest. Solid. But her employer was matching 401(k) contributions she'd have to scale back on to afford that payment, and the market was returning eight percent annually on those same dollars. She was essentially trading an 8% guaranteed return for a 3.25% guaranteed return. Stupid move. The calculator will show you the interest savings. It won't tell you whether it's the right financial move for your situation. Here's another thing most accelerators miss: biweekly payment structures. A lot of lenders pitch their own biweekly programs where you pay half your monthly amount every two weeks, which adds up to thirteen full payments per year. The marketing says you'll save interest and pay off early. The truth is some of these programs charge setup fees between $100 and $300 and monthly servicing fees around $8 to $12. Running those costs through an Accelerated Mortgage Payoff Calculator shows the real picture. Often the net savings shrink by a third once you factor in the fees. Better to just set up automatic extra payments on your own through your bank and skip the lender's program entirely.
What the Calculator Can't Tell You
Your lender might not apply extra payments the way you expect. Some will apply them to future principal due dates rather than immediately reducing your balance. Others will hold the money in a suspense account until your next regular payment hits. This delays the interest savings by a full billing cycle, sometimes two. I've seen people think they were saving months off their loan when they were actually saving about three weeks because of application lag. Always call your servicer and ask how they handle partial payments, then factor that delay into your timeline. Refinancing mid-payoff is another minefield. If you've been making accelerated payments for five years and your rate drops, you might be tempted to refinance and start over. The new Accelerated Mortgage Payoff Calculator run will look attractive on paper. But closing costs typically run 2% to 5% of the balance. On a $200,000 loan that's $4,000 to $10,000 upfront. Plus you reset the clock. Sometimes the math works. More often it doesn't. Run the numbers with the costs included before you sign anything. If your mortgage has a prepayment penalty clause, the calculator won't warn you about it. Some older loans, especially those originated between 2005 and 2010, carry penalties that eat into your savings during the first three to five years. Check your closing documents. If there's a clause saying you pay a percentage of prepaid principal if you pay off early within a certain window, the accelerated payoff strategy changes dramatically. You might need to wait until the penalty period expires before the math makes sense.
Get the Full Details

The tool itself is free on dozens of websites. Just search Accelerated Mortgage Payoff Calculator and you'll find options from bank sites, financial blogs, and independent calculators. Pick one that lets you adjust the extra payment amount and see the updated payoff date in real time. The ones that only give you a single static number are less useful because your situation will change. Save your results, redo the calculation when rates shift or your income changes, and track the variance over time.