Understanding ASC 842 Lease Accounting in Practice
Accounting Asc 842 Example: How the Right-of-Use Model Actually Works
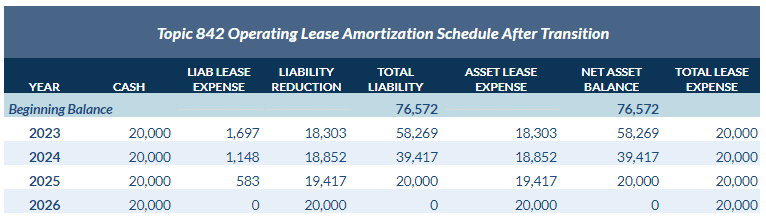
ASC 842 replaced ASC 840 for public companies starting in 2019 and for private companies in 2022. The fundamental shift was moving most leases onto the balance sheet. Before 842, operating leases sat off-balance sheet entirely. Now every lease above a certain threshold requires recognition of a right-of-use asset and a corresponding lease liability. The standard applies to any contract that conveys the right to control the use of an identified asset for a period of time in exchange for consideration. That definition is broader than most people initially assume. It includes software arrangements, infrastructure contracts, and even some service agreements that contain embedded leases. The key word is control. If the customer has the right to direct how and for what purpose the asset is used, it is a lease under 842. The basic journal entry at lease commencement looks like this. You debit right-of-use asset and credit lease liability for the present value of future lease payments. The discount rate you use matters significantly. For lessees, ASC 842 requires the rate implicit in the lease if it is readily determinable. Most of the time it is not. In practice, almost everyone uses the incremental borrowing rate. That rate depends on your credit quality, the lease term, and the economic environment at commencement. I have seen companies miss the difference between their IBR on day one and what they ended up using six months later, which created restatement work down the line.
The Measurement Problem Nobody Warns You About
The tricky part is that lease payments include more than just the stated rental amount. Fixed payments, variable payments tied to an index or rate, residual value guarantees, and exercise prices on options to purchase or terminate all factor into the calculation. If you are reasonably certain you will exercise an option, you include it in the lease term. Reasonably certain is a high bar. It means you have a significant incentive to exercise that is not merely economic convenience. I worked on a transition engagement for a mid-market logistics company a couple of years ago. They had a fleet of warehouse trailers under long-term rental agreements. The contracts had escalation clauses tied to CPI. The problem was that many of these escalations were drafted as separate service payments rather than true lease payment adjustments. Under ASC 842, the distinction determines whether you revalue the liability when the index changes. If the escalation is part of the lease consideration, you remeasure. If it is a variable non-lease component, it stays excluded from the liability and hits P&L as incurred. The workaround was straightforward but tedious. I pulled every contract, identified the payment schedule line items, and cross-referenced them against the separation guidance in ASC 842-10-15. We ended up reallocating approximately 12 percent of what they had originally classified as variable payments into the lease liability because the contractual language effectively made them fixed in substance. The adjustment increased their total lease liabilities by about $3.4 million and shifted a meaningful chunk of expense from operating to interest and amortization.
This is the kind of thing that does not show up in the quick reference guides. The standard itself is clear on paper but the real world contracts are rarely clean. You need someone who has actually read the lease documents line by line rather than relying on the finance team summary.
Get the Full Details
Operating Versus Finance Classification
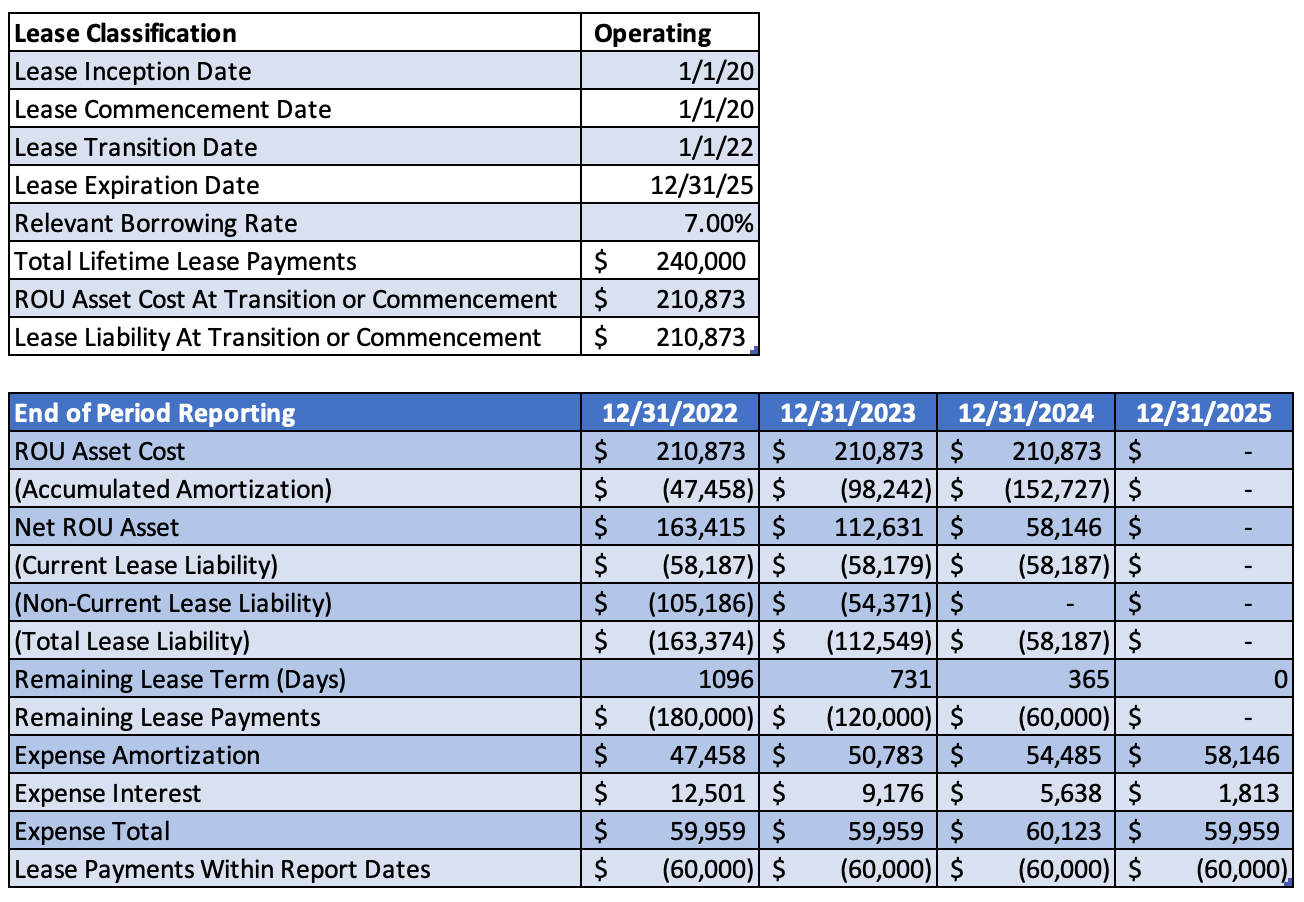
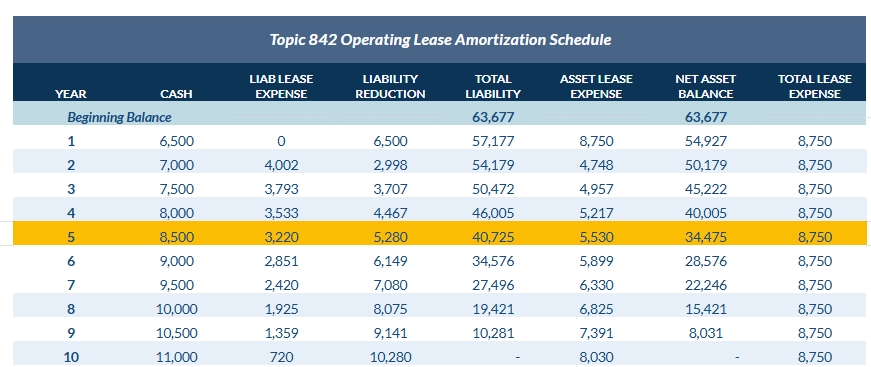
Not all leases are treated the same after recognition. The classification decision between operating and finance leases determines the pattern of expense recognition over the lease term. Finance leases front-load expense because interest is calculated on the declining liability balance while the ROU asset amortizes straight-line. Operating leases spread the total lease cost evenly across the term. The total expense over the life of the lease is the same either way. Only the timing differs. The classification criteria are the same five tests that existed under ASC 840, but with one important change. The ownership transfer and purchase option tests are now harder to fail under the new reasonable certainty language. I have seen clients classify leases as operating when a straightforward reading of the purchase option language should have triggered a finance classification. The test is whether theLessee is reasonably certain to exercise the option. If the option price is significantly below fair value at the date it becomes exercisable, that is a bright yellow flag.
Practical Implementation Issues
The biggest practical problem companies face is data collection. ASC 842 requires an inventory of every lease arrangement across the organization. Real estate, vehicles, equipment, IT hardware, even some packaging return programs. Most companies did not have a centralized register. I have seen facilities managers hold lease files in spreadsheets that were three versions behind the actual contract. The recommendation is to build a single source of truth early. A shared database with fields for commencement date, lease term, payment schedule, discount rate, and option dates will save you hundreds of hours during each reporting period. Another issue is the practical expedient for non-lease components. ASC 842 allows you to elect not to separate lease and non-lease components. This is a group-wide election. Once you make it, you apply it to all leases. The decision matters because combining the components means the entire payment stream gets discounted and recorded as a lease liability. Separating them means only the lease portion goes on the balance sheet. For companies with significant maintenance or service components bundled into their leases, the separation election often results in materially lower reported liabilities. But you cannot pick and choose. It is all or nothing. Private company relief is worth noting. Private companies get a four-year delay on adoption compared to public companies. They also have an optional practical expedient to use a single discount rate for a portfolio of leases with similar characteristics. If you manage 200 identical warehouse leases with the same terms and your IBR does not vary meaningfully between them, the portfolio approach can cut your computation time dramatically. I used this for a client with a large retail footprint. The portfolio election reduced the number of individual liability calculations from several hundred to roughly two dozen. The result was materially accurate because the variation in IBR across those leases was less than 25 basis points.
Common Pitfalls
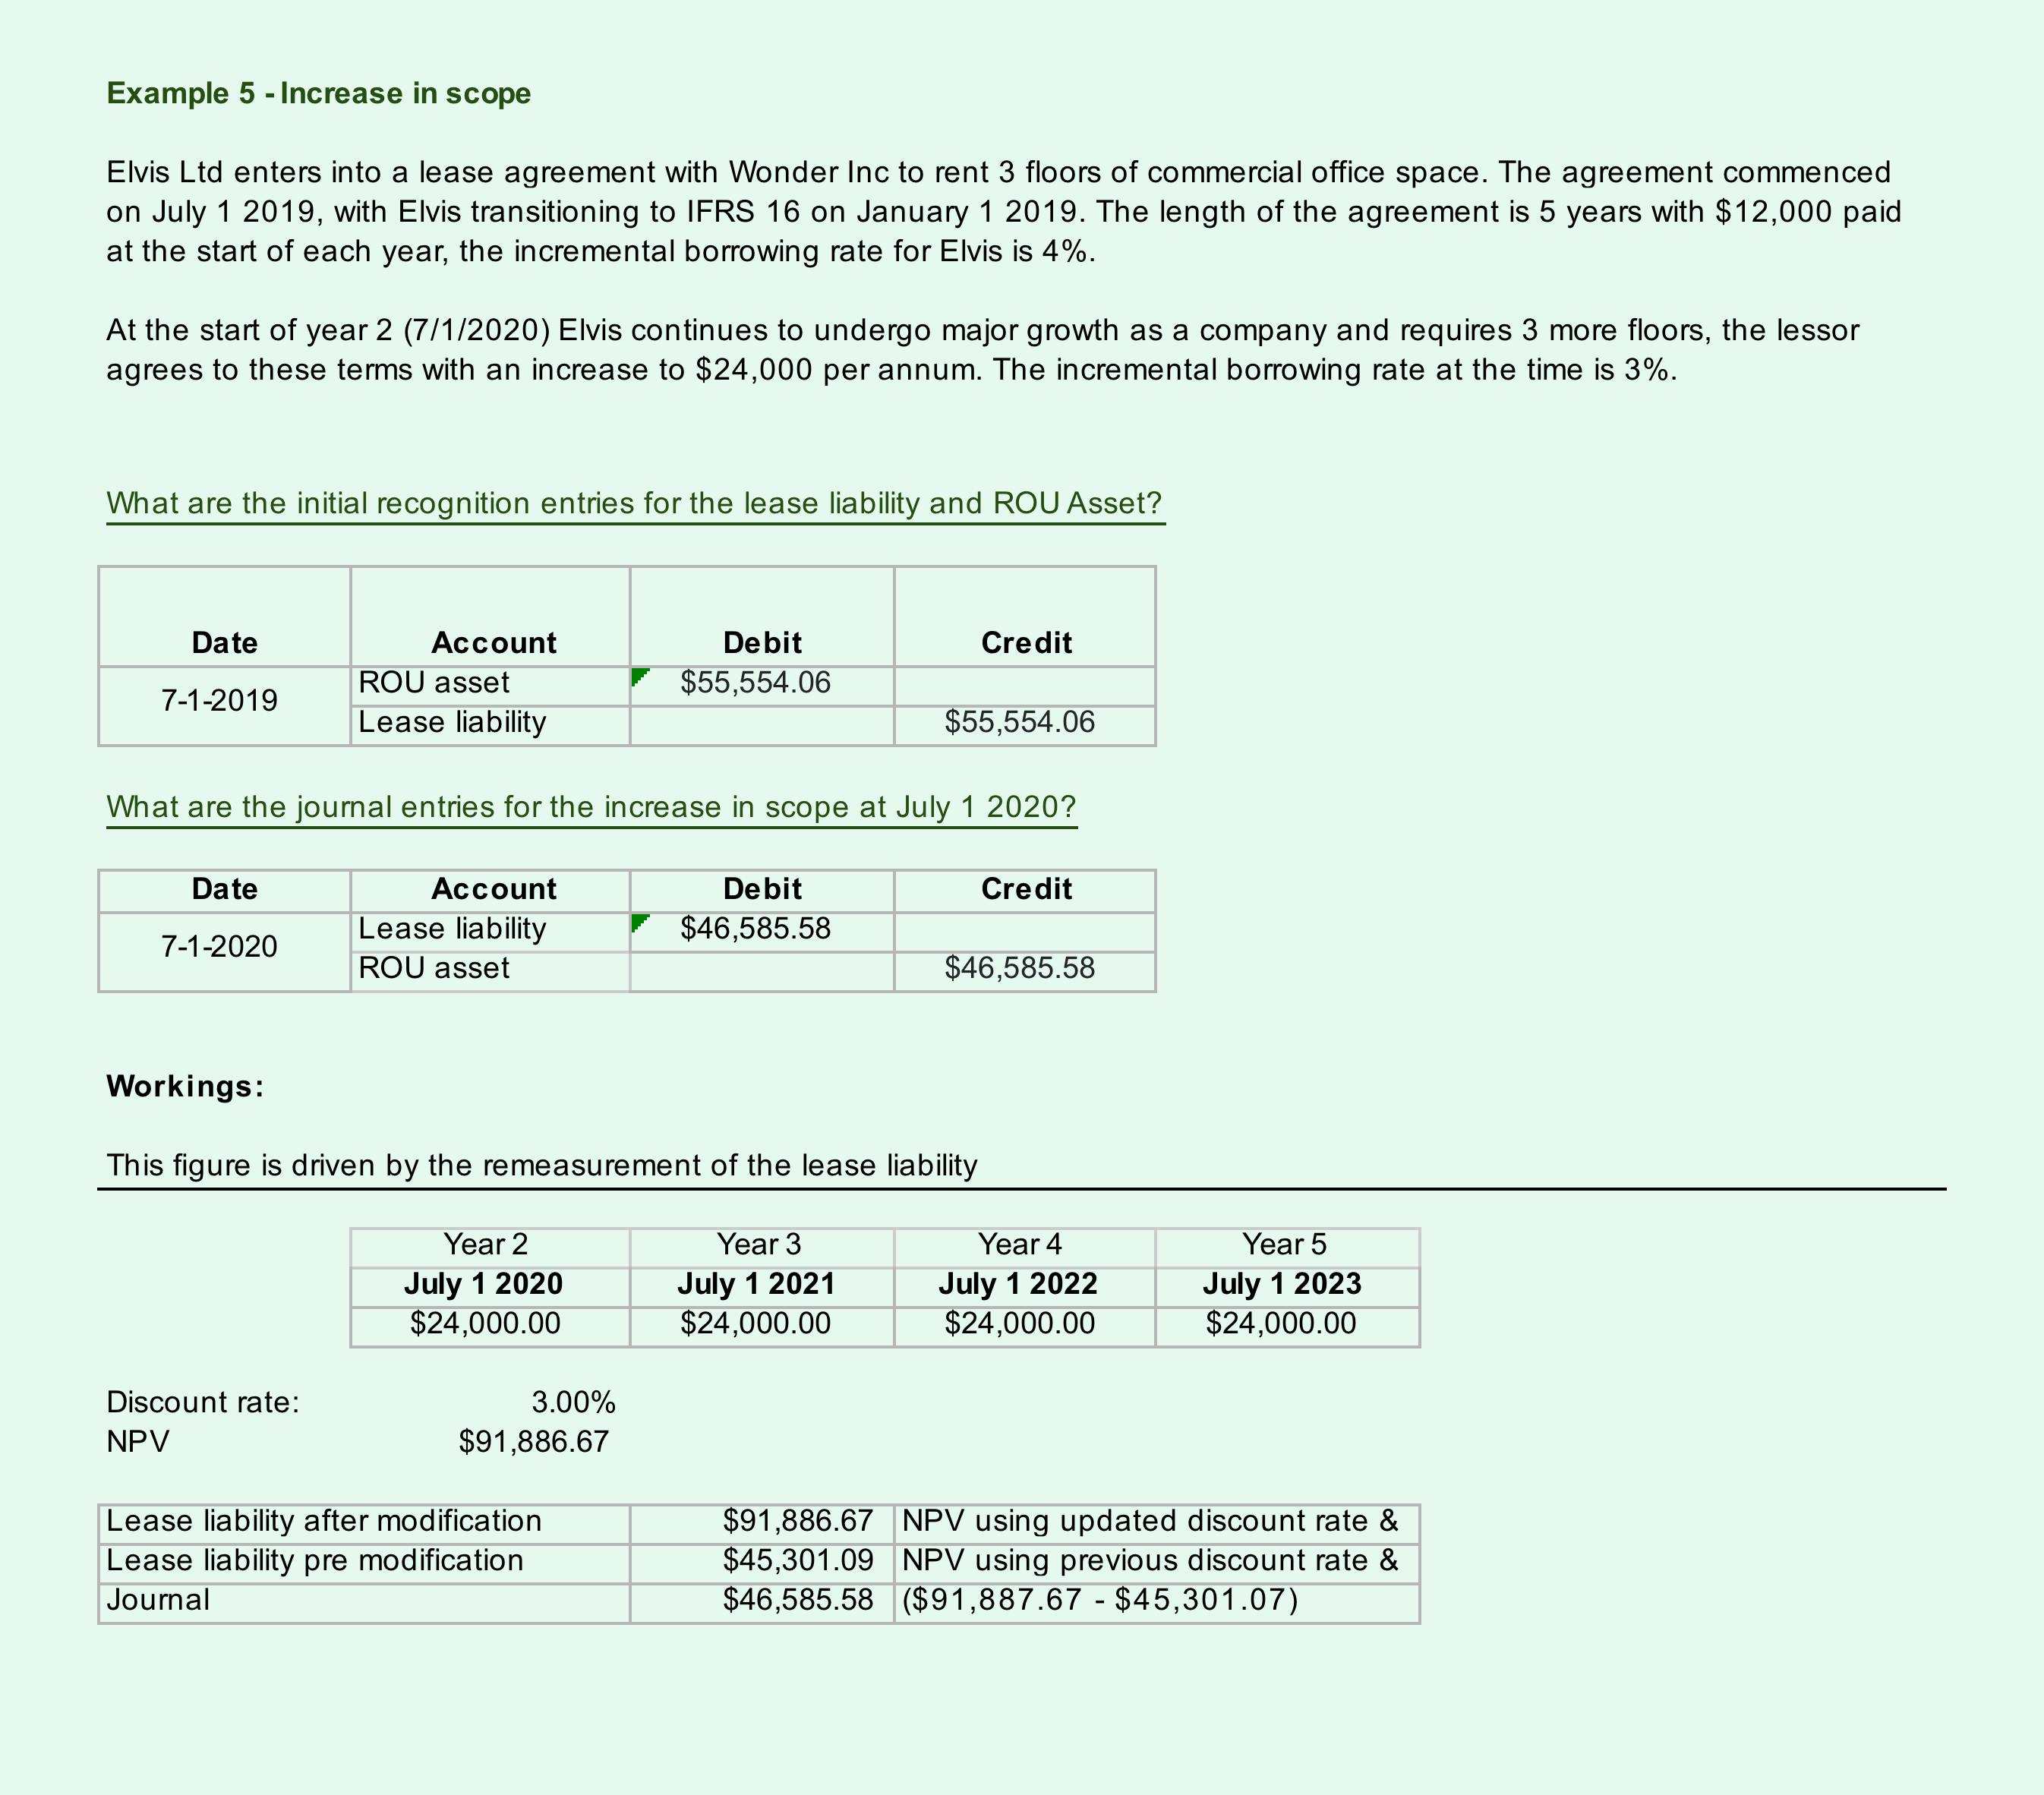
Here are mistakes I see repeatedly. First, companies forget to reassess lease terms when significant events occur. A renovation decision, a change in business strategy, or even a sublease arrangement can trigger a reassessment. The liability and ROU asset must be adjusted prospectively. Second, companies use the wrong discount rate. Some use the rate from the original negotiation instead of recalculating the IBR at each reporting date. The standard requires the rate at lease commencement to determine the liability. Subsequent changes to the discount rate do not restate the liability unless there is a modification or reassessment. Third, and this one is painful, companies omit embedded leases from their scope. A long-term cloud hosting agreement with dedicated infrastructure allocation can constitute a lease if the customer controls the use of that specific hardware. I encountered a SaaS contract where the vendor reserved the right to migrate the customer to different servers at any time. The right of substitution was substantive because the vendor could practically replace the asset without customer consent and would benefit economically from doing so. That meant there was no identified asset, and therefore no lease. The initial review had incorrectly classified it as a service contract. Correcting that required pulling the technical architecture documentation and talking to the engineering team, not just reading the commercial terms.
Where ASC 842 Falls Short
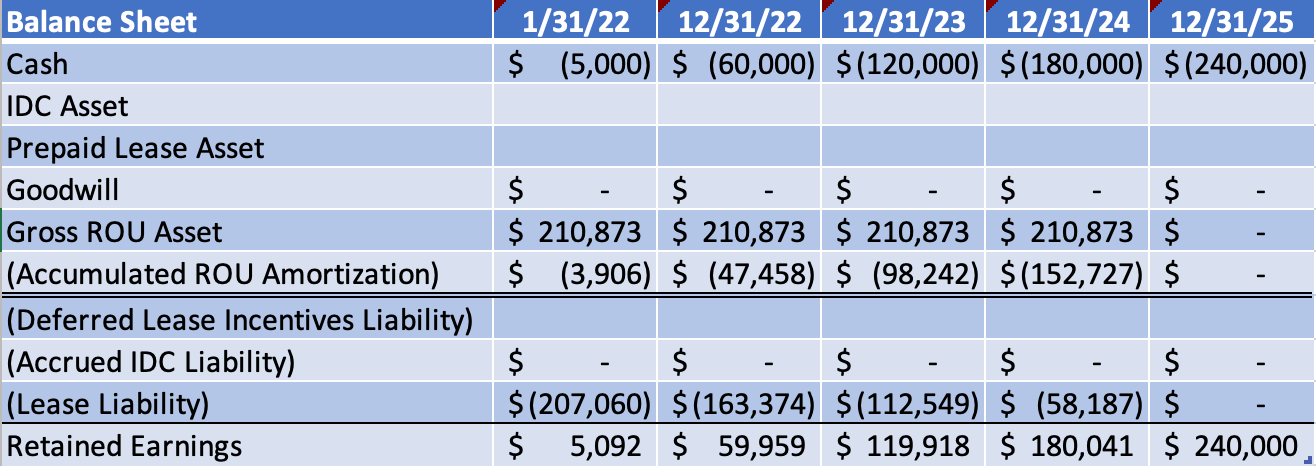
The standard has genuine limitations. The biggest is that it does not address all forms of right-to-use arrangements clearly. Contract manufacturing, data center agreements, and certain franchise arrangements sit in a gray area that the FASB has not fully resolved. The Emerging Issues Task Force has issued some guidance, but the application is still fact-intensive and often requires management judgment that two different preparers could resolve differently. Another limitation is cost. For smaller entities with complex lease portfolios, the compliance burden is disproportionate. The data requirements, the systems investment, and the ongoing reassessment obligations can consume significant resources. If your organization has fewer than 50 active leases with simple terms, the cost of building a robust 842 compliance process may exceed the benefit of perfect precision. In those cases, a simplified portfolio approach with documented judgment is usually reasonable. The SEC and auditors generally accept it as long as the methodology is consistently applied and the conclusions are defensible. For public companies, the disclosure requirements are extensive. You need to provide quantitative and qualitative information about leasing arrangements, maturity analyses, supplemental cash flow disclosures, and a reconciliation of beginning and ending balances. The maturity table alone typically runs two pages. Companies that treat the disclosure as boilerplate often get questions from auditors because the numbers do not reconcile cleanly to the balance sheet line items. Always verify that the rollforward in the notes ties exactly to the financial statement numbers before you finalize the package.