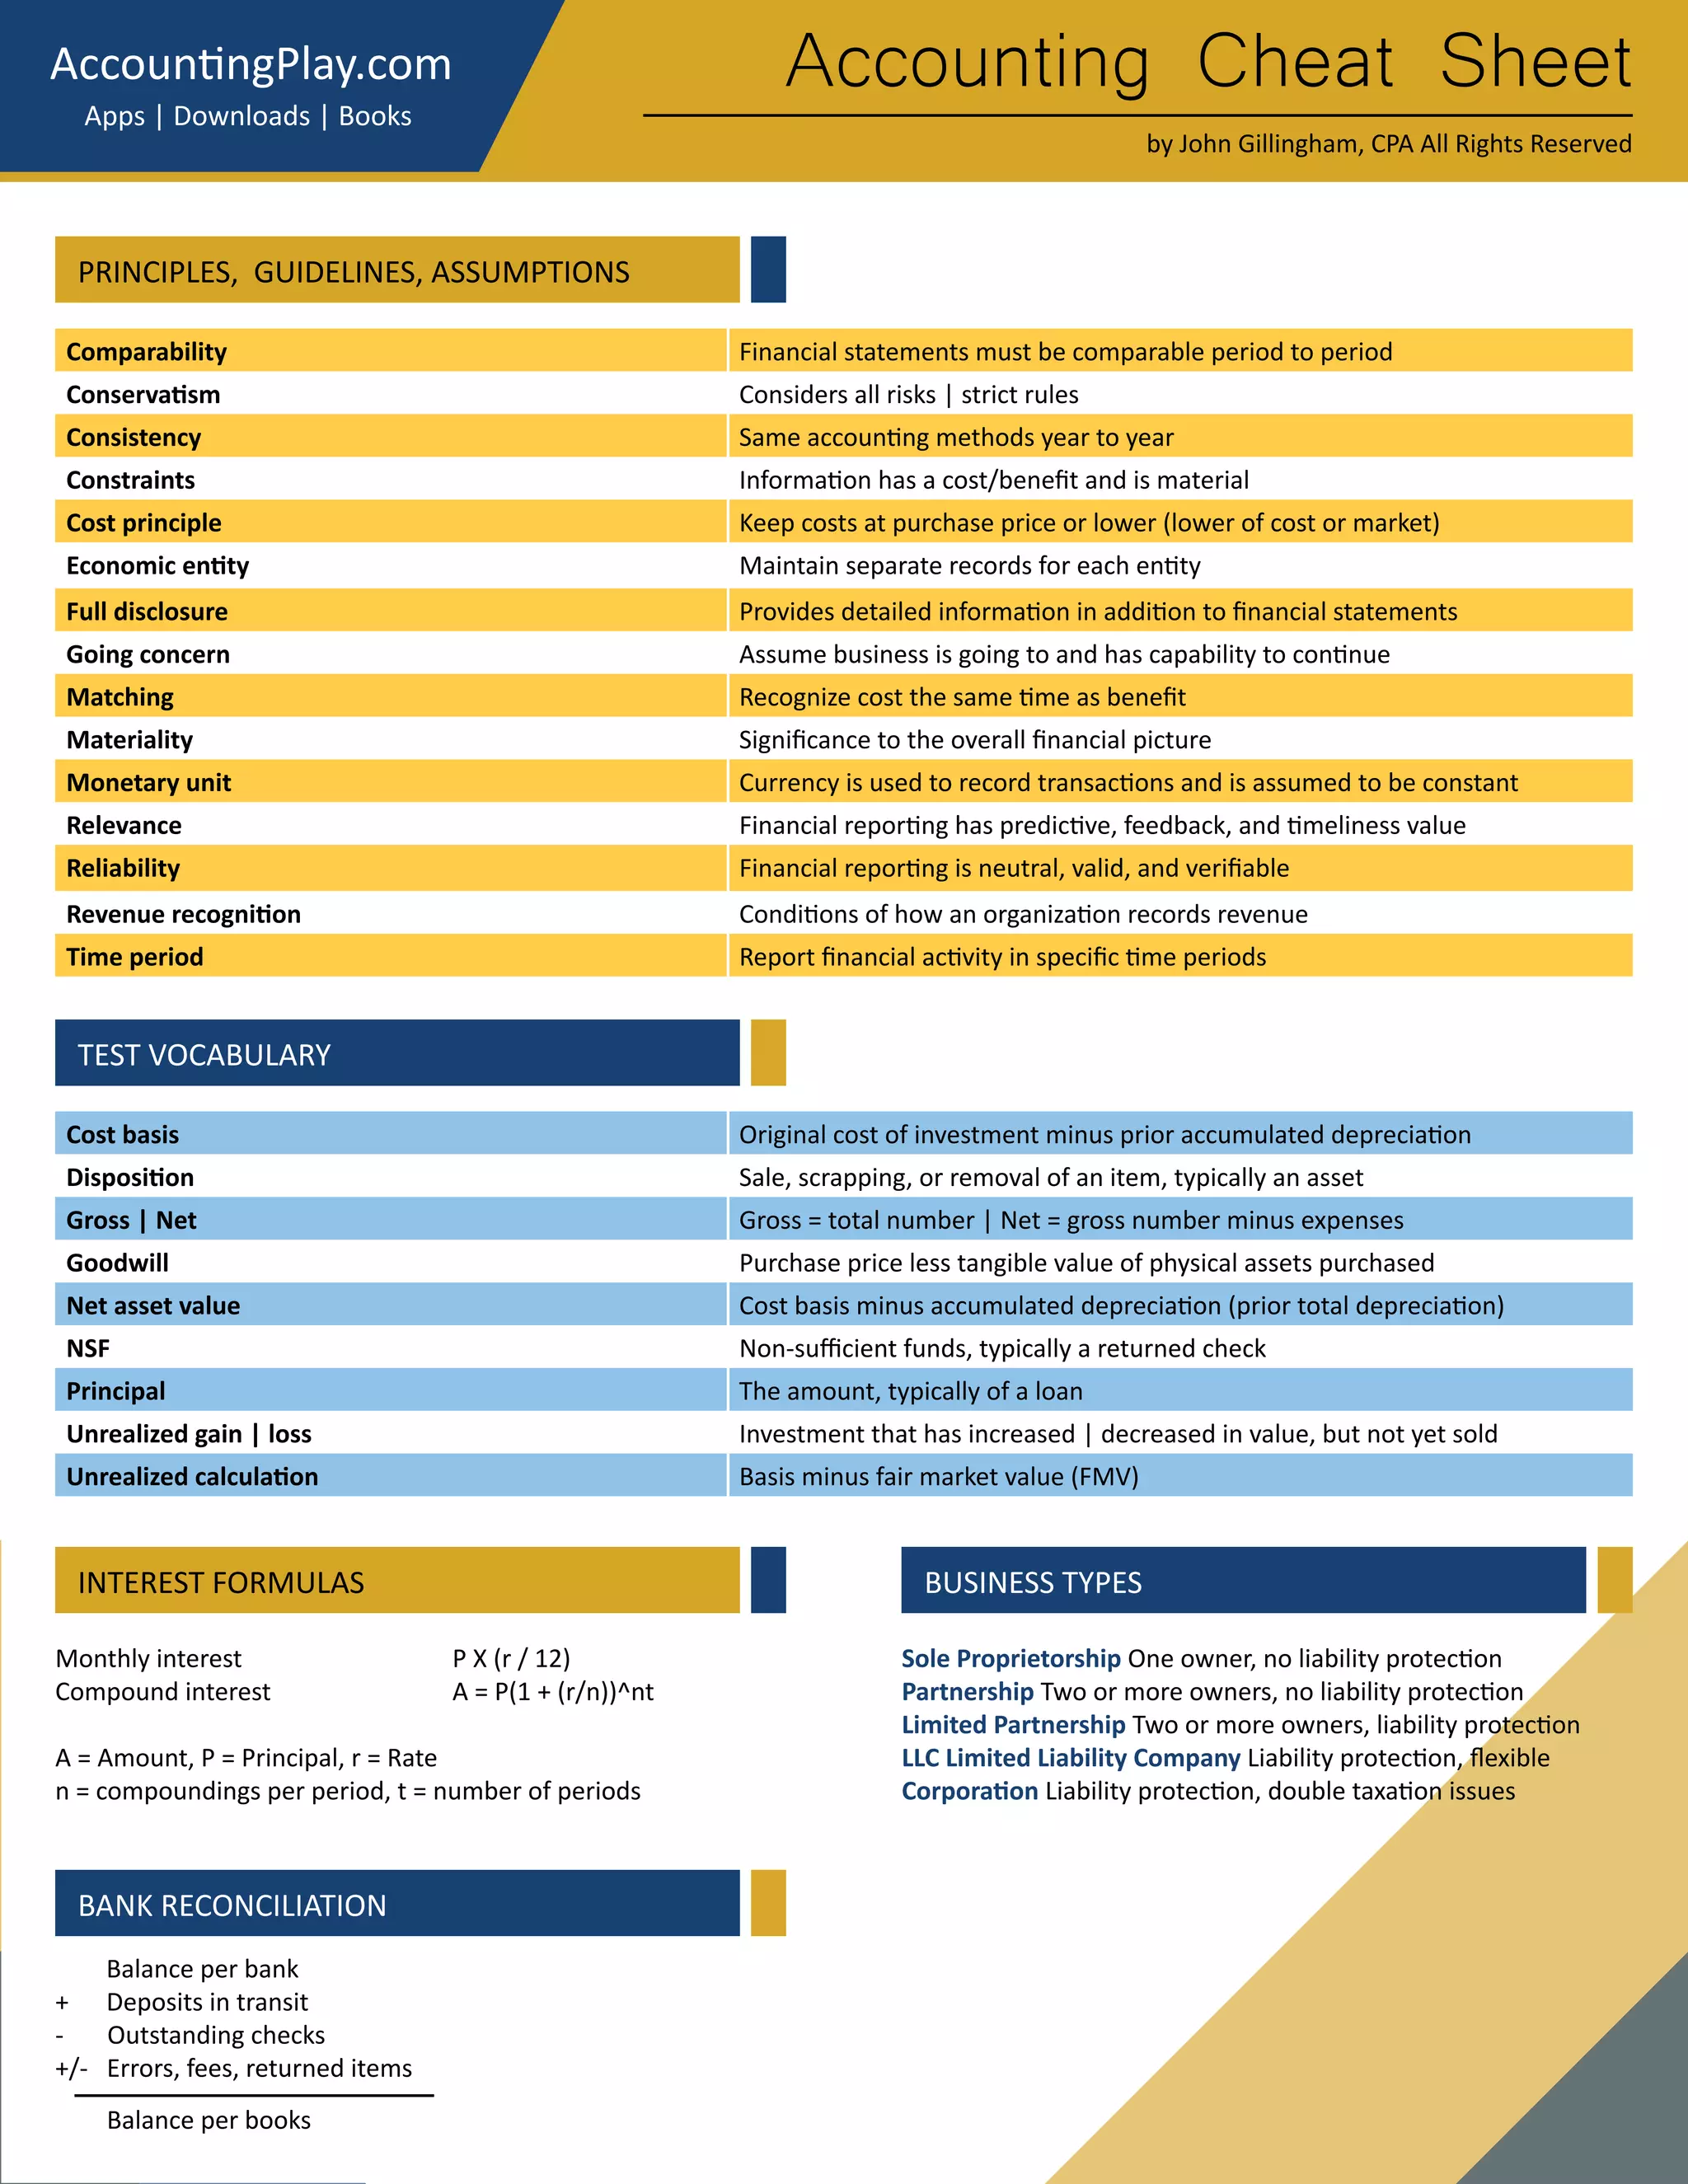
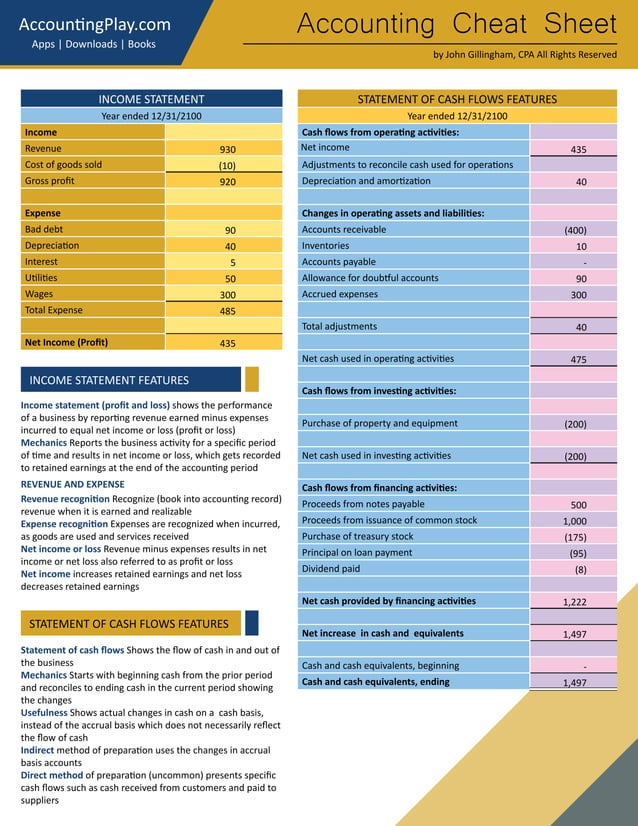
What This Thing Actually Is
Most people grab an Accounting Cheat Sheet Weekly as a quick reference during tax season, which is about as useful as a map for a region you're already driving through. It's a condensed accounting reference document that cycles through different topics each week — balances, journal entries, depreciation methods, revenue recognition rules, the usual things that slip your mind when you're knee-deep in month-end close. Think of it less as a learning tool and more as a tactical lookup sheet. The resource itself isn't something I can link to directly since there are a dozen variations floating around forums, Reddit threads, and accounting education sites, and most of them are just repackaged PDFs with no attribution. What I'd suggest is searching for the latest version that matches your jurisdiction and accounting framework — US GAAP vs IFRS makes a real difference here, and mixing them up will bite you. A properly organized sheet should be print-friendly on a single A4 page front and back. If it's five pages long, it's not a cheat sheet, it's a textbook that forgot to cut the fat. I keep one at my desk and reference it constantly during close periods. The one I use now was assembled from several sources over the past three years and has evolved into something I actually trust, which is more than I can say for most of these things.
How to Actually Use It Without Wasting Time
The biggest mistake I see people make is treating it as a study guide instead of a reference. You don't read it cover to cover. You open it to the section relevant to whatever you're doing right now and pull the specific formula or rule you need. I spent about two weeks trying to memorize the amortization schedules from a different version I found online before I realized I was solving the wrong problem entirely — you're supposed to know the underlying concepts cold and use the sheet only for the mechanical parts you'd otherwise have to look up in a full standard. That distinction alone cut my close process time significantly. Here's the workflow I settled on: keep the sheet open in one tab while you're working, and only switch away if you need to reference something outside its scope. When you encounter a situation not covered — and they will be, because no sheet covers everything — that's when you pause and either document the gap or add it to your own personal version. This is how the thing stays useful. Static sheets rot. Yours should grow.
The Specific Problem I Ran Into
Last quarter, I was reconciling a lease accounting entry under ASC 842 and realized the cheat sheet I'd been relying on had the discount rate methodology backwards for operating versus finance leases. It listed them interchangeably, which is a non-starter when the difference affects your entire lease liability calculation. Instead of spending an afternoon reworking every entry, I pulled the original standard text and corrected the relevant section. Now my version includes a small footnote on every lease-related line that calls out which classification applies and what rate basis to use. Took me maybe twenty minutes to fix. Saved me from making a material error in a set of financials. This is why you should never treat any published version as authoritative without checking it against the current standard. These sheets circulate with errors, and nobody verifies them before reposting. I've caught three separate mistakes in the last year across different sources — two on tax depreciation tables and one on foreign currency translation mechanics. All of them would have cost real money if I hadn't spotted them.
Get the Full Details

What Most Sheets Get Wrong
The first thing to watch for is outdated standards. Several versions I've seen still reference ASC 606 revenue recognition language that was superseded by the amendments finalized in 2023. Another common issue is mixing perpetual and periodic inventory methods in the same section without noting which applies to which formula. That confusion shows up repeatedly in exam settings and in real work when someone applies a perpetual method formula to a periodic system and the COGS number comes out wrong. A second problem is the presentation of the accounting equation. Most sheets show Assets = Liabilities + Equity and call it done. That's sufficient for a class but insufficient for actual work. In practice, you also need to track the flow through the income statement into retained earnings, and the comprehensive income layer that sits above net income. My version includes a small flow diagram showing where each account category feeds and what drives the period-over-period movement. That diagram alone has saved me from misclassifying items several times.
Building Your Own Version
Start with whatever published version you can find, then immediately begin marking up your copy. Don't buy into the idea that you need to create something from scratch. The value isn't in the originality, it's in the corrections and additions you make. I use a two-column format for my personal version — the standard formula or rule on the left, and notes on exceptions, common misapplications, and recent standard changes on the right. When I hit a topic not covered, I add it to the appropriate section rather than creating a separate reference. The sheet stays focused and easier to navigate. If your sheet grows beyond two sides of A4, cut it down. Remove anything you already know by heart and that you don't actually reference. The best cheat sheets are the ones that force you to think about what you need versus what sounds important. I've seen people fill pages with formulas they've never actually needed and skip the three rules that would've mattered most on their last assignment.
Where It Falls Apart
No cheat sheet handles complex consolidations well. If you're dealing with multi-entity structures, foreign subsidiaries, or intercompany eliminations, the sheet becomes a source of false confidence — it gives you simplified formulas that don't account for the edge cases that actually show up in real consolidation packages. In those situations, the sheet is better left in the drawer and you go straight to the full standard or a professional reference. I learned that after a particularly rough fiscal year end when I tried to apply a simplified intercompany elimination shortcut and had to redo a significant portion of the work. The other limitation is temporal. Standards change. Tax codes change. A sheet from two years ago is likely already slightly behind, and older versions get worse fast. Whatever version you're using, verify the date on it. If it doesn't have one, that's a red flag. My current version was last updated in January and explicitly notes which standards it was cross-referenced against and when. If you want something more comprehensive for complex scenarios, the actual FASB or IFRS standards are the only reliable source, though they're not exactly concise. There are also commercial tools like CCH or Thomson Reuters that handle this better but require subscriptions. For most small to mid-size engagements and individual practitioners, a well-maintained personal cheat sheet plus the habit of double-checking anything that feels off is the most practical approach available.