Setting Up a Weekly Accounting Checklist That Doesn't Fall Apart After Three Weeks
The most common mistake I see isn't that people don't have a checklist at all. It's that they build one that's too detailed and then abandon it entirely because it takes three hours to complete. A weekly accounting checklist needs to be something you can actually finish in 45 minutes or less, consistently, without skipping items when you're behind on other work. If it's longer than that, you've built a month-end close procedure, not a weekly checklist. It's a recurring set of accounting tasks performed every business week—typically Friday afternoon or Monday morning—designed to keep your books within a day or two of real-time accuracy instead of letting them pile up until month-end. The goal isn't perfection. The goal is catching discrepancies while they're small enough to fix in fifteen minutes instead of requiring a multi-hour investigation six weeks later. A properly maintained weekly process gives you a current trial balance on any given day, not just after you've spent the last two days of the month desperately trying to record receipts from three weeks ago. When you know your cash position from Friday's reconciliation, you're making decisions with actual numbers instead of hoping the bank balance you checked on Tuesday still roughly matches reality.
How to Build One Without Creating Something You'll Ignore
Start by listing every reconciliation task you currently do at month-end. Then strip out anything that genuinely doesn't need weekly attention. Bank accounts usually need it every week. Credit cards absolutely need it every week. Subscriptions and recurring payments can often go biweekly. Fixed asset additions and depreciation are monthly at most. Sales tax collections vary by jurisdiction but weekly tracking prevents surprises when the filing deadline hits. Build the actual checklist document in the tool you already use daily. If you're in QuickBooks, create it as a memorized report or a custom checklist within the application. If you're in Xero, use their built-in checklist feature or maintain it in a shared spreadsheet. The moment you force yourself to look in a separate document to do the work, you'll skip steps. The checklist and the work should live in the same interface. I once worked with a client whose checklist was a beautifully formatted PDF stored on their shared drive. They printed it every Friday, checked boxes with a pen, and filed it in a binder. They went eight months without anyone actually reviewing whether the work was done correctly. The checklist existed as an artifact, not as a functional tool. Switching to a Google Sheet they could edit in real time changed everything. Now the controller can see who completed what and when, and flagged items turn red automatically if left unchecked for two weeks.
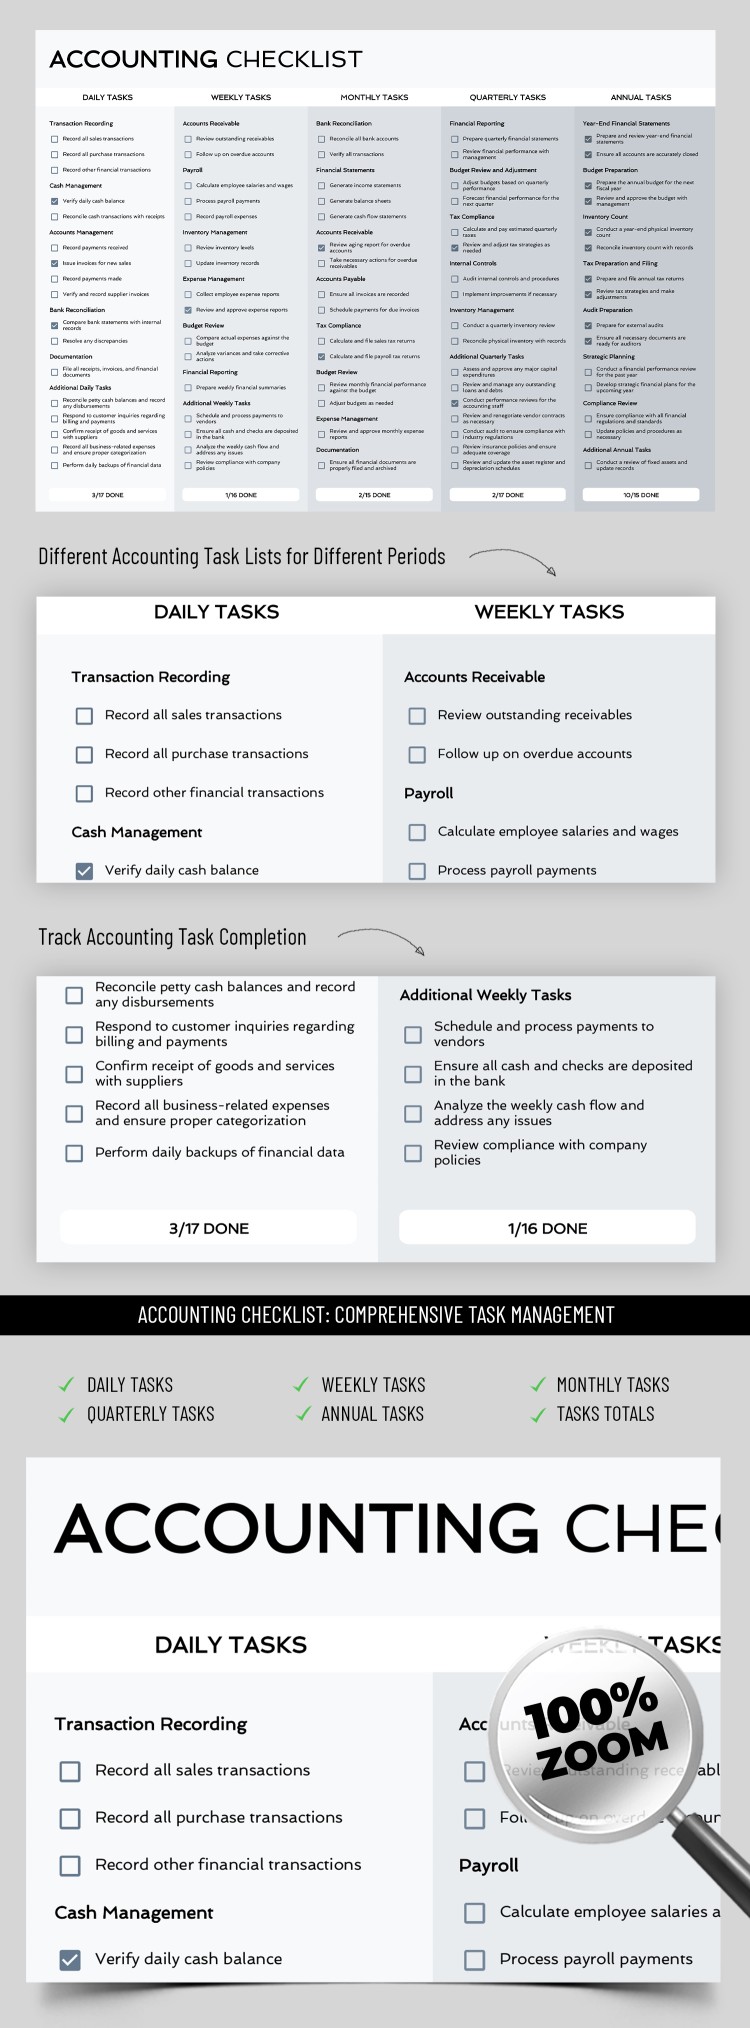
Weekly Accounting Checklist Template Structure
1. Bank and Cash Reconciliation
Pull the prior Friday's closing balance forward. Reconcile every checking, savings, and credit card account. Match every transaction on the bank statement to your books. Note any uncleared items older than fourteen days. This single step catches roughly eighty percent of accounting errors before they compound. 2. Accounts Receivable Review
Pull the A/R aging report. Identify invoices older than your standard terms by more than five days. Send follow-up notices to customers who haven't paid on time. Verify that any credits or write-offs have proper documentation attached. Leave no invoice sitting in "sent" limbo without someone owning the next step. 3. Accounts Payable Review
Pull the A/P aging report. Confirm all vendor invoices received during the week are entered. Match invoices to purchase orders or receiving documents where applicable. Schedule payments due next week and ensure sufficient cash is reserved. This prevents the embarrassment of a missed payment to a vendor who's been patient three times already.
Get the Full Details

4. Payroll Verification
If you run payroll weekly or biweekly, verify the total matches your records. Check for any off-cycle payments, corrections, or retroactive adjustments. Confirm tax deposits are scheduled or paid. A missed quarterly payroll tax deposit is one of the fastest ways to trigger state penalties that snowball far beyond what you'd expect from a simple oversight. 5. Revenue and Expense Cut-off Check
Review the past week's transactions for anything that belongs in a different period. If you shipped product on Thursday but invoiced on Monday of the following week, that revenue might be recorded in the wrong period depending on your accrual method. Small timing differences like this accumulate quietly and distort your profit margins for the month. 6. Credit Card and Subscription Audit
Run through every charge on your business credit cards. Flag anything unfamiliar. Review subscription services—cancel what you're not using. I found a $299/month software license that had auto-renewed because someone clicked "continue" during onboarding two years ago. It wasn't in use, nobody remembered it, and it showed up on the weekly review simply because we were looking.
7. Tax Liability Snapshot
Check your sales tax payable and payroll tax payable accounts. Are the balances moving in the right direction? If you're approaching a filing threshold, flag it here instead of discovering it the Sunday night before the deadline. Note: this step works best when paired with a calendar reminder system that triggers thirty days before any major tax filing date.
Edge Cases That Break Most Weekly Checklists
Multi-entity businesses create the most headaches. If you run separate legal entities orDBAs with shared bank accounts, reconciling becomes a mapping exercise rather than a simple balance check. I spent an entire Friday in 2021 tracing intercompany transfers between two LLCs that used the same physical bank account. The bank statement showed thirty transactions that appeared in one entity's books but not the other's. The root cause was a joint operating account where one entity paid vendors directly and the other reimbursed without recording the transaction on both sides. We solved it by creating a shared clearing account that both entities posted to, so every withdrawal automatically appeared in both sets of books. It took a to set up and five minutes per week to maintain afterward. Revenue recognition timing is another quiet killer. If you bill monthly subscriptions upfront but recognize revenue weekly, your deferral schedule has to be maintained separately from your reconciliation work. I've seen businesses treat these as the same task and miss a full week of revenue deferrals because the invoice was paid but the service hadn't been delivered yet. The fix is simple: maintain a separate deferred revenue schedule that updates automatically when invoices are created, and verify it against your general ledger each week. The verification should take five minutes if the automation is working correctly.

Common Pitfalls and Why They Keep Happening
Pitfall 1: Including too many monthly tasks in a weekly list. Depreciation entries, year-to-date tax summaries, and full financial statement reviews belong in a monthly close checklist, not a weekly one. Mixing the timelines creates decision fatigue. Every Friday you're asking yourself whether this is a weekly task or a monthly one, and eventually you just skip it. Keep the lists separate. Use a master calendar that clearly marks which tasks belong to which cadence. Pitfall 2: Not establishing a consistent execution window. "Do it sometime during the week" is not a plan. Pick a specific time block—Friday 2:00 to 3:00 PM, for example—and treat it like a standing meeting that cannot be canceled. If you move it around, you'll always find a reason to postpone it. The psychological commitment of a fixed time slot matters more than the actual hour you choose. Pitfall 3: Skipping the review step after completing the checklist. Completing the tasks and then never looking at the results is worse than not having a checklist at all, because it creates false confidence. Someone needs to spot-check the work monthly. Pull a random week from the previous month and verify the reconciliations were done correctly. This usually takes twenty minutes and will surface process gaps faster than any amount of training.
Practical Setup: Week One Implementation Guide
Don't try to implement everything at once. Start with bank and credit card reconciliation only. Do this every week for two weeks. Once that's habitual, add accounts receivable review. Add accounts payable the following week. Continue adding components until your full checklist is operational. Each addition should feel effortless before you introduce the next one. Rushing this process is the single most common reason implementations fail within the first month. Choose your measurement metrics early. Track completion rate—what percentage of weeks did you finish the full checklist on time? Track error discovery rate—how many discrepancies did you catch during weekly reviews versus during month-end close? These two numbers will tell you whether your process is actually improving or just feeling productive.
The Realistic Downsides Nobody Mentions
A weekly checklist will not catch fraud on its own. I reviewed a case where an employee diverted $47,000 over eleven months by creating fake vendor invoices. The weekly checklists were being completed on time. The reconciliations balanced. The problem was that the checklist never included verifying new vendors against W-9 forms and purchase order documentation before payment was issued. Adding a vendor verification step would have stopped this in the first month. But no standard checklist includes it unless you specifically design one that does. The process also requires initial overhead that smaller businesses sometimes can't justify. Setting up automated bank feeds, configuring recurring transaction rules, and building template reports takes time. For a business with one bank account and no employees, a simple Friday review of bank statements and invoice status may be sufficient. A formal weekly checklist is overkill if your transaction volume is below roughly fifty entries per week across all accounts. In those cases, a streamlined three-item review is more appropriate than a full structured checklist. Certain industries face structural limitations. Seasonal businesses with concentrated revenue periods will find that a uniform weekly checklist becomes meaningless during quiet months when there's barely anything to reconcile. Consider adjusting the checklist frequency rather than abandoning it entirely—switch to biweekly during low seasons and return to weekly when volume increases. The structure stays the same; only the cadence changes.
Downloadable Template and Resources
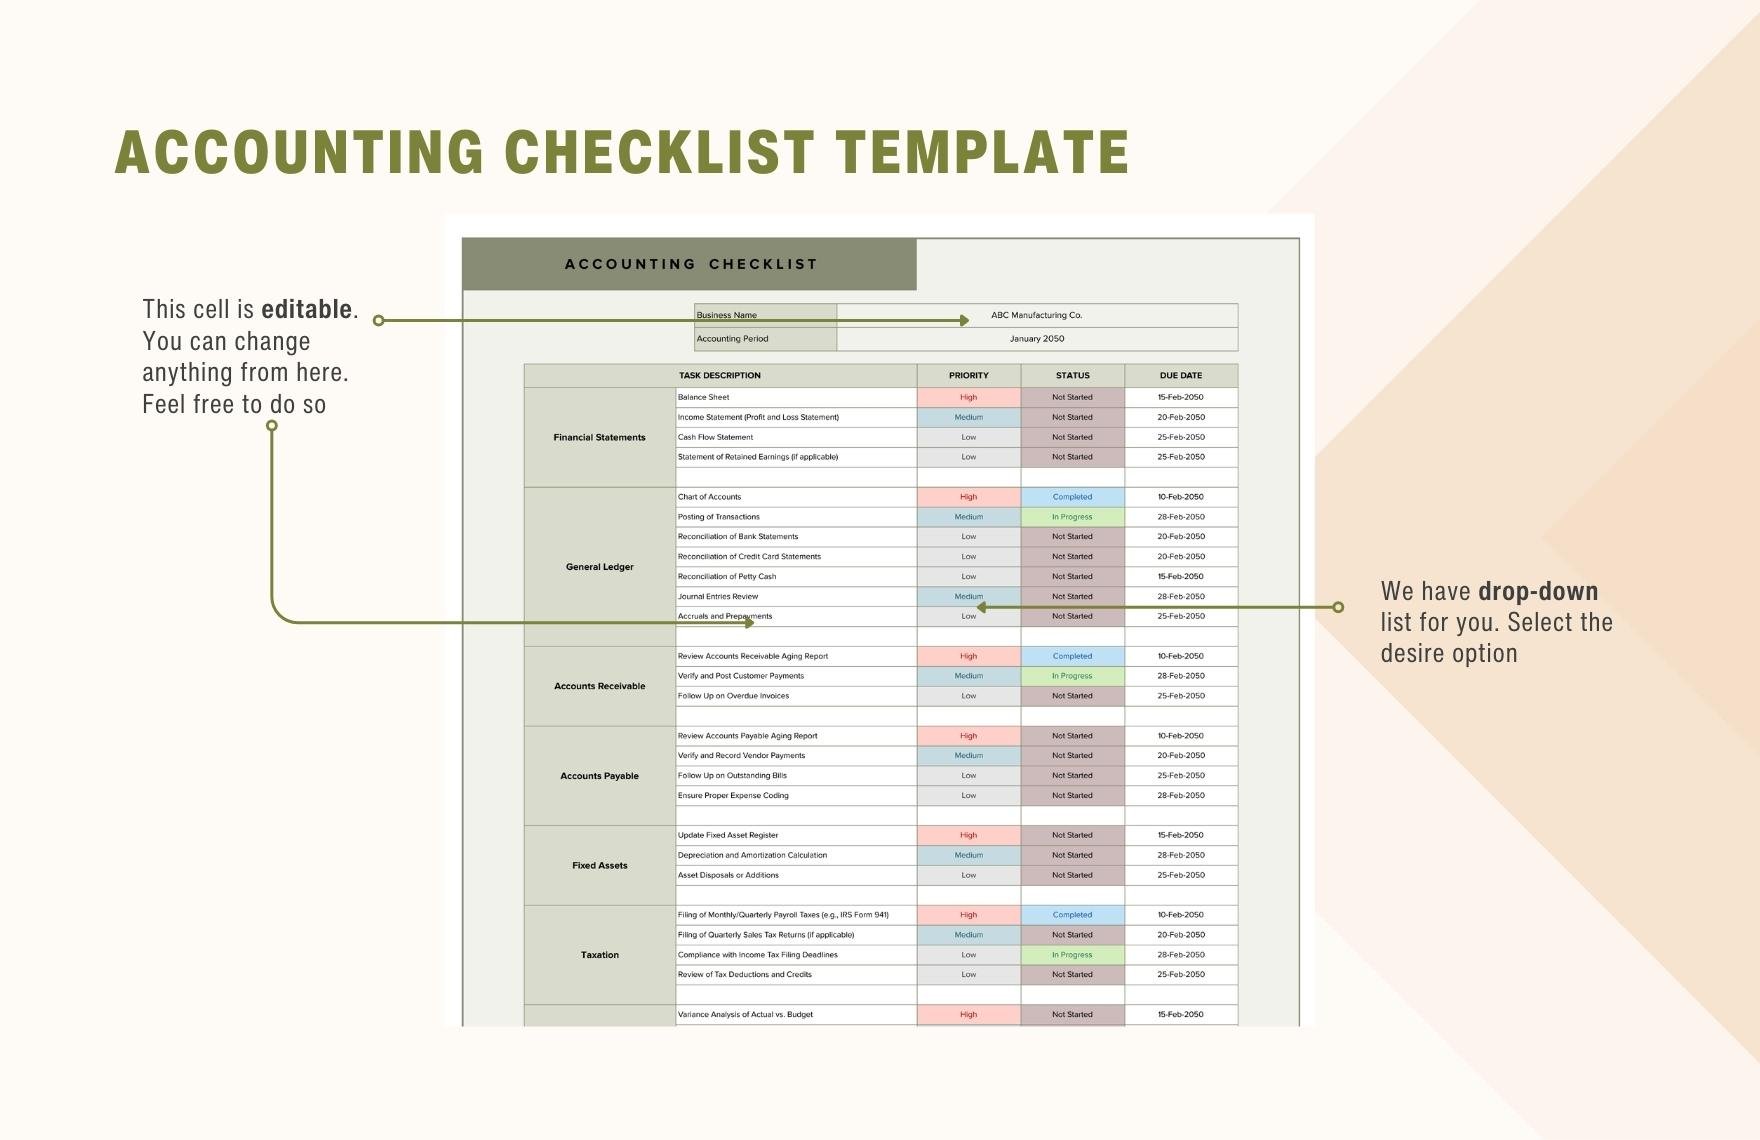
A properly formatted template is included below. It covers all seven core components listed earlier with space for notes and action items. Save it to your accounting platform or shared drive and customize it for your specific chart of accounts and filing requirements. Every business adjusts these items slightly—sales tax jurisdictions differ, payroll frequencies differ, and subscription audit depth depends on how many recurring charges you manage. The template is a starting point, not a final product. If you're using QuickBooks Online, you can import this structure directly into the checklists feature under the Gear icon. Xero users can replicate it using the Built-in Checklist module. For spreadsheet-based workflows, a well-formatted Google Sheet with conditional formatting that turns items red after seven days uncompleted works better than most purchased templates because you control the logic and can modify it without upgrading. The spreadsheet version I use internally includes columns for completion date, reviewer initials, discrepancy flag, and resolution notes. It's basic but it creates an audit trail that makes month-end reviews significantly faster. If someone flagged an item three weeks ago and never resolved it, you can see that immediately instead of rediscovering it fresh during close.
Final Notes on Sustaining the Process
Expect resistance from anyone who sees the weekly review as redundant with month-end close. They're not wrong—there is overlap. But the difference is timing. Catching a missing $340 expense in week three means you adjust it over four remaining weeks of activity. Catching it in month-end means you adjust twelve weeks of reported numbers retroactively. The math on why this matters is straightforward even if the psychological resistance to extra weekly work feels abstract to someone accustomed to a different rhythm. Assign ownership clearly. A checklist that's everyone's responsibility is nobody's responsibility. One person completes the work. One person reviews it monthly. Two people and clear roles prevent the assumption that the other person already handled a step. Revisit the checklist itself every quarter. Remove items you haven't touched in ninety days. Add items you discovered were necessary through actual use. A checklist that never changes is either perfectly designed—which is extraordinarily rare—or it hasn't been challenged by real operating conditions yet. Both scenarios should prompt a review, just for different reasons.