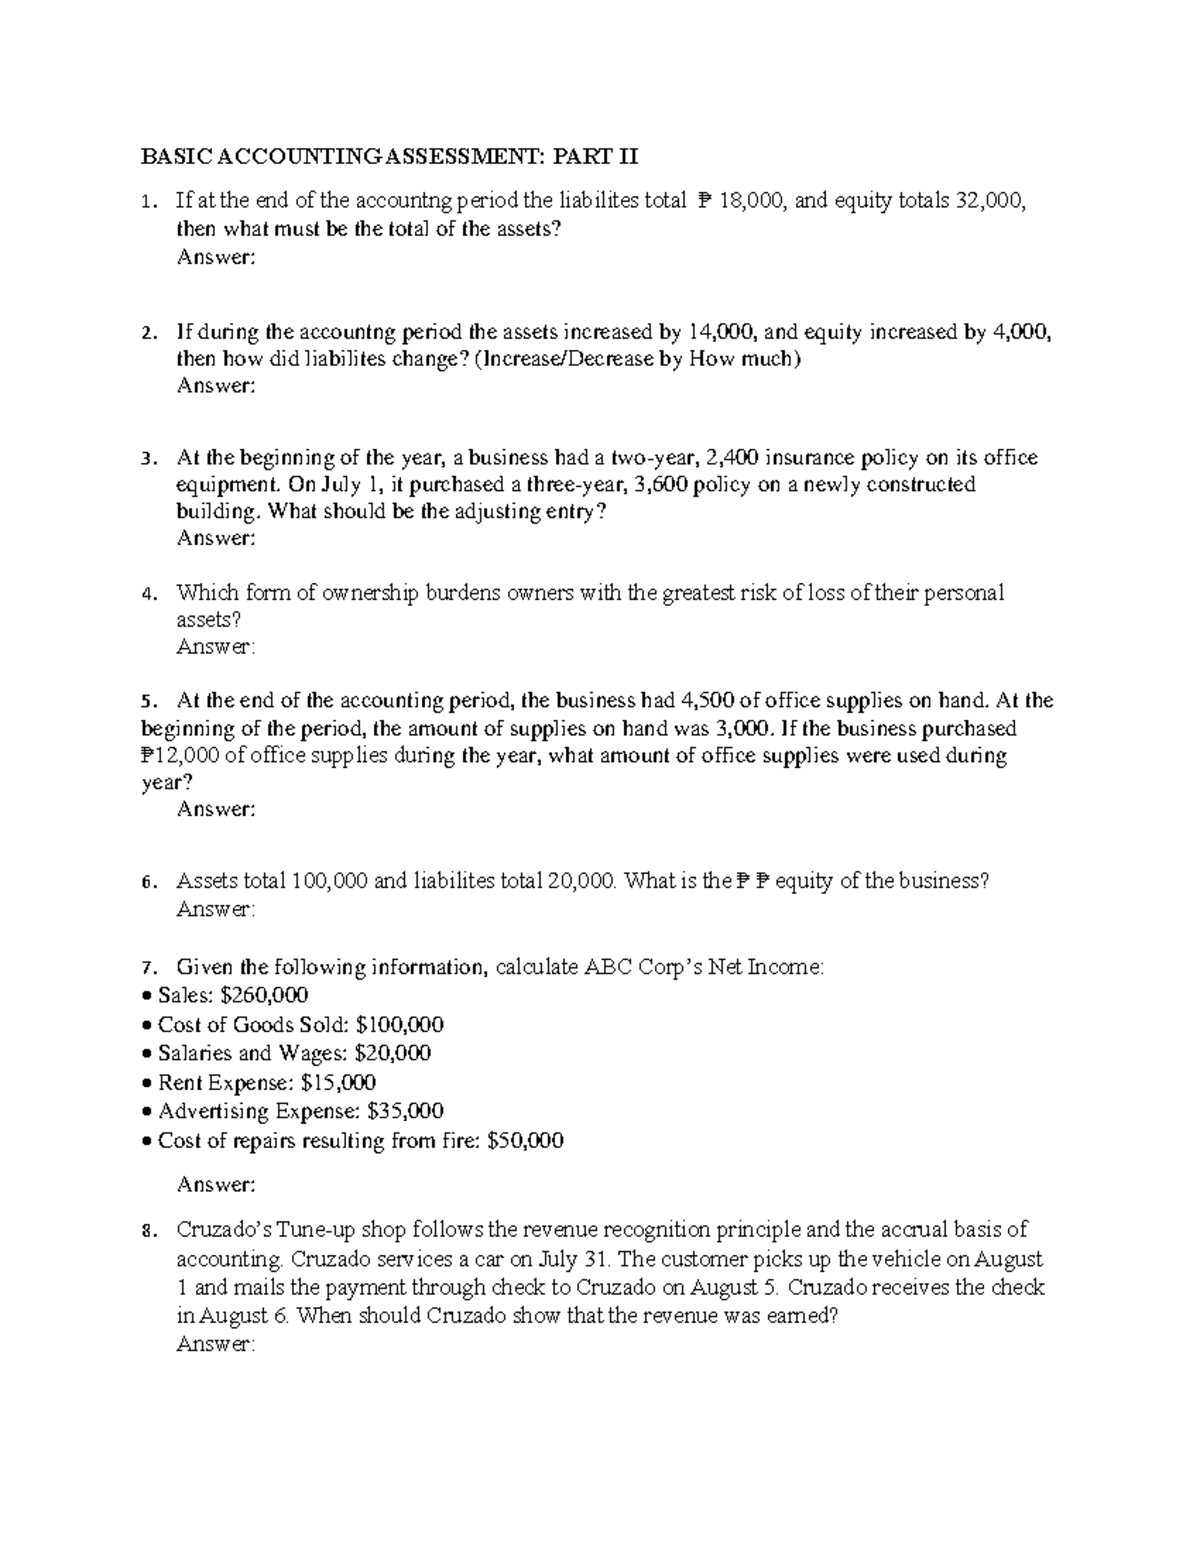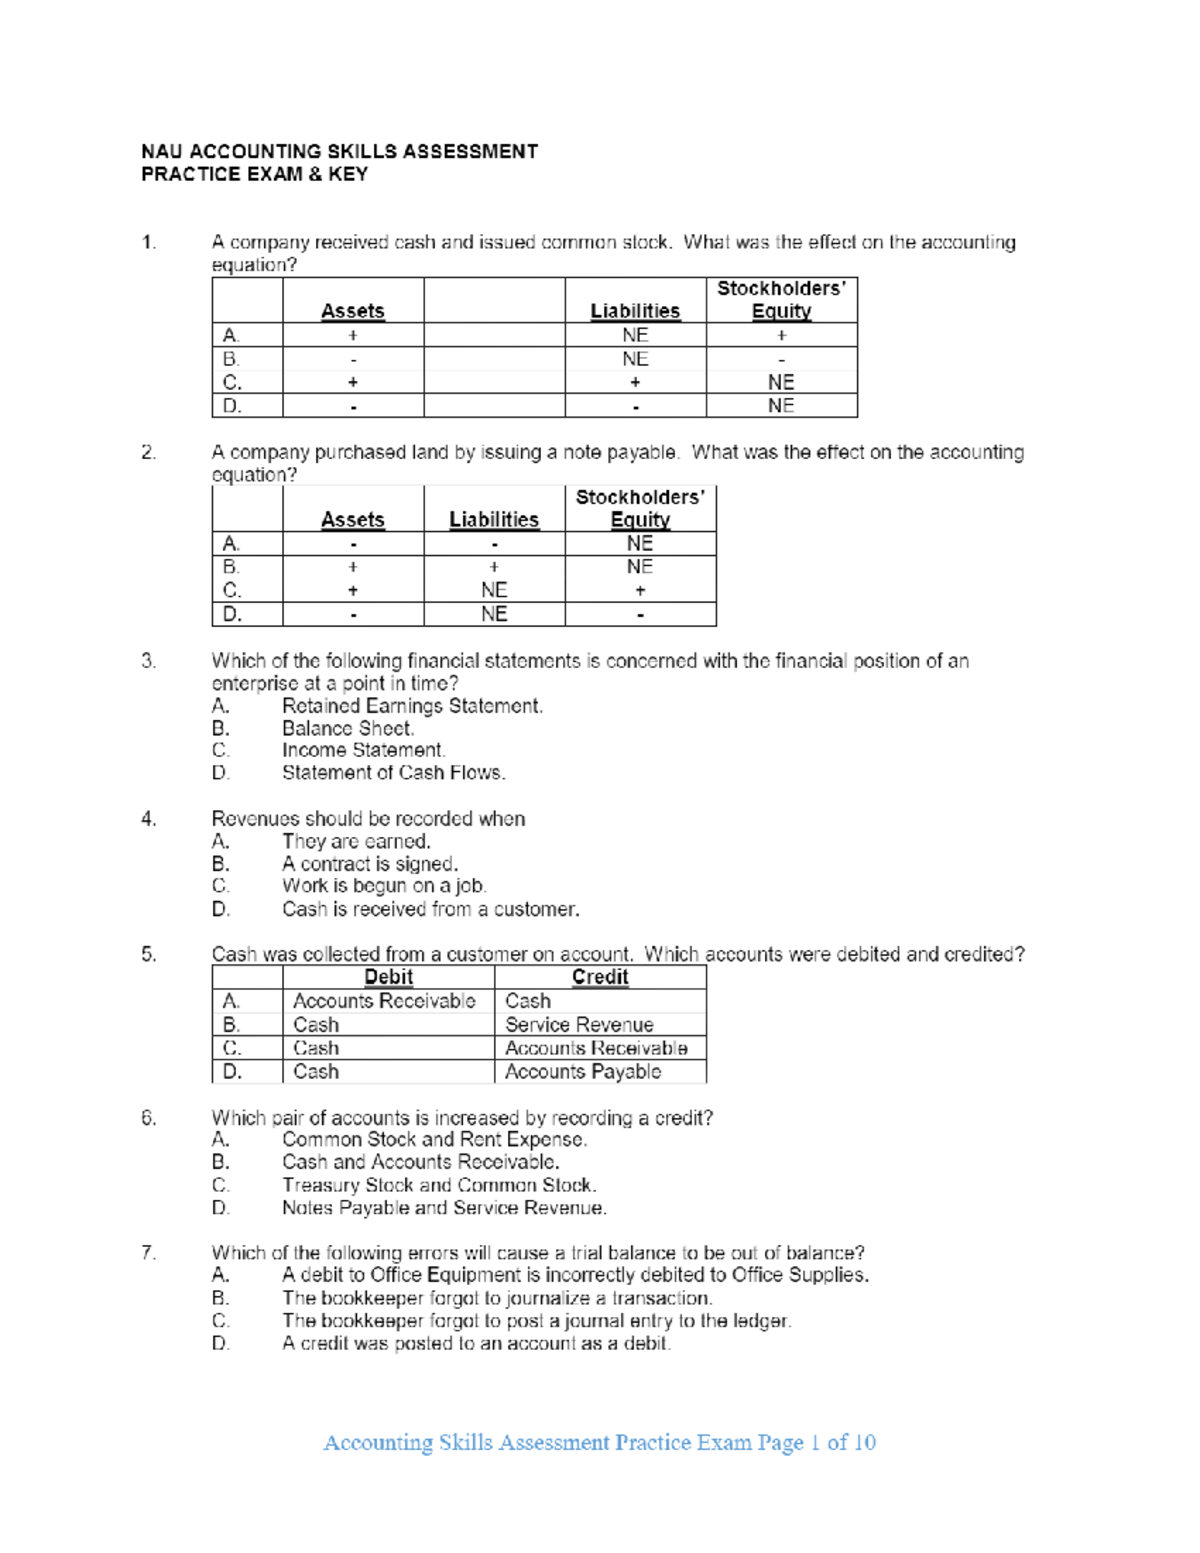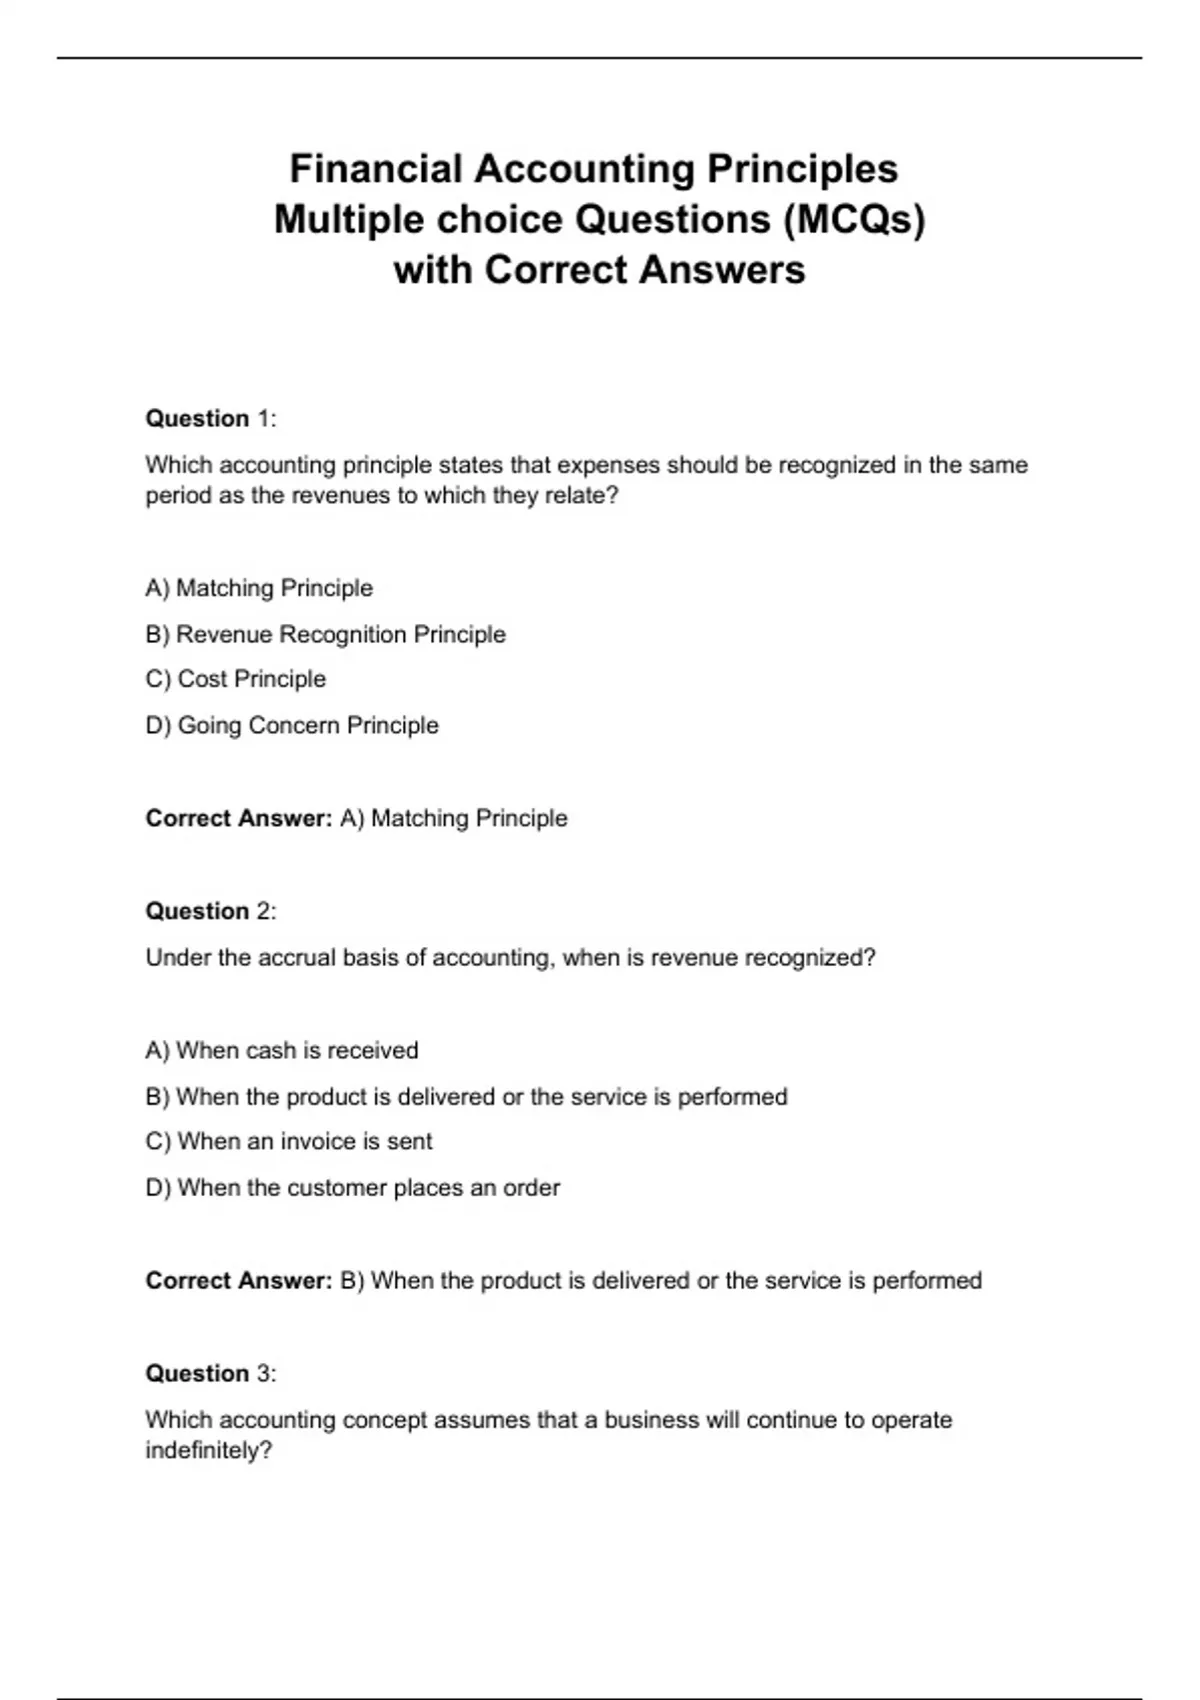
What Accounting Concept Assessments Actually Test
You will often see students and early-career accountants scrambling to find Accounting Concept Assessment Answers because these tests don't measure whether you can memorize debits and credits. They measure whether you understand when those rules bend, break, or simply don't apply. I have watched people fail portion two of these assessments every year. The questions are deliberately vague on purpose. Most accounting concept assessments use a mix of scenario-based multiple choice, short justification questions, and journal entry problems where you must select the right accounts without being told which ones. The trap is assuming the question wants a single correct answer. Many questions have two defensible positions, and the grader is looking for your reasoning, not the textbook answer. I took one of these assessments while prepping for a certification review back in 2019. One question described a company that received a prepaid insurance payment covering twelve months but had only used seven months of coverage by year end. The question asked whether unearned revenue should appear on the balance sheet. The obvious answer is yes. The actual correct response required identifying that the remaining five months create a liability, but also explaining why recognizing the full twelve months as revenue upfront would violate the revenue recognition principle under accrual accounting. Getting half of that right still earned partial credit. Most people missed the second half entirely.
Core Concepts That Show Up Every Time
The assessment consistently circles back to five foundational ideas. If you do not understand these at a practical level, you will struggle regardless of how many answers you find online. Accrual vs cash basis accounting comes up constantly, usually disguised as a question about timing. You need to know that revenue is recognized when earned, not when cash changes hands. Expenses follow the same logic. This sounds simple until a question asks about a service contract spanning two fiscal periods with milestone payments. The matching principle is the other big one. It requires expenses to be recorded in the same period as the revenues they helped generate. Depreciation questions test this directly. A common mistake is treating accumulated depreciation as a cash reserve. It is not. It is a contra asset account that reduces the book value of a long lived asset over its useful life.
Revenue recognition under ASC 606 is now standard material. The five step model matters more than you might expect on these tests. Identify the contract, identify performance obligations, determine transaction price, allocate that price, and recognize revenue when obligations are satisfied. Questions often present bundled services and ask when revenue should be recognized for each component. The answer depends entirely on whether performance obligations are distinct. Going concern assumption shows up less frequently but still appears. If there is substantial doubt about a company ability to continue operating, disclosures become mandatory. The assessment may present a scenario with negative working capital and ask whether the financial statements are still valid. They are, provided appropriate disclosures exist. Materiality is the concept that separates theoretical accounting from actual practice. A $500 error on a $50 million company is immaterial. The same $500 error on a $10,000 company could be critical. Exam questions sometimes include trivial details to test whether you can filter for what actually matters.
Get the Full Details

How to Approach the Questions Themselves
Read every word twice. Not three times. Twice is enough, but most people read once and then guess. Scenario questions often contain a detail that completely changes the answer. A question might say a company uses straight line depreciation, then later mention that the asset was impaired halfway through the year. Impairment changes everything about how you calculate depreciation expense for that period. When you encounter a journal entry question, write out the accounts first before selecting options. The temptation is to match answer choices to your memory of debits and credits, but the options are deliberately scrambled. Some include plausible distractors like prepaid expenses disguised as accrued expenses or deferred revenue confused with unearned revenue. Justification questions require a different strategy. State the principle, apply it to the facts, and conclude. Do not write three paragraphs. Two or three sentences max. Graders scan for key terms and logical flow. "Revenue should be recognized when control transfers to the customer per ASC 606 because the service was completed in the current period" is stronger than "I think we should record revenue now since the work is done."
Common Pitfalls That Cost Points
Confusing accrued expenses with prepaid expenses is the most frequent error. An accrued expense is something you owe but have not yet paid. A prepaid expense is something you have paid but not yet consumed. They sit on opposite sides of the balance sheet and affect the income statement in opposite directions over time. Another pitfall involves bad debt estimation. Some students assume the direct write off method is acceptable under GAAP. It is not for financial reporting purposes. The allowance method is required because it matches the expense to the same period as the related revenue. The assessment may ask you to calculate the adjustment needed given an existing allowance balance and a desired ending balance. Missing the existing balance is how people lose easy points. Consolidation questions trip up a lot of people. Intercompany transactions must be eliminated in full. If a parent company sells inventory to a subsidiary at a profit, that profit cannot appear on the consolidated statements until the subsidiary sells to an outside party. The assessment may give you separate net incomes for two entities and ask for consolidated net income. Simply adding them together is wrong if any intercompany transactions exist.
Where to Find Legitimate Accounting Concept Assessment Answers
Search results for Accounting Concept Assessment Answers are a mixed bag. Some sites are legitimate study repositories. Others are question dumps that will get you in trouble if your instructor uses plagiarism detection. The safest sources are university course pages, professional organization study guides like those from the AICPA or ACCA, and textbook companion sites. These resources typically provide explanations alongside answers, which is what actually helps you learn. Textbook test banks from publishers like Wiley, McGraw Hill, and Cengage are reliable when used properly. They align with specific chapters and concepts. The key is using them to understand why an answer is correct, not just memorizing the letter choice.

What These Assessments Cannot Measure
A concept assessment will tell you whether you understand the theory behind accrual accounting. It will not tell you whether you can close a set of books under pressure during audit season. It will not measure your ability to interpret unclear guidance from a client or your judgment when a transaction falls into a gray area with no clear precedent. Those skills come from experience, not from answering scenario questions in a timed environment. The format also favors students who have taken accounting recently. Someone who learned these concepts three years ago and has been working in a different field will likely perform worse than a fresh graduate, even if that person has stronger practical knowledge. Recency matters heavily on these assessments. Finally, the assessments generally cannot account for differences in accounting standards between jurisdictions. GAAP and IFRS diverge on issues like inventory valuation, lease accounting, and development cost capitalization. If the assessment does not specify which framework applies, you should state your assumption and proceed consistently with it. Most graders will accept either approach as long as it is internally consistent and properly justified.
The reality is that no single resource will prepare you completely. Combine textbook problems with past assessments, practice writing justifications out loud, and focus on understanding the underlying principle rather than memorizing answers. That approach will serve you better than any shortcut you find online.