Why Most Estate Settle Late (And What Actually Moves the Needle)
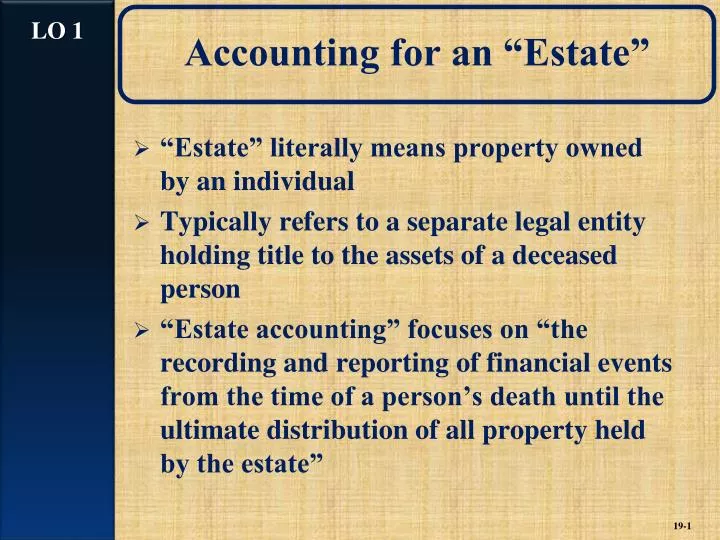
The hardest part of accounting for an estate is not the math. It is getting every single asset located, valued at the right date, and mapped to the correct legal bucket. I have seen estates take fourteen months because the executor assumed a forgotten CD existed in a safety deposit box but never actually pulled the bank statement. One missing form can stall the whole process. At its core, estate accounting is a financial record of everything the deceased person owned, everything they owed, all income the estate earned after death, and how assets were distributed. It is not one document. It is a set of records that must satisfy the probate court, the IRS, state tax authorities, and the beneficiaries. When these groups disagree on numbers, the accounting is what resolves the dispute. The work splits into distinct phases. The first phase is gathering. The second is classification and valuation. The third is recording income and expenses. The fourth is reconciling everything against distributions. The fifth is producing the final account that gets approved. Skip a phase or do it out of order and you will rewrite it later anyway.
The Practical Workflow
Start by requesting death certificates in bulk. Not one. Five to ten certified copies. You will need them for every institution, and each one charges a fee. Ordering them upfront saves weeks. I learned that the hard way in 2018 when an estate in Ohio stalled for six weeks because the probate judge required a certified copy with the raised seal and the local recorder's office was backed up past the state deadline. Step one is creating a master asset schedule. List every account, property, vehicle, business interest, insurance policy, and digital asset. Include the account number, the institution, the custodian, and the date-of-death value. Do not rely on what the family remembers. Rely on statements. A common mistake is valuing retirement accounts using the balance on the last statement before death instead of the alternate valuation date election, if one applies. That error alone can shift taxable income by thousands. Next, pull every bank and brokerage statement from January first through the date of death. Then pull statements for every month the estate remains open. The estate is its own taxpayer once probate starts. It earns interest, dividends, and capital gains. Those numbers go on the estate income tax return, not the deceased person's final return. Mixing them up is one of the most frequent errors I see, and it triggers amendments that add months to closure.
After income and expenses are recorded, calculate the net value available for distribution. This requires tracking payments made from estate funds versus payments made directly by beneficiaries. A beneficiary paying a mortgage on inherited property out of pocket does not reduce estate liabilities. Paying it from estate funds does. The distinction matters for the final accounting and for reimbursement claims.
Get the Full Details

Documents You Will Actually Need
Beyond death certificates and court appointments, you need original wills, trust documents, beneficiary designations, prior tax returns for context, closing statements for real estate, appraisal reports, and receipts for every expense paid from estate funds. Keep originals in a fireproof box. Work from copies. I once spent three days tracking down a lost original quitclaim deed because the executor had taken it home and left it in a junk drawer while dealing with grief. Get copies notarized early. For bank accounts, request a letter from the institution confirming the date-of-death balance. Some banks provide this automatically. Most do not. That email or letter becomes your proof against any beneficiary who later claims a different number. The courtroom reality is simple: paper beats memory every time.
Common Pitfalls That Cost Time and Money
One major pitfall is ignoring small balances. A $47 checking account or a $112 brokerage remainder sounds trivial. It is not. Those accounts must be closed with a formal accounting, or the court will not close the estate. I handled an estate last year where six accounts under five hundred dollars each added four months of extra filings. Closing out those tiny balances upfront with a statutory small-estate affidavit, when available, usually cuts that administrative overhead dramatically. Another pitfall is undervaluing personal property. Furniture, jewelry, art, and collectibles need appraisal if the estate is large enough to file an estate tax return. Even if it is not, beneficiaries often contest vague descriptions in the will. "My collection of silver" is not useful. "12 place settings, sterling, marked by X silversmith, appraised at $Y" is. I recommend obtaining at least nominal appraisals for anything over a few hundred dollars per category. Beneficiary conflict is the third major problem. Two siblings inherit a house and a bank account. One lives in the house. The other wants cash. The accounting must reflect who received what and when. If one sibling occupies the property rent-free during administration, that is an offset that belongs in the final statement. Document it. Otherwise, the other sibling will claim theft later, and the estate accountant becomes a witness instead of a number cruncher.
Where Estate Accounting Breaks Down
It breaks down when the deceased left no organization behind. Missing statements, unclear passwords, shared devices, and digital footprints without backup plans make recovery slow and expensive. In these cases, I usually recommend a forensic approach. File a petition with the probate court to compel financial institutions to produce records. Use the letters of administration as authority. It is not fast, but it is often the only path that produces a court-approved accounting when nothing else is available. Another scenario where this method fails is when the estate is insolvent. Asset values fall below debts. Beneficiaries receive nothing. The accounting still must be complete, but the stakes shift. Creditors become the priority, and disputes move from distribution to validity of claims. An estate that looks solvent on paper but has contingent liabilities, like an pending lawsuit or an unpaid tax position, can turn insolvent during administration. Plan for that possibility before you close.
 IMAGE.jpg?width=1224&height=1584&name=Final Accounting for Estate (Probate) IMAGE.jpg)
Tax Considerations That Change the Numbers
Filing Form 1041 for estate income is mandatory when the estate earns more than six hundred dollars in gross income annually. The estate gets its own taxpayer identification number. Filing Form 706 is required for federal estate tax only when the gross estate exceeds the exemption threshold, which changes yearly. As of my last update, the threshold was high enough that most estates do not need to file, but portability elections for surviving spouses complicate that calculation. If the deceased spouse did not use their full exemption, the survivor may inherit the unused portion, and that election must be made on Form 706 even when no tax is due. State-level rules vary enough that a generic guide will mislead you. Some states have their own estate tax with lower thresholds. Some have inheritance tax that hits beneficiaries differently depending on relationship. Account for both before you finalize distributions. I have seen executors distribute assets based on federal rules alone, then get hit with a state tax bill months later. By then, the money is gone and the beneficiaries are angry.
A Real Case That Teaches Something Useful
I worked an estate a few years back where the decedent had rolled over a traditional IRA into a brokerage firm without updating beneficiaries after a divorce. The ex-spouse was still listed. The accounting for that estate required coordination between the probate court and the brokerage. The IRA went to the ex-spouse by contract, bypassing the will entirely. The remaining estate assets were smaller than expected, which shifted the tax bracket on Form 1041 and changed the distribution amounts for the intended heirs. The workaround was straightforward once I identified the problem early. I pulled the beneficiary designation form directly from the brokerage, confirmed the divorce decree date, and filed a motion with the probate court to clarify that the IRA was non-probate. The court approved it in two weeks. Without that step, the accounting would have shown an inflated estate value and incorrect tax filings. The lesson is simple: contract-designated assets do not belong in the probate inventory, even if they appear on a joint statement. Keep them separate from the start.
What Makes a Clean Final Accounting
A clean final account lists receipts, disbursements, and distributions in chronological order with supporting documentation referenced. Each line item should have a source. Every distribution should tie to a court order or a signed receipt from the beneficiary. Ambiguity is the enemy. "Paid legal fees" is not acceptable. "Paid Smith & Jones LLP $4,200 for probate petition preparation, invoice attached" is. Include a summary schedule at the front. Executors and beneficiaries rarely read every page. They read the summary and then zoom in on disputed items. A well-organized summary with clear totals reduces questions and speeds approval. Courts appreciate it. Beneficiaries appreciate it. Everyone wins when the paperwork does not force a second round of revisions. Estate accounting is tedious by design. It is supposed to be. The goal is a record so complete that no reasonable person can dispute where money went. That record protects the executor, the beneficiaries, and the integrity of the process. Anything less just creates work for everyone involved.