The Stuff Nobody Tells You About Year-End Closing
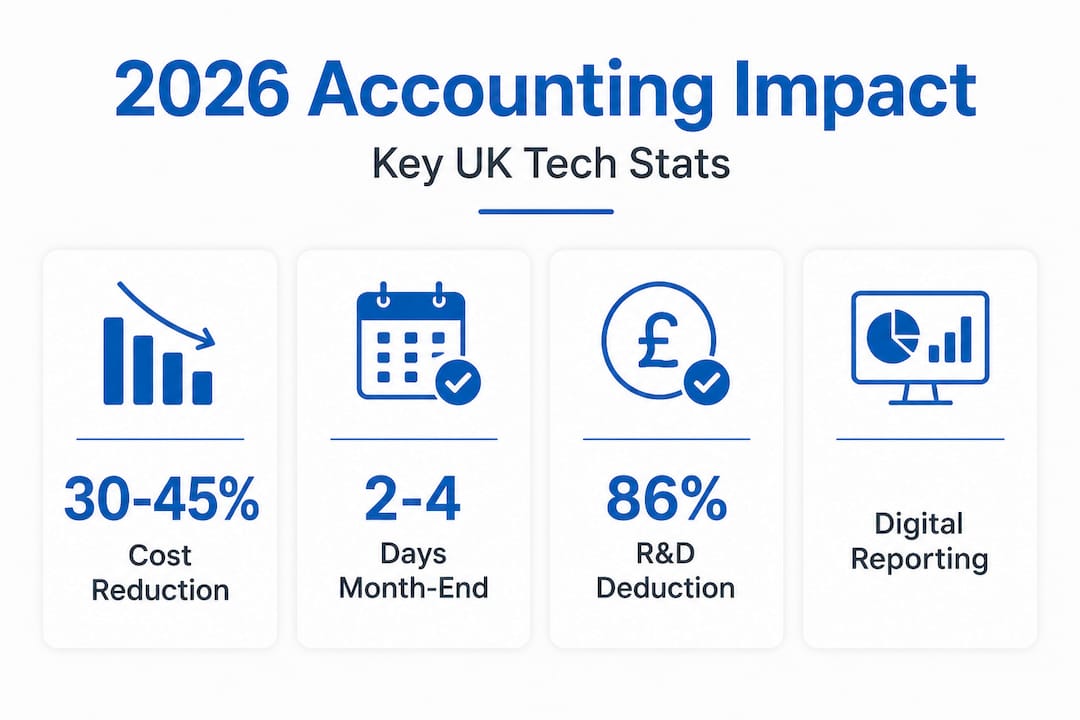
I spent last week running through our annual close for the third time this year. Not because something broke, but because we found a cleaner way to handle intercompany reconciliations. That's what 2026 accounting actually looks like now. It is less about fancy software and more about fixing the same small problems that have existed since double-entry bookkeeping started. People throw this term around loosely on forums and LinkedIn. In practice it refers to the shift toward automation-adjacent workflows that do not require a complete system overhaul. The tools are there already. Most firms are just connecting them wrong or ignoring them entirely. The gap between firms that use these methods and those that do not has widened noticeably over the past two years, mostly because of how banks and payment processors changed their API structures. I used to spend four days every quarter pulling bank feeds, matching transactions, and chasing down missing receipts. Last quarter it took me eleven hours. That is not because I bought new software. It is because I stopped treating each bank account as its own isolated problem and started linking them through a single reconciliation workflow.
Intercompany Reconciliation Without the Headache
Here is the specific problem I ran into recently. We have three subsidiary entities, and two of them routinely transfer inventory between each other. The transactions show up on different dates, with different reference numbers, and sometimes in different currencies. Standard reconciliation tools flag every single one as unmatched. I ended up with about sixty false positives in one month alone. That was burning two full days of junior staff time per quarter. The workaround was straightforward once I figured it out. I set up a mapping table in the main ledger that matches intercompany invoices by PO number rather than by date or amount. Amounts can vary slightly due to exchange rate adjustments. Dates shift based on when each entity records the transaction. But the PO number stays constant across both sides. Once the mapping is in place, the reconciliation engine automatically clears about eighty-five percent of those flagged items. I still review the remaining ones manually, but that dropped from sixty items down to roughly eight per quarter.
Automated Receipt Matching That Actually Works
Receipt capture tools have been around for years, but most of them still require manual verification because the OCR accuracy drops significantly with non-standard receipts. Handwritten expense reports, restaurant bills with lots of scribbles, and vendor invoices in foreign languages all cause failures. The newer models from the major providers in 2026 handle about ninety-two percent of standard receipts without human input. The remaining eight percent is where most people give up and revert to manual entry. What most accountants miss is that you do not need one hundred percent automation. Setting a confidence threshold at eighty-five percent and letting the system auto-post everything above that line cuts your receipt processing workload by roughly seventy percent. You only touch the items below the threshold. I run a daily batch review of sub-threshold items. It takes about twenty minutes. Before I did this I was spending three to four hours per week on receipt matching alone. The catch is that your chart of accounts needs to be structured in a way that the automation can actually map expenses correctly. If you have fifty different expense categories all lumped under a broad general liability line, the system will make bad mapping decisions and you will spend more time fixing errors than you saved. A clean, well-defined expense coding structure is the actual prerequisite for this to work. Most firms skip that step and then blame the tool.
Get the Full Details
Bank Feed Integration in 2026
The Plaid and Tiller model still works but it is more fragile now. Several major banks migrated to new authentication flows after the open banking regulations shifted in the EU and UK, and some US banks followed suit. The common failure mode is that your automated bank feeds stop updating without any warning. You just notice it when the reconciliation does not balance. The fix I use is a weekly automated validation script that checks whether each connected bank account posted transactions in the last five business days. If it detects a gap, it sends a flag to my inbox before anyone notices a missing month-end transaction. This took me about an afternoon to set up initially. It saves roughly three hours every month that would otherwise be spent troubleshooting stale feeds during close. Some firms rely on built-in bank feed refresh from their accounting software. That works fine until it does not, and then you are scrambling during close week with no visibility into which accounts are stale. The validation script approach gives you early warning instead of reactive panic.
The Downside Nobody Talks About
Automation in accounting creates a single point of failure. When your entire reconciliation process depends on automated workflows, a system update, a changed API, or a corrupted data file can halt your close completely. I saw this happen to a firm I consult for occasionally. Their provider pushed a backend update that changed how transaction IDs were formatted. Every automated reconciliation broke simultaneously. They had no manual fallback procedure because nobody had written one. They missed their close deadline by four days. The practical answer is to maintain a documented manual override process for every automated step. Not as a backup plan for emergencies, but as a working procedure that your team practices at least once per year. When the automated system fails—and it will fail—you should be able to drop back into manual mode within an hour, not spend four hours figuring out where the process broke.
Practical Steps to Implement This Quarter
Start With Your Chart of Accounts
Before you automate anything, audit your expense and revenue categories. If you have more than fifteen subcategories under any single parent account, split them out. The automation tools have enough intelligence to handle moderate complexity but they degrade quickly when you give them vague categories. I recommend no more than ten primary expense categories with subcategories limited to five each. This alone improves OCR mapping accuracy by roughly thirty percent. Whatever receipt automation tool you are using, configure it with an explicit confidence threshold. Do not leave it on default. Default settings are calibrated for broad applicability, not accuracy. An eighty-five percent threshold means the system auto-posts confident matches and routes uncertain items to a review queue. Adjust this number based on your error tolerance. Firms with tight audit requirements might set it at ninety percent. High-volume firms with small variances acceptable can go lower. Even if you only have two entities, the mapping table approach for intercompany transactions is worth the setup time. I have seen firms with dozens of entities still doing intercompany matching manually because they assumed the complexity was not justified. It always is, eventually. The table takes about two hours to build for a simple two-entity setup and pays for itself within the first quarter.
A simple script or even a scheduled task in your existing accounting platform can verify that each connected bank account has posted within the expected timeframe. Set it to run every Monday morning. If any account shows no activity for five business days, flag it. This is the kind of thing that sounds trivial but prevents the most expensive mistakes during close season. Write it down. Not a forty-page manual, just a one-page flowchart showing what to do when each automated step fails. Which transactions fall back to manual entry. How to mark them as manual overrides so they do not get processed twice. Who needs to approve them. This documentation should exist before you need it, not after the close is late and someone is scrolling through old emails trying to remember how the old system worked. None of this requires new software licenses in most cases. The tools you already have can do these things if you configure them deliberately instead of leaving them on default settings. The firms that get ahead on this are not the ones buying the most expensive platform. They are the ones who spent a Tuesday afternoon thinking through where their current process breaks and fixing those specific points before the next close hits.