The messy reality of tracking your own books
Most people who try to manage accounting without some kind of tracker end up with three spreadsheets that don't match, a bunch of PDF receipts buried in email attachments, and a tax season that feels like defusing a bomb. I spent four years running a small e-commerce business and learned this the hard way. The accounting tracker isn't glamorous, but it's the single thing that kept me from losing sleep every April. An accounting tracker is simply a system — digital or manual — where you record every financial transaction in one place. Income, expenses, accounts receivable, accounts payable, bank reconciliations. The idea is that everything lives somewhere central so you can look at your actual financial position without doing forensic accounting every time you need a number. Simple concept. Execution varies wildly depending on what you're tracking and how much money is moving through the system.
What an Accounting Tracker actually does
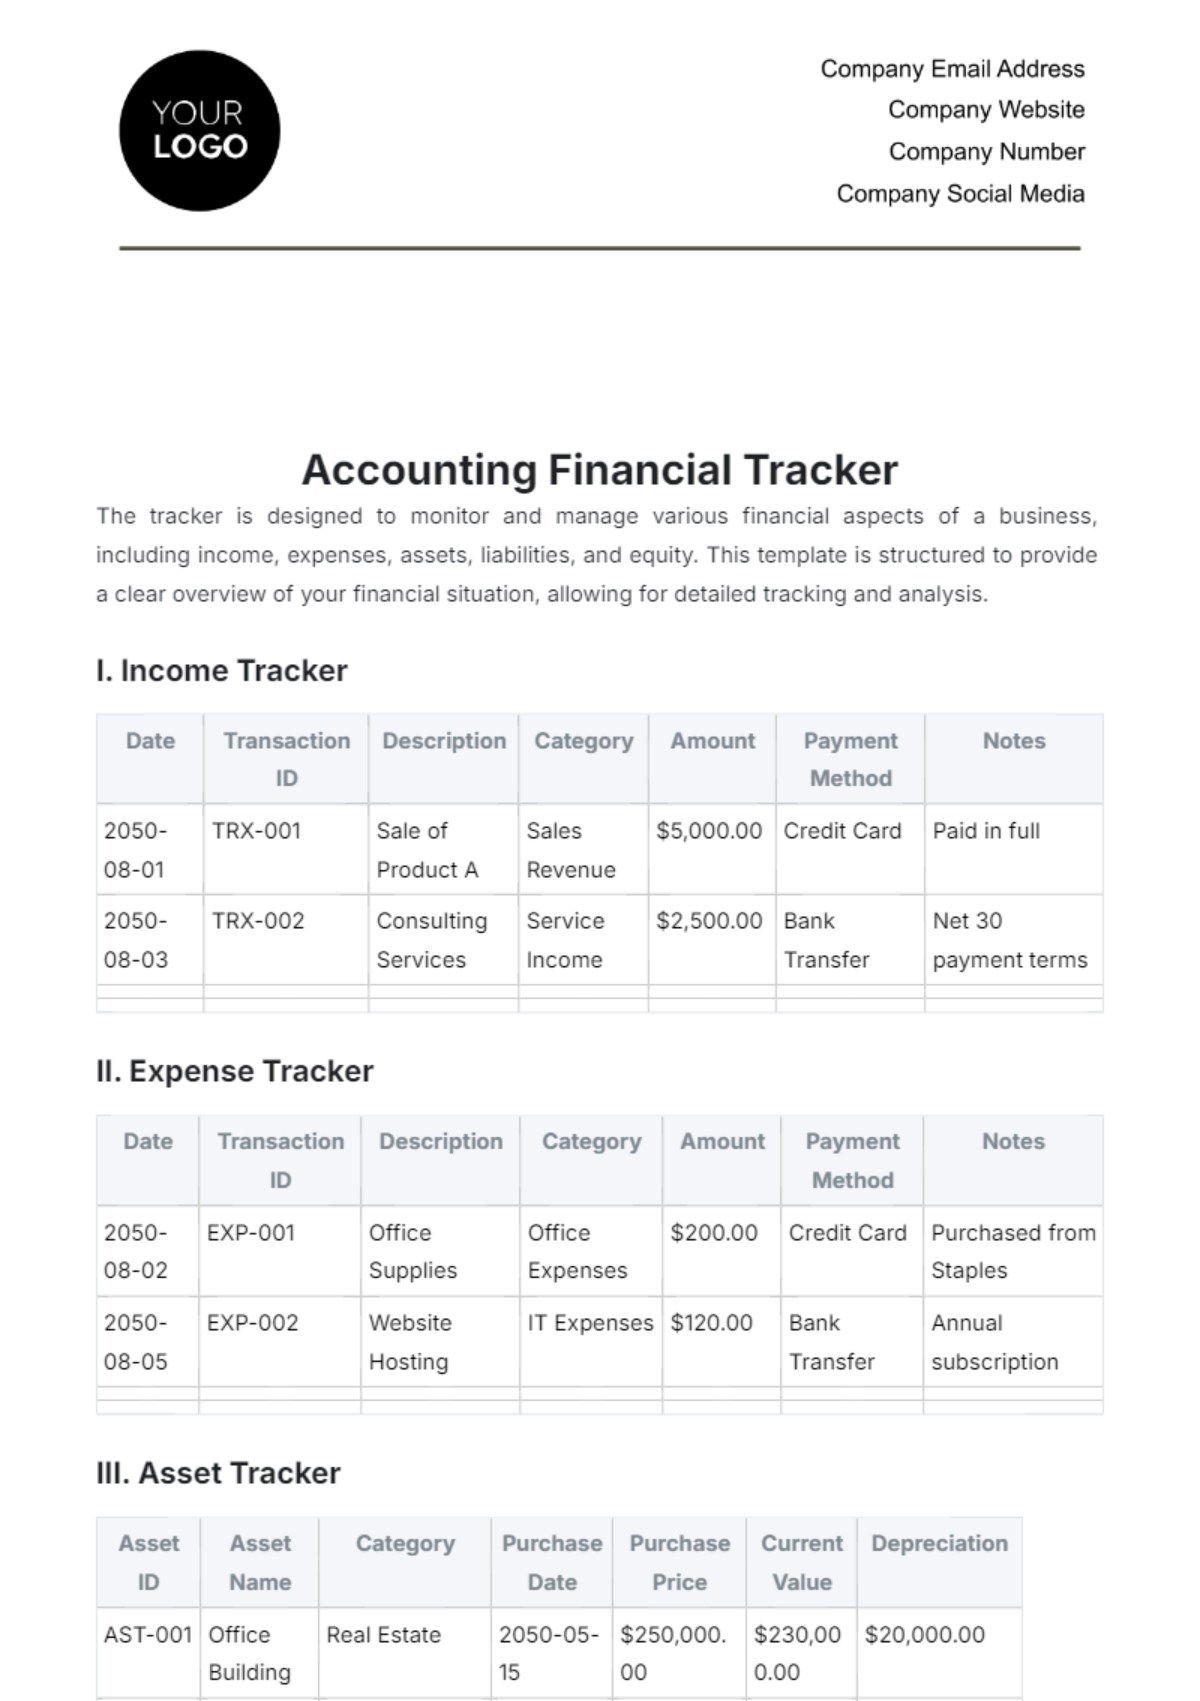
At its core, a basic accounting tracker records transactions with dates, amounts, categories, and references. Double-entry bookkeeping is the standard most people end up using because single-entry just doesn't scale past a certain point. Once you're handling more than roughly $50,000 a year in revenue, single-entry becomes a liability. I found that out when my monthly bank reconciliation took six hours instead of forty minutes. The moment I switched to double-entry tracking, the same process dropped to about fifteen minutes. Every transaction affects at least two accounts. Revenue goes up, cash goes up. Expenses go up, cash goes down. Accounts receivable tracks money people owe you. Accounts payable tracks money you owe. The tracker keeps these balanced so your balance sheet actually balances. If it doesn't, something is wrong and you'll spend hours debugging it later. Much better to catch it when it happens.
Picking the right tool for your situation
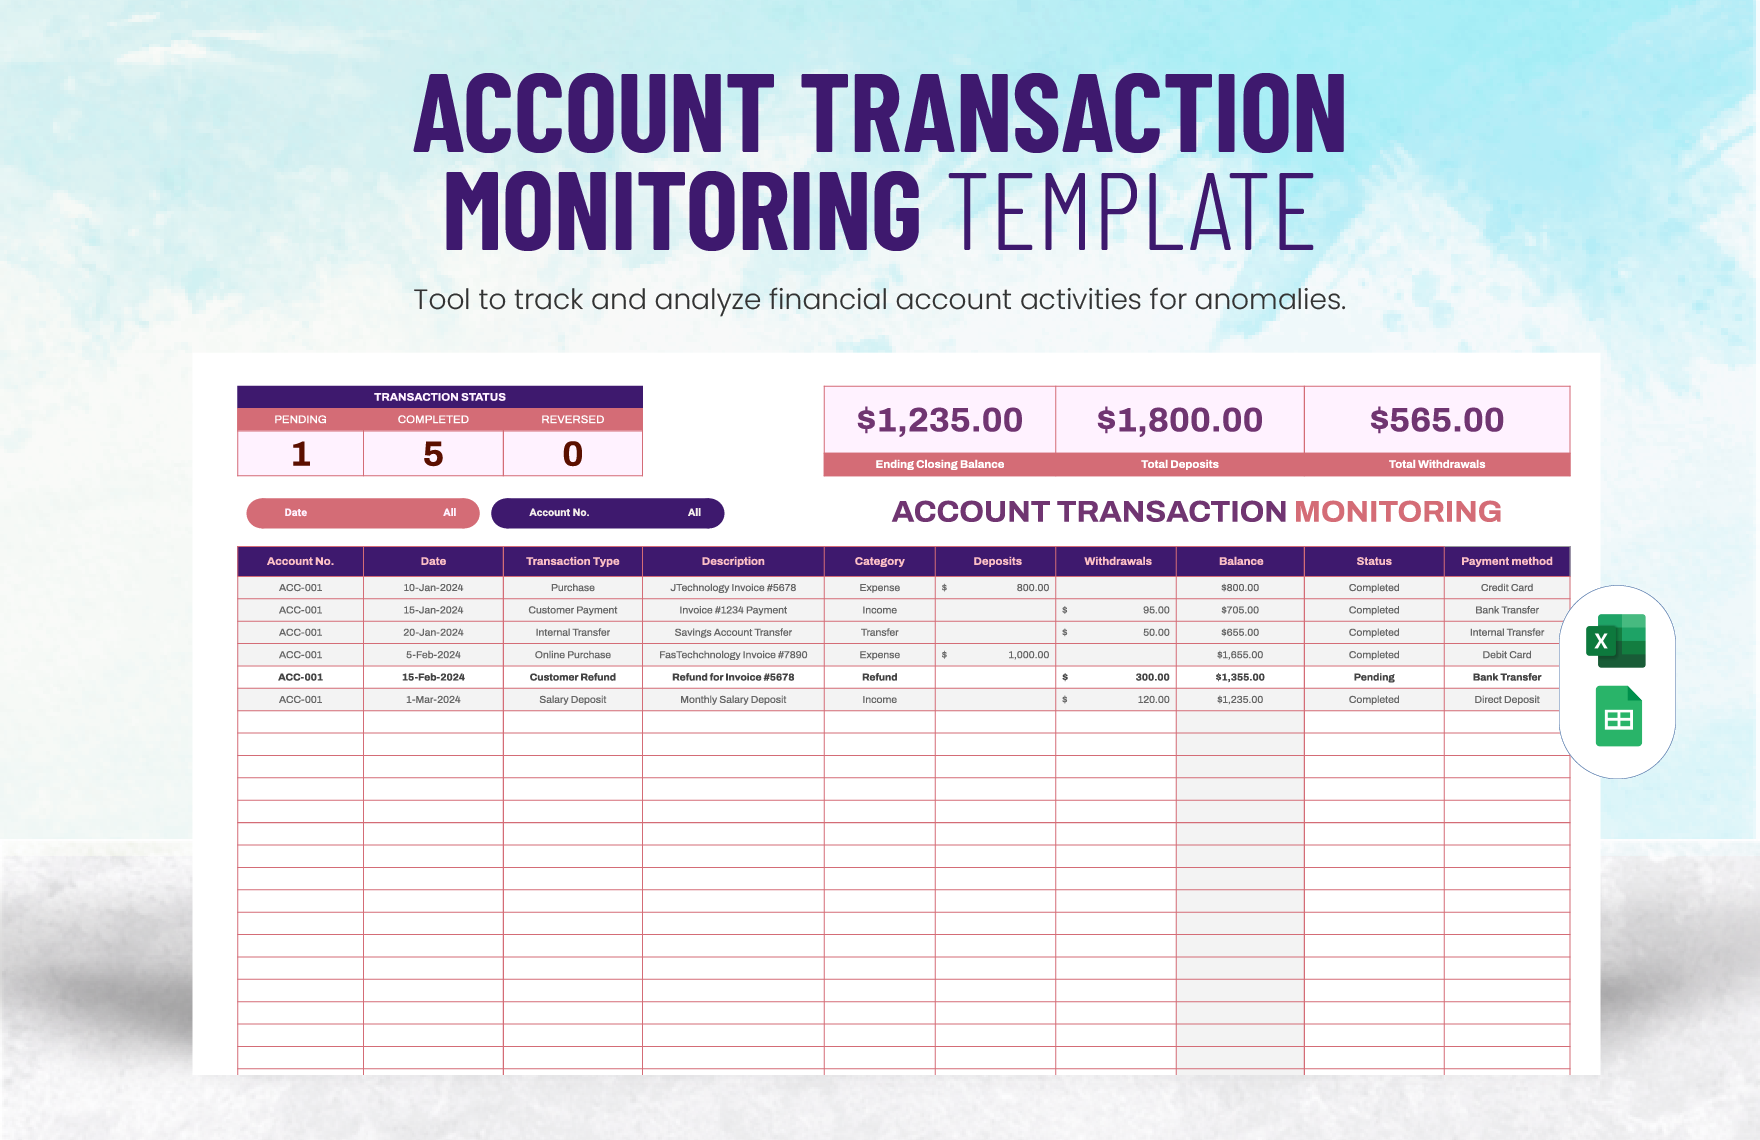
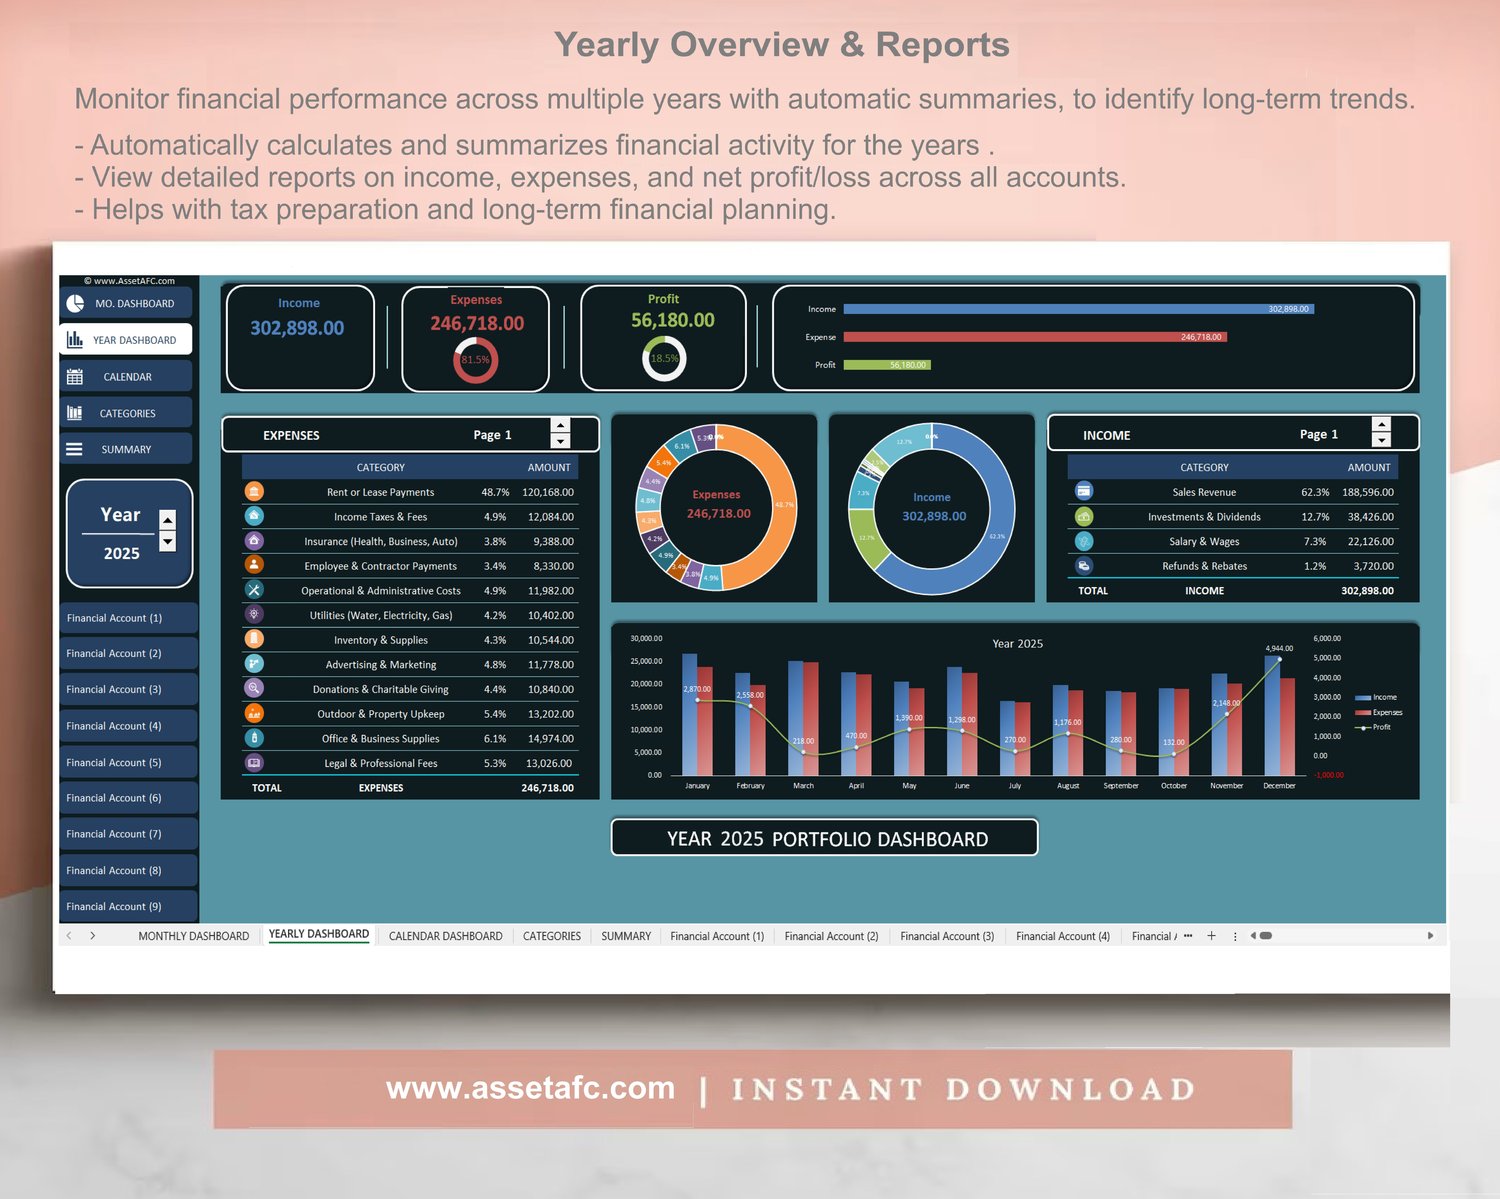
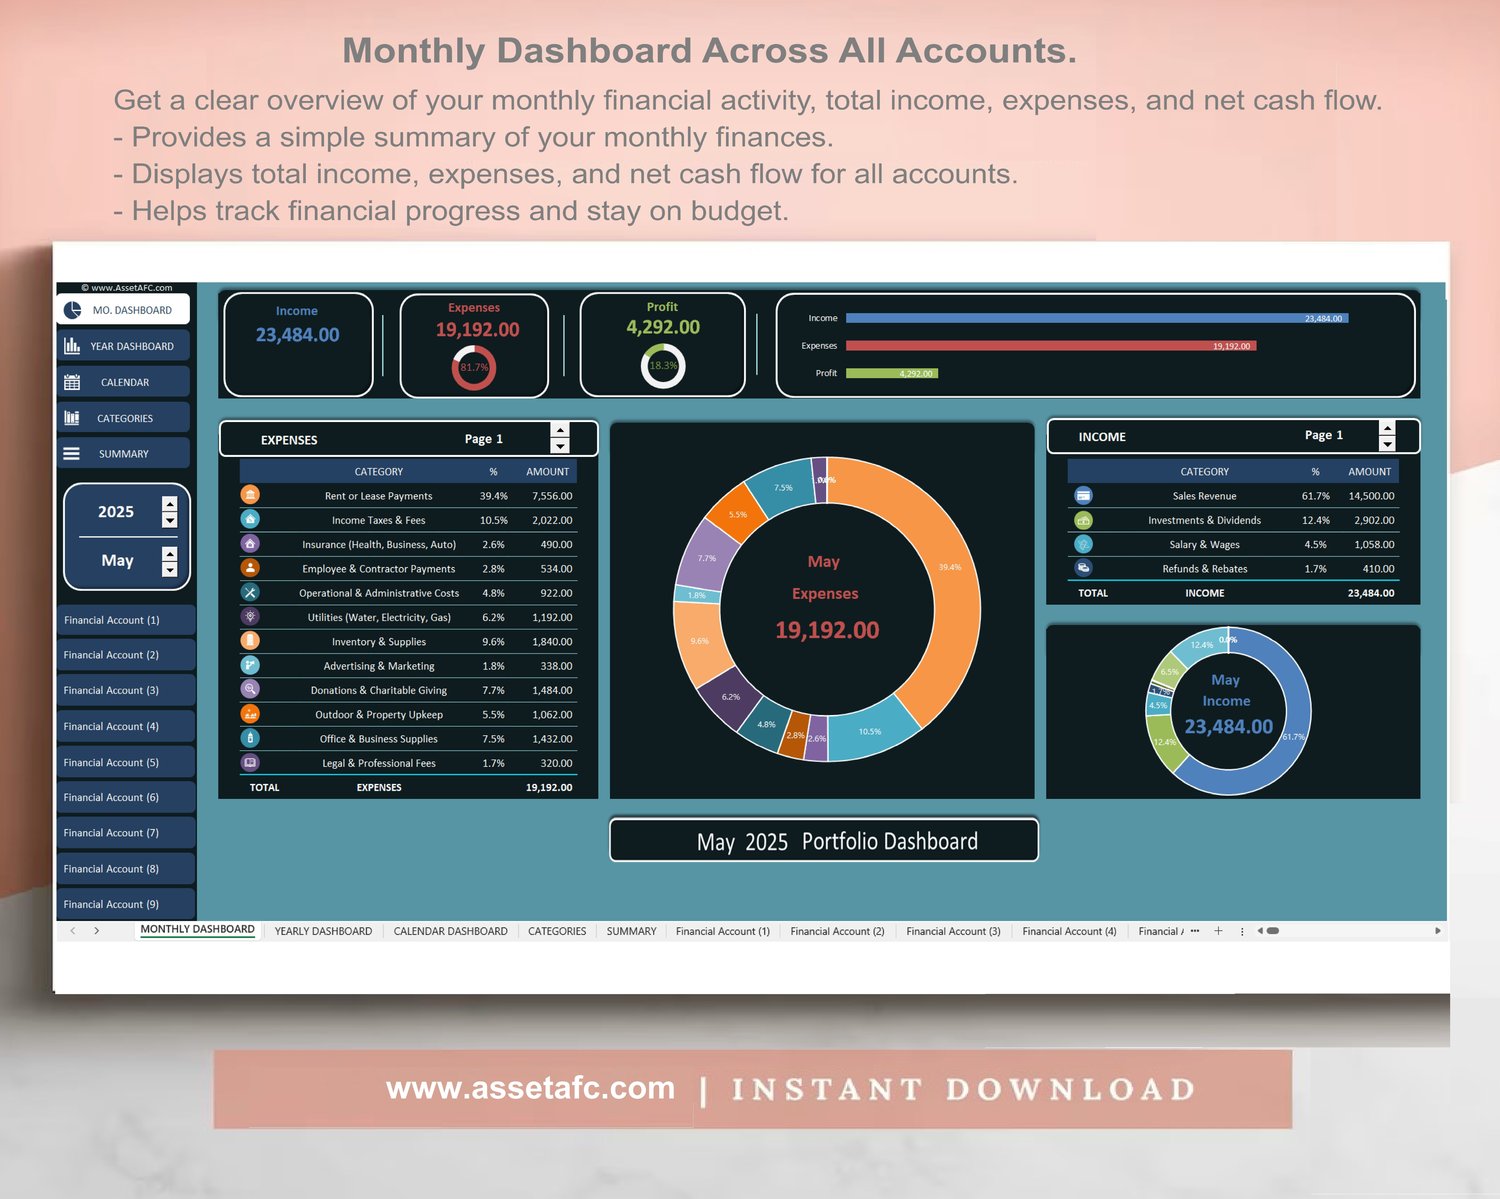
There are three tiers of accounting tracker and each serves a different type of operation. Understanding which tier you're in will save you more time than any feature comparison. Tier one is spreadsheet-based tracking. Google Sheets or Excel. Fine for solopreneurs, hobby businesses, or anyone under about $100,000 annual revenue who wants zero recurring cost. The disadvantage is that spreadsheets have no built-in audit trail, no multi-user support without becoming a mess of version conflicts, and reconciliation is entirely manual. I used this for about a year before my transaction volume made it untenable. The moment I had more than forty transactions per month across three different accounts, the spreadsheet started lying to me. Not intentionally, but formulas break, rows shift, and before you know it your P&L is off by a few hundred dollars and nobody knows why. Tier two is cloud accounting software. QuickBooks Online, Xero, FreshBooks, Wave. This is where most small businesses land and stay. Automatic bank feeds pull transactions daily. Categorization rules reduce manual entry to near zero for recurring items. Monthly bank reconciliation takes maybe twenty minutes once the initial setup is complete. Tax reports generate themselves. The main downside is subscription cost and the learning curve if you've never done real bookkeeping before. Expect about two weeks of frustrating configuration before things feel normal.
Get the Full Details
Tier three is enterprise-level. NetSuite, SAP, Oracle Financials. These are overkill for almost any business under five million in revenue. They're worth considering if you have multiple entities, international currency requirements, or need inventory tracking tied to COGS. I've seen people implement these for businesses doing two million a year and watch them spend more time maintaining the system than doing actual accounting. Don't do that.
Setting it up without making it worse
The biggest mistake I see people make is treating the initial setup as something to rush through. Chart of accounts configuration, bank account linking, opening balance verification, recurring transaction setup. If you skip any of this, you're building on a foundation with cracks in it. A proper chart of accounts for a small business usually runs between forty and eighty accounts. Not more, not less. Most templates online give you something like two hundred accounts because they're designed for companies that have departments, subsidiaries, and cost centers you don't need. Trim yours down to what you actually use. You'll thank yourself during tax season. Opening balances are where people get tripped up. Don't just copy the number from your bank statement. Your bank statement shows cash. Your chart of accounts also needs accounts receivable, accounts payable, credit card balances, loans, and equity entries. If you only enter the bank balance and ignore the rest, your books will be out of balance by whatever those other accounts total. I learned this when my first bank reconciliation showed a discrepancy of $12,847 and I spent three days hunting for a missing invoice before realizing I'd never entered the credit card balance as an opening figure. Bank feed setup should happen early but not before your chart of accounts is finalized. Once feeds start pulling, categorization rules lock in patterns and changing your account structure after that point means going back and re-categorizing months of transactions. Settle on your account structure first. Then connect the feeds. Then build your rules.
Common pitfalls nobody warns you about
Clean data matters more than features. An accounting tracker with automatic bank feeds is useless if every transaction is miscategorized. I've seen people brag about their software while their expense reports were wrong because they had a rule that sent all PayPal transactions to "miscellaneous" instead of the correct expense category. Review your rules quarterly. Transaction volume grows, product lines shift, and old rules start misfiring without anyone noticing until it's too late. Reconciliation shouldn't be an annual event. Do it monthly at minimum. Quarterly reconciliation is the point where problems compound into disasters. If your books are off by a few hundred dollars and you only check once a year, that error has been propagating through every report you generate for twelve months. Monthly reconciliation takes about as long as a coffee break once your system is set up properly. Twenty to thirty minutes. Do it on the first business day of the month and move on. Here's a specific edge case that caught me completely off guard. I was tracking revenue for an e-commerce store and noticed my accounting tracker showed about eight percent less income than my platform's dashboard. I spent two weeks investigating. Turned out the issue was with how refunds were handled. My payment processor refunded customers immediately but the refund didn't appear in my bank account until three to five business days later. My accounting tracker recorded the expense when the refund hit the bank, not when it was issued. So my revenue looked lower than it actually was for that month because the refund was in a different period. The fix was simple — I switched to recording refunds when they were issued in the platform, not when they cleared the bank. But it took me three months of confused analysis to figure out what was happening. Make sure you understand how your tracker handles timing differences between transaction dates and settlement dates before it becomes a problem.
Maintenance habits that matter
Enter transactions daily or at least every other day. I know this sounds obvious but most small business owners batch their entry work into one chaotic session per month. Daily entry takes about five minutes. Monthly batching takes about four hours and involves more errors because you're relying on memory to fill in gaps. Keep digital receipts attached to every transaction. Not in a separate folder somewhere. Attached directly to the transaction in your tracker. When the IRS or your auditor asks for documentation three years later, you'll either have it ready in thirty seconds or you'll be digging through email threads and printer folders hoping something survived. I use a tool that snaps a photo of physical receipts and attaches it automatically, but even the manual version of dragging a PDF onto a transaction is worth the effort. Review your profit and loss report every month, not just at tax time. A thirty-minute monthly review catches problems early. Things like a vendor raising their rates without notification, a recurring subscription you forgot about, or revenue dropping below expected thresholds. If you only look at your P&L once a year, you're flying blind for eleven months.
Cost estimates for running a basic accounting tracker: Spreadsheet method is free but your time cost rises significantly around transaction volumes above thirty per month. Cloud software runs between twenty and fifty dollars per month depending on features. Professional bookkeeper assistance, if you need it, typically runs two hundred to five hundred dollars monthly for small business volume. Factor in the software cost when deciding whether to DIY or hire help.
When your tracker stops working for you
No accounting tracker handles everything perfectly. Here are the scenarios where you'll hit walls: Multi-currency operations require software that supports automatic exchange rate updates. Most entry-level trackers don't do this well. If you invoice in USD but pay suppliers in EUR and JPY, you need something like QuickBooks Online Plus or Xero with a dedicated FX solution. Otherwise you're manually calculating exchange gains and losses, which is tedious and error-prone. Inventory-heavy businesses run into COGS complications. Every item you sell needs to be tracked through purchase, storage, and sale. Basic accounting trackers treat inventory as an expense when you buy it, not as an asset until it's sold. If you carry significant inventory, this distorts your profit figures month to month. You need inventory management integrated into your accounting tracker or a separate system that syncs with it.
Multi-entity structures break most small business trackers. If you're running two LLCs that share expenses, employees, or equipment, your accounting tracker needs to handle inter-company transactions cleanly. Basic tools muddle this and you end up with commingled finances that create tax and legal problems far worse than the accounting inconvenience. The honest assessment is that for a straightforward single-entity business with domestic currency operations and minimal inventory, a mid-tier cloud accounting tracker handles everything you need. For anything more complex, the complexity of your situation should dictate the tool, not the other way around. Running a sophisticated operation through a simplified tracker creates more work than doing the work manually, which sounds wrong but is genuinely true in practice. I've watched this happen.
Getting started today
Choose your tier based on your actual revenue and transaction volume, not your ambitions. Set up your chart of accounts before connecting any bank feeds. Verify opening balances against your actual financial statements, not your memory. Reconcile monthly from day one. Keep receipts attached to transactions. Review your P&L every month. Handle refunds and timing differences with awareness of how your tracker records them. These are the things that separate a system that works from a system that looks like it works until it doesn't.