Getting Your Books Actually Sorted Without Going Crazy
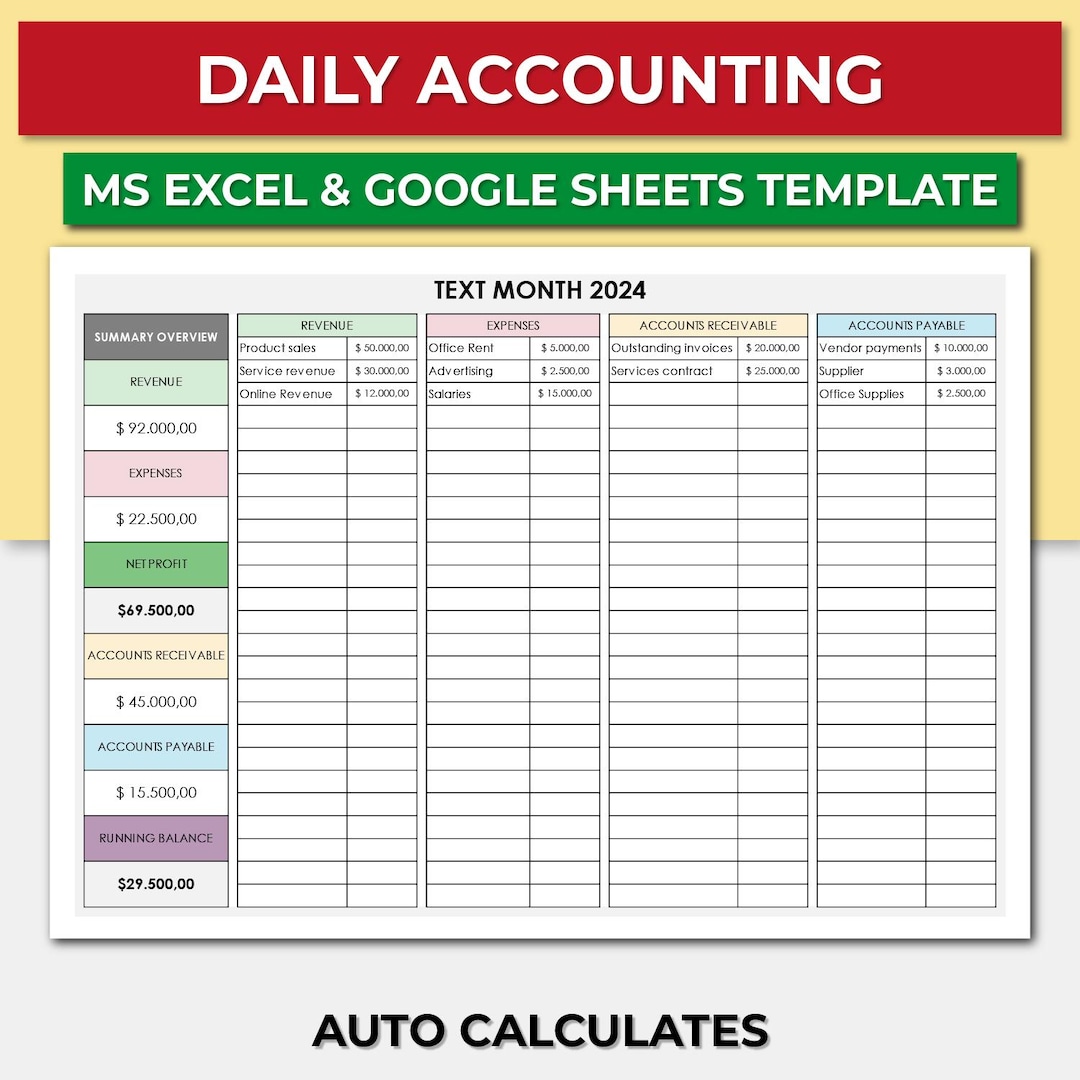
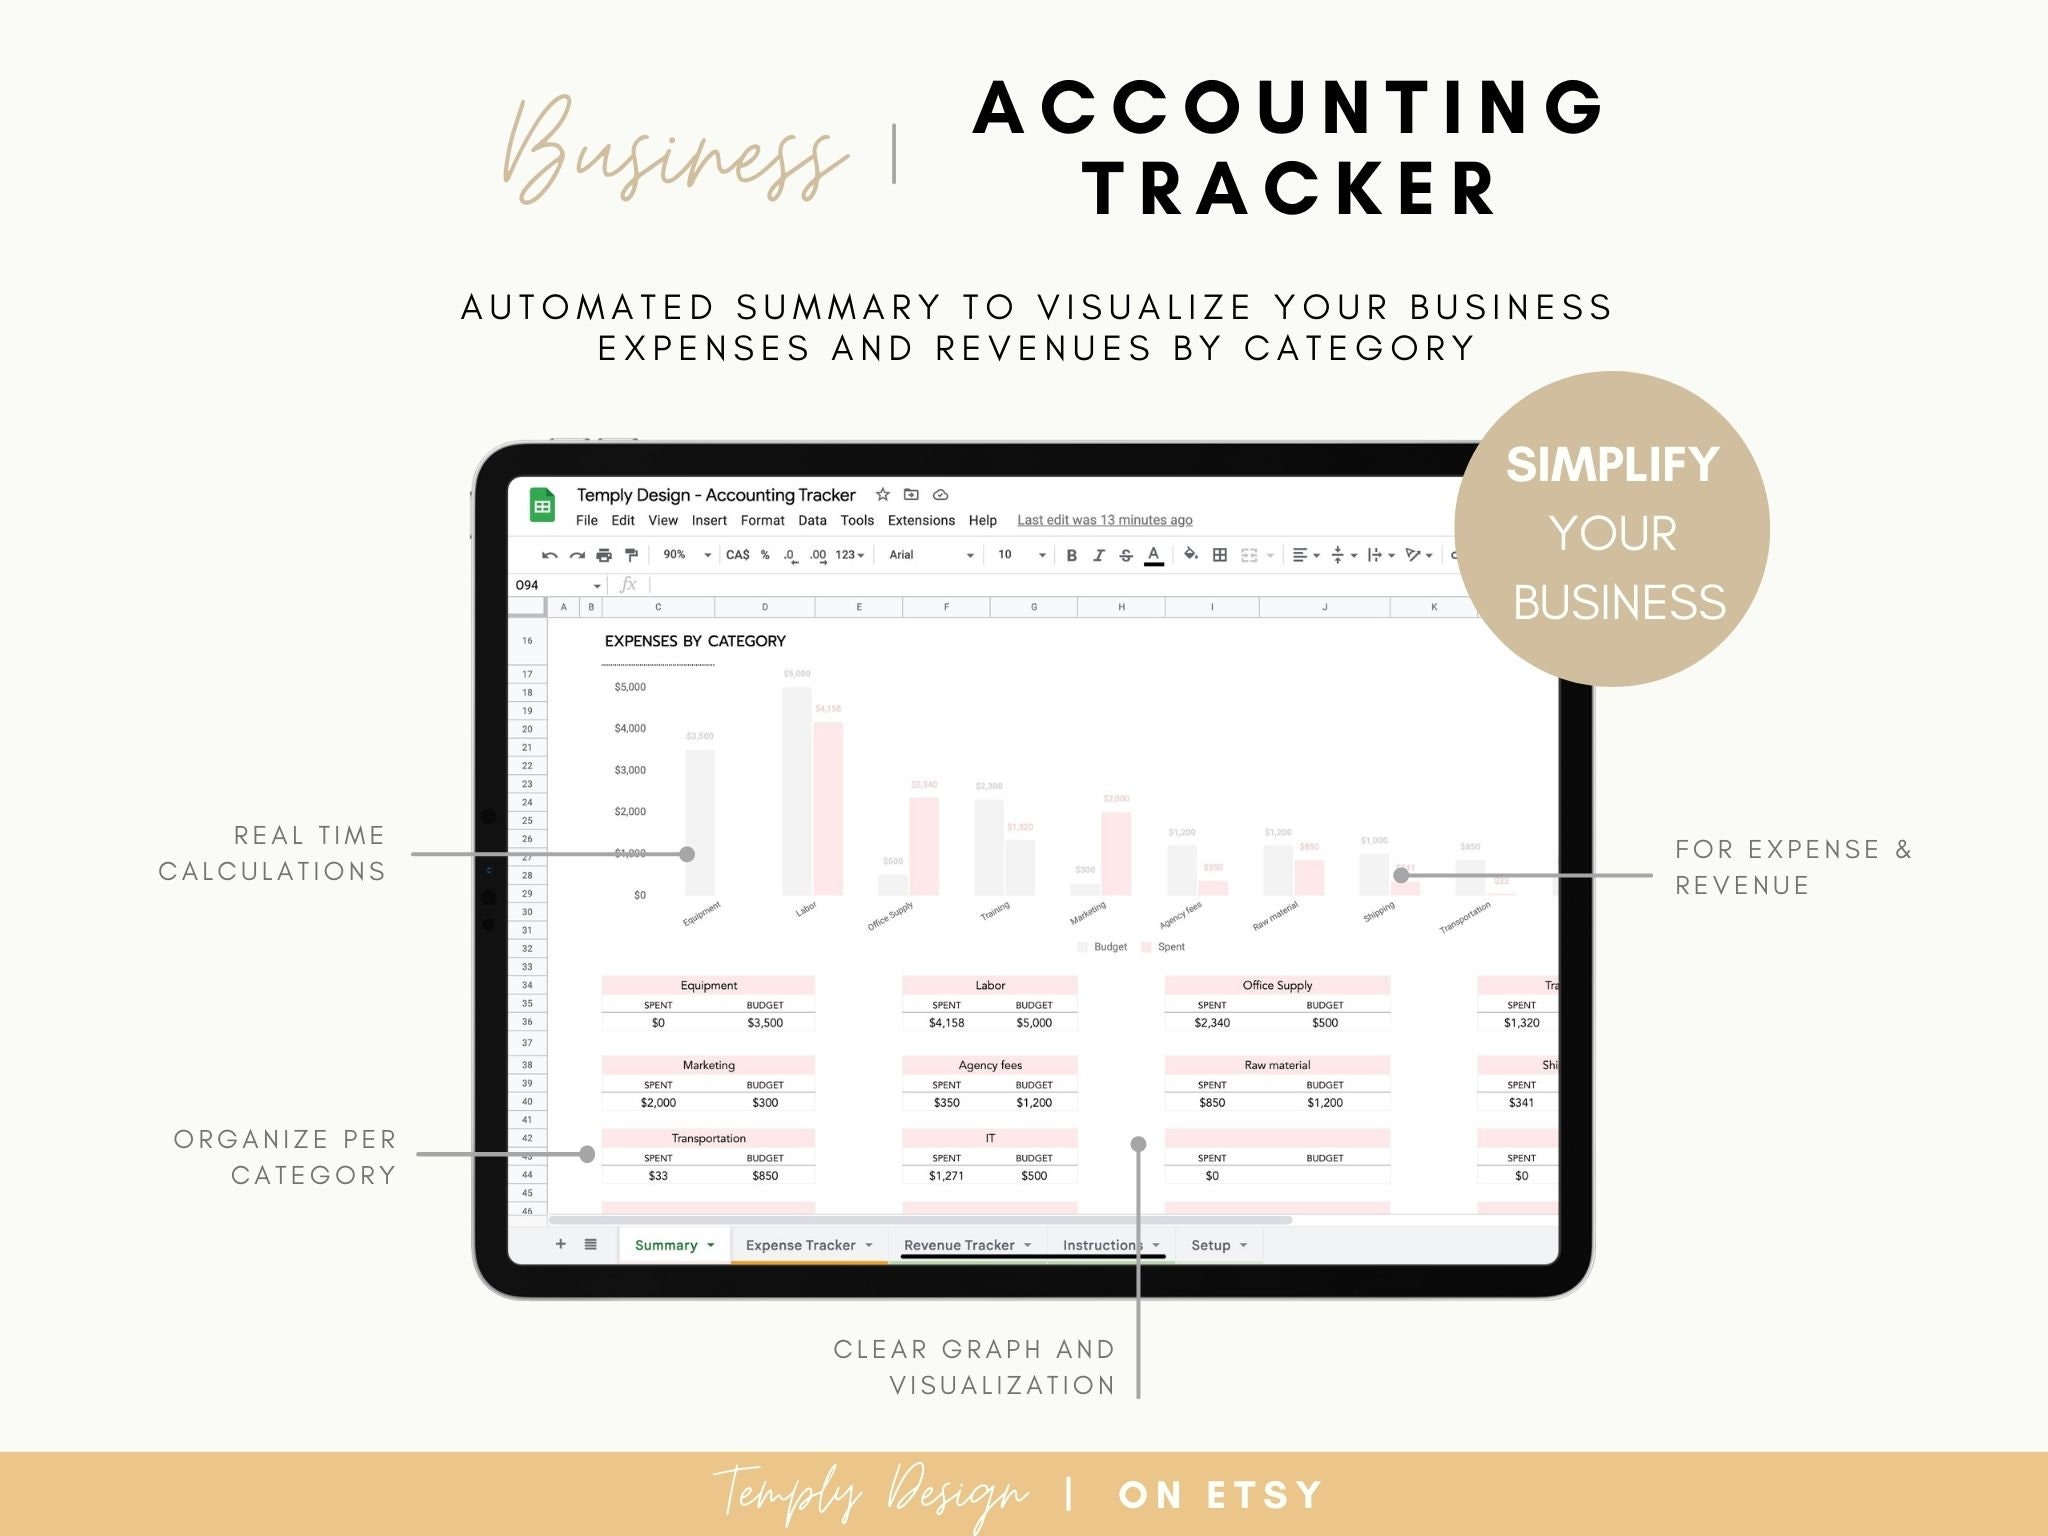
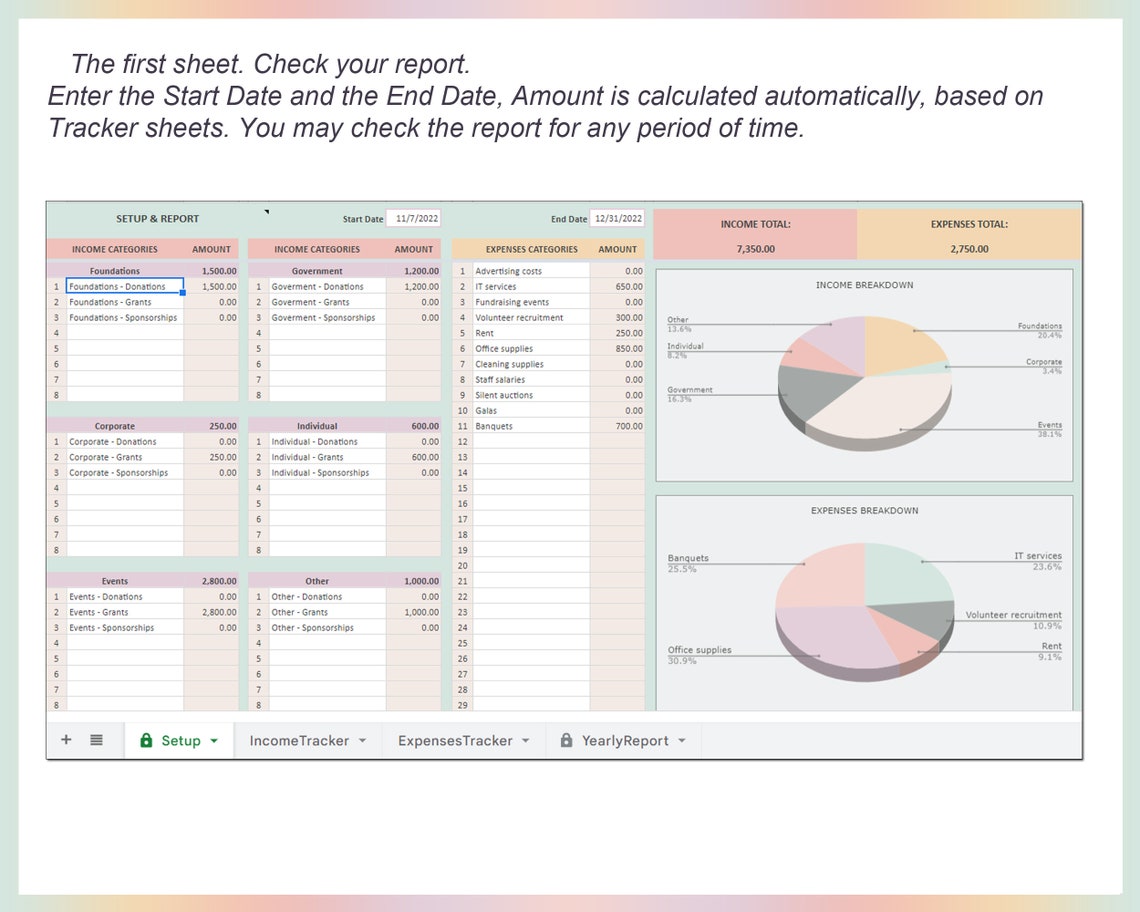
I spent about three years trying to keep personal finances and a small consulting business straight using a bunch of different spreadsheet systems, budgeting apps, and everything in between. Most of them were either too complicated for what I needed or they fell apart the moment something unexpected showed up. I eventually landed on something I ended up calling my Accounting Tracker Quick setup, which is honestly just a well-organized spreadsheet with some conditional formatting and a few smart formulas. People sometimes ask me about it, so I figured I would put together a proper rundown. The core of the system is a main transaction log with about eight columns: Date, Description, Category, Subcategory, Type (income or expense), Amount, Account, and Status. The status column is where most people mess up, and it is also what makes the whole thing work. You are basically tracking whether a transaction has been reconciled against your bank statement or not. Everything else flows from that. Below the transaction log, I have a summary sheet that uses SUMIFS formulas to pull data by category and by month. It looks like this: =SUMIFS(Amount_Column, Category_Column, "Office Supplies", Date_Column, ">="&DATE(2024,1,1), Date_Column, "<="&DATE(2024,1,31)). It is not fancy but it does exactly what you need without requiring any add-ins or subscriptions.
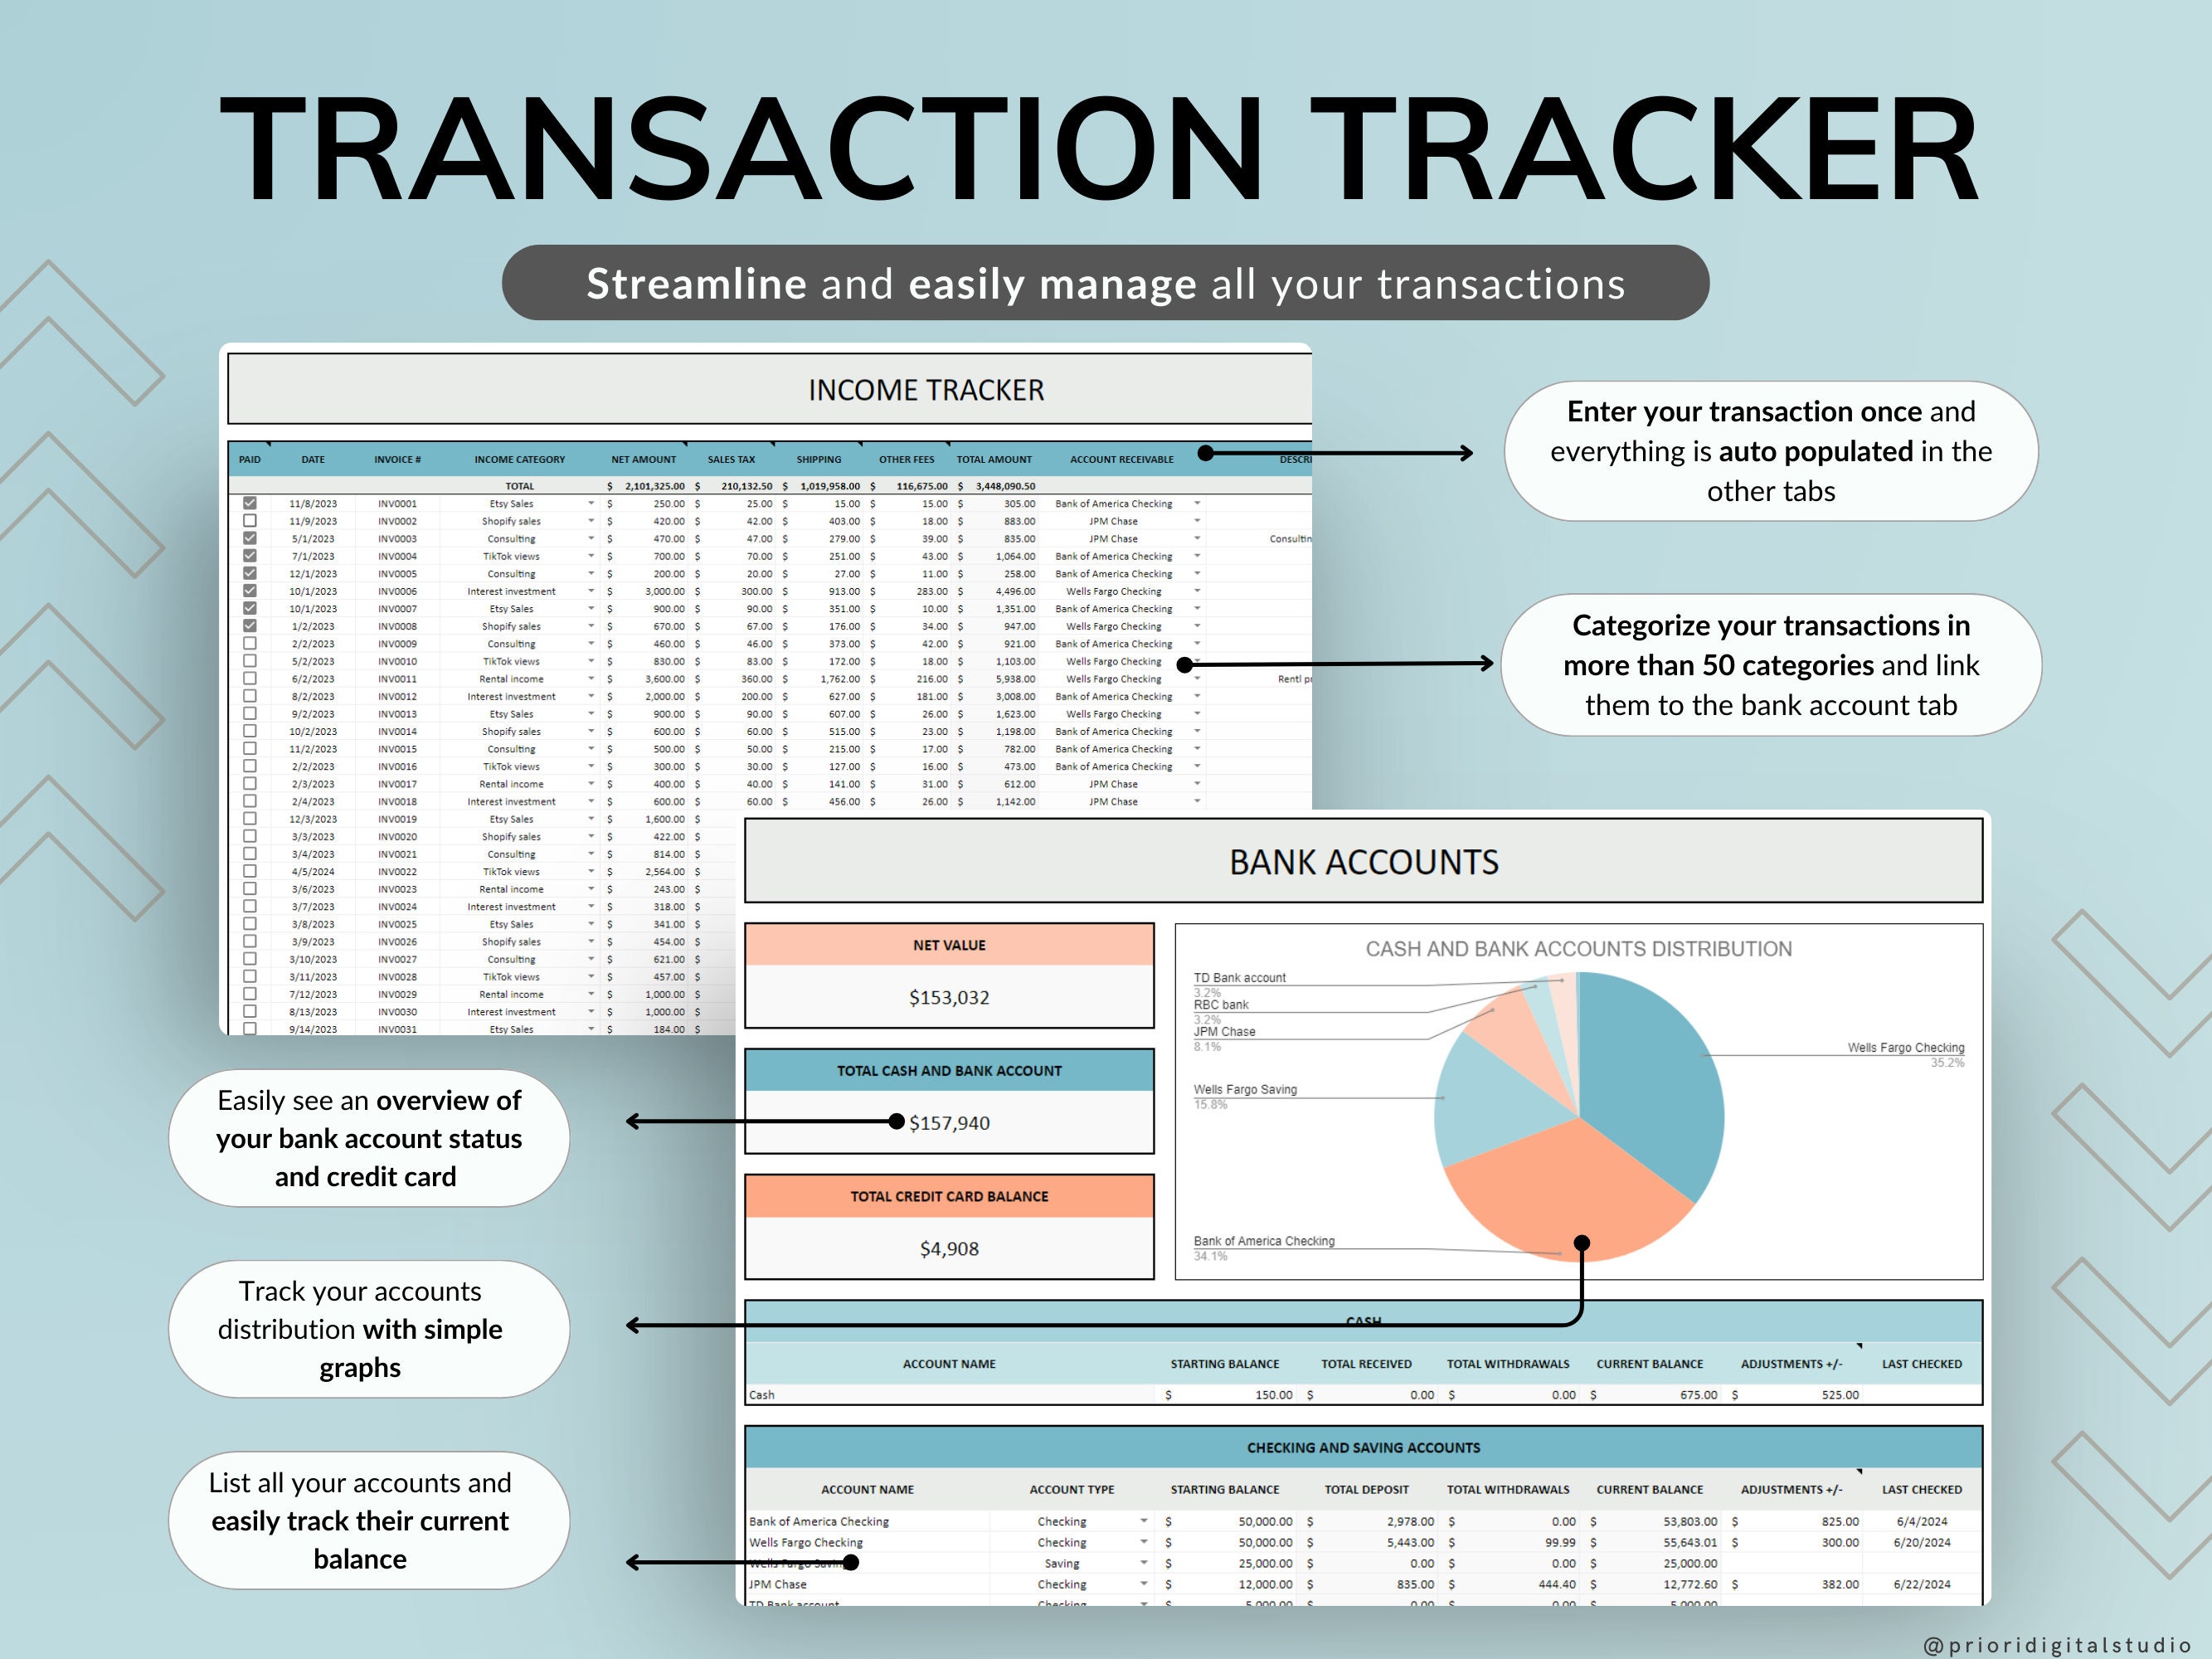
The third sheet is a reconciliation tracker, which I honestly did not think I would use but ended up relying on heavily. It lists each bank and credit card account, shows the ending balance per your statement, shows the ending balance per your spreadsheet, and calculates the difference. If the difference is zero, you are good. If it is not, you know immediately that something is off and you can dig in instead of finding out three months later during tax season.
How I Actually Built This
I started with a blank Google Sheets file because I wanted cloud access and the ability to share it with my accountant if something came up. The first version took me about six hours to set up properly, mostly because I was overthinking the category structure. I learned pretty quickly that you should keep categories broad at first and only subdivide when you actually notice a pattern that matters. For example, "Food" is fine. "Groceries" and "Restaurants" are worth splitting only if the numbers in those buckets are actually large enough to change your behavior. Once the basic structure was down, I added data validation dropdowns for the Category and Type columns. This prevents typos from breaking your SUMIFS later on. A single typo like "Transporation" instead of "Transportation" will silently throw off your entire category breakdown and you will not notice until you are looking at a chart that clearly does not add up. I have seen this happen to people way more experienced than me. For the reconciliation sheet, I used another SUMIFS to pull the running balance from the transaction log by account and date range. The formula references the main log and filters by the Account column. If your log has duplicate entries for the same transaction in the same month, your reconciliation will always be off by that amount. This is probably the single most common error I see when people try to set something like this up on their own.
Get the Full Details
The Thing Nobody Warns You About
Here is a specific problem I ran into that took me about two weeks to figure out. I was using the NOW() function in one of my cells to auto-fill today's date, and I had it set to recalculate on every edit. The spreadsheet would occasionally save a stale date value instead of the actual transaction date because the calculation would finish at a slightly different time than when I entered the data. It sounded minor but it caused real issues in my monthly summaries because transactions would get pushed into the wrong month boundary. The fix was simple once I understood it. I stopped using NOW() for dates entirely and instead used a dedicated input cell where I would manually type the date. I added a simple data validation rule that only accepted date formats, which prevented me from accidentally entering text. This alone cut down my end-of-month reconciliation time from about forty-five minutes to roughly twelve minutes. Another issue that caught me off guard: when you import bank CSV files into the spreadsheet, the date format from most banks is not standardized. Some export as MM/DD/YYYY, some as DD-MM-YYYY, and some as ISO format. If your spreadsheet interprets these inconsistently, half your transactions will end up in the wrong column and you will waste an evening chasing phantom discrepancies. I solved this by adding a helper column that standardizes the date format using the TEXT function, then referencing that helper column in all my summaries instead of the raw import column. This is a small step that saves a lot of frustration later.
When This Approach Breaks Down
Let me be blunt about where this system fails. It does not scale past roughly two to three bank accounts and maybe twelve to fifteen credit cards before the spreadsheet starts feeling sluggish, especially in Google Sheets. Once you cross that threshold, you are spending more time managing the tool than actually doing the accounting. At that point, you should move to something like QuickBooks Self-Employed or even a proper desktop accounting program. There is no shame in outgrowing a spreadsheet. Another limitation is multitab tracking. If you want to separate personal and business expenses in the same file, the complexity ramps up fast. You end up with conditional formatting rules that overlap, SUMIFS ranges that get enormous, and a high chance of accidentally referencing the wrong sheet in a formula. I tried this for about four months and just switched to separate files for personal and business. It is cleaner and the mental model is simpler. Collaboration is also weak here. Google Sheets allows multiple editors, but if two people edit the same row at the same time, you get weird overwrite behavior that is hard to trace. If you are working with a partner or an accountant who needs to make notes directly in the sheet, this can get messy fast. Version control is basically nonexistent outside of Google's built-in version history, and navigating that is not intuitive for most people.
Practical Tips From Someone Who Actually Uses This
Keep a backup copy exported to Excel format once a month. Cloud services fail, sheets get corrupted, and sometimes a rogue formula breaks an entire column. Having a local copy is insurance. I learned this the hard way when a spreadsheet sync error wiped about six weeks of manual entries and I only had the cloud version, which had already propagated the corruption. Use color coding sparingly. I see a lot of people go wild with conditional formatting and end up with a rainbow spreadsheet that is impossible to read. Green for reconciled, red for unresolved, yellow for flagged. That is enough. Anything beyond that is visual noise. Set a recurring reminder to reconcile at least once a week. Not monthly. Weekly. The longer you wait, the harder it is to remember what each transaction was for. I used to do monthly reconciliation and it would take me an entire Saturday to sort through everything. Once I switched to weekly, it became a fifteen-minute task that I could do on a Wednesday evening while having a drink.
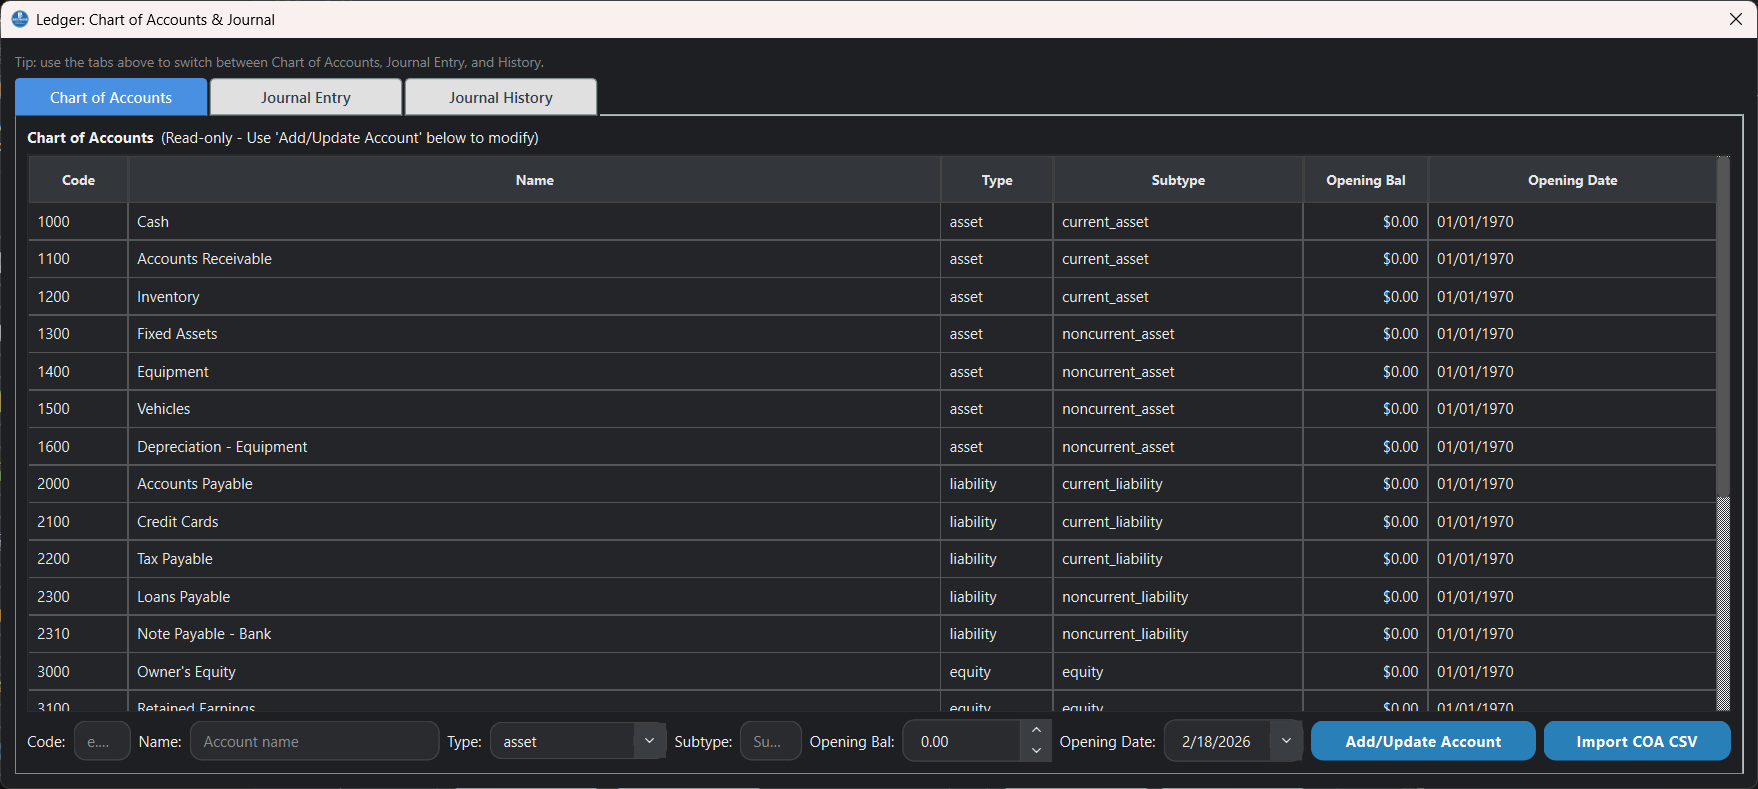
If you are doing this for a business, make sure your chart of accounts follows a numbering convention even if you do not plan to use accounting software. Something like 1000 for assets, 2000 for liabilities, 3000 for equity, 4000 for income, 5000 for cost of goods sold, and 6000 for expenses. This makes it trivially easy to migrate to proper software later if you ever need to. I have watched people spend hundreds of dollars on an accountant to restructure their categories after deciding to upgrade, all because they had no system in place.
Should You Build This or Buy Something?
If you are a sole proprietor or freelancer with fewer than three accounts and under five hundred transactions per month, this spreadsheet approach will serve you well. It is free, it is transparent, and you understand every number on the screen. If you have a team, multiple revenue streams, inventory to track, or more than about a thousand transactions monthly, you are better off paying for something like QuickBooks, Xero, or FreshBooks. The time you save will pay for the subscription within the first month. For most people reading this though, the spreadsheet route is the right call. It forces you to actually engage with your numbers instead of trusting a black box app to tell you how you are doing. That engagement is what changes behavior. I watched my own spending drop noticeably once I was manually categorizing every transaction instead of letting an app guess at it based on merchant names. The bottom line is that there is no perfect system, just a system that fits your current situation. Build the simplest version that does the job, use it consistently for sixty days, and then evaluate whether it is still working for you or whether you have outgrown it. That is the practical path most people miss because they either overcomplicate it at the start or they refuse to upgrade when they should.