Accounting Methods That Actually Determine Whether You Can Pay Your Bills
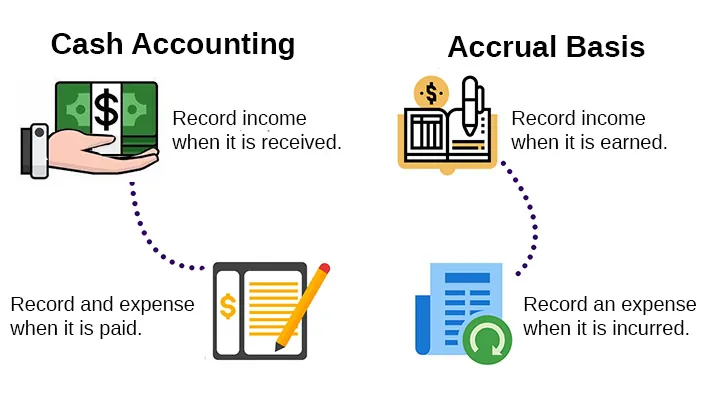
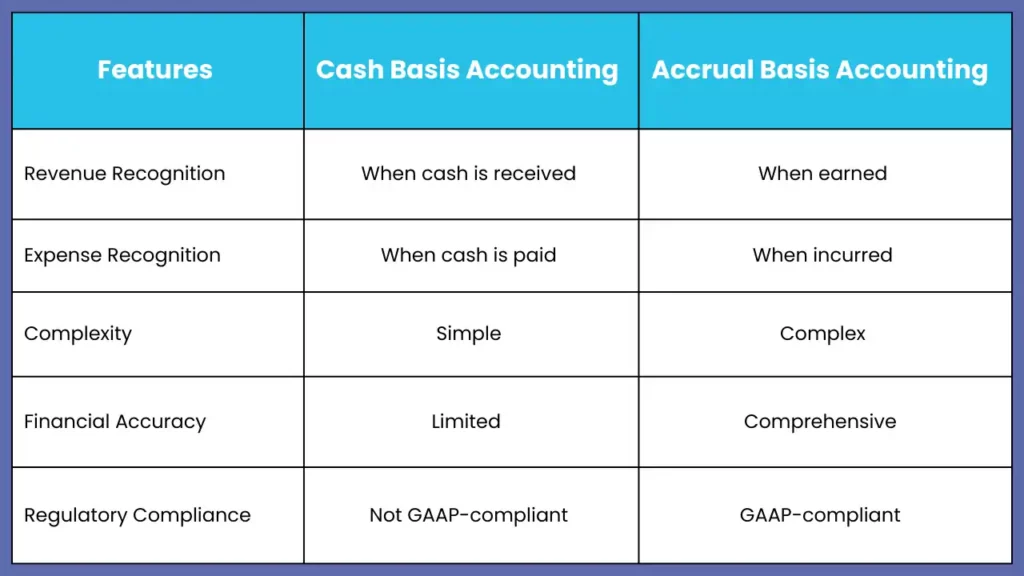
The way you recognize revenue and expenses changes everything about your financial picture. Most small business owners pick an accounting method without understanding what it actually does month to month. They set it and forget it, then get confused when their profit-and-loss statement doesn't match their bank balance. Cash basis accounting records transactions only when money actually changes hands. You invoice a client in March, they pay you in May, and on your books that revenue appears in May. Simple. Clean. The expense side works the same way - when you pay the bill, it hits your expenses. Accrual accounting recognizes revenue when it's earned and expenses when they're incurred, regardless of when cash moves. You deliver the service in March, record the revenue in March, and track the receivable until the customer pays. Matching revenue to the period it was earned gives you a different view of profitability.
The mismatch between these two methods shows up most aggressively in businesses with long sales cycles or significant outstanding invoices. A consulting firm might show $80,000 in revenue on an accrual P&L for Q1 while collecting only $35,000 in actual cash. On cash basis, that same quarter shows $35,000. Both numbers are technically correct depending on which method you use. I ran into a specific problem with a manufacturing client last year. We were switching from cash to accrual for a loan application, and the accounts receivable aging report showed $120,000 in outstanding invoices that never made it onto their annual tax return. Their CPA had been preparing cash basis returns for six years without ever flagging that their accrued revenue exceeded 40% of total reported income. The workaround was rebuilding the AR sub-ledger from invoice dates and cross-referencing payment dates, which took about three weeks of manual reconciliation. One thing most people miss about cash basis is that it creates a false sense of financial health during high-revenue months. You collect $50,000 from a client in December for work done over November and December, and your P&L shows a December that looks incredible. But that cash represents work performed across two months. You can't budget against that pattern. It skews your quarterly planning and makes it difficult to forecast accurately.
On the accrual side, the hidden complexity comes from bad debt estimation. When you recognize revenue upfront, you need to estimate how much of it will actually convert to cash. The allowance method requires periodic review of your collection history and adjustment of your reserve. I've seen businesses consistently under-reserve by 2-3% because they assumed their collection rates would stay stable. They don't. Economic shifts, client bankruptcies, and payment term changes all hit your allowance account. Cash basis has real limitations that people don't talk about enough. You cannot reliably determine gross margin on individual projects because expenses get recorded whenever you pay them, not when the related revenue was earned. If you pay a subcontractor in January for work completed in November, your November project margin looks artificially high and your January margin looks artificially low. This makes project profitability analysis nearly impossible on pure cash basis. The IRS requires accrual accounting if your business meets certain thresholds. Currently, average annual gross receipts exceeding $29 million (for tax years beginning in 2025) generally triggers the requirement. Businesses above that threshold must use accrual for inventory and can't use cash basis for most revenue recognition. There are exceptions for qualified personal service corporations, but those have their own narrow definitions.
Get the Full Details

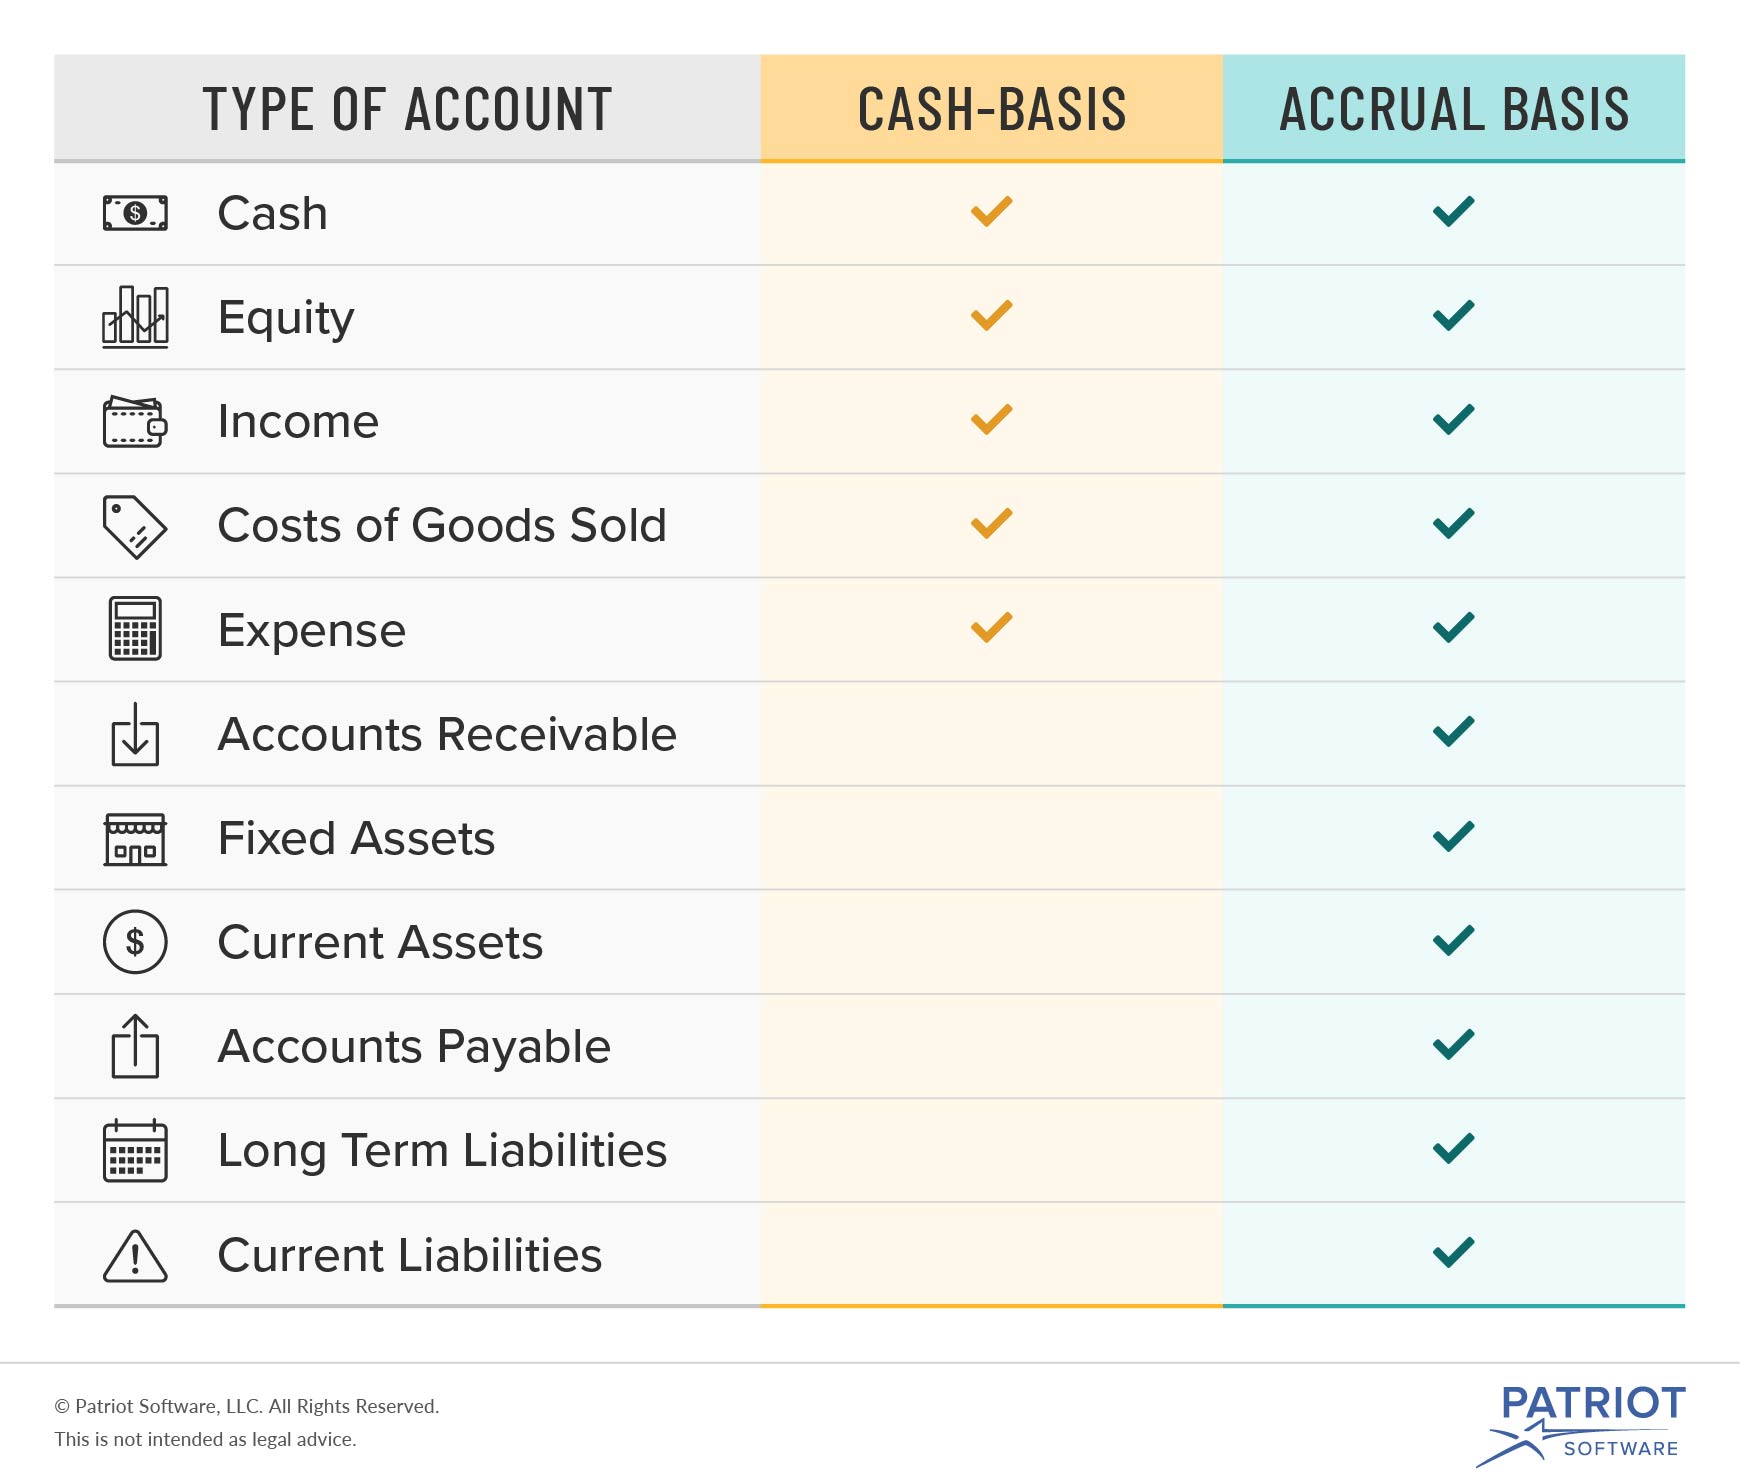
If you're deciding between methods for your own situation, start by looking at your receivables and payables turnover. If you routinely carry outstanding invoices beyond 60 days, cash basis is hiding material information from you. If you pay suppliers quickly and collect from customers within 30 days, the difference between the two methods is probably small enough that cash basis simplicity wins out. Sales tax handling also behaves differently under each method. Under cash basis, you collect and remit tax when payment arrives. Under accrual, you may need to account for tax on invoices before you've actually received the money. This creates a timing gap where you're paying sales tax to the state on revenue that hasn't hit your bank account yet. Make sure your tax software accounts for this if you're accruing. Payroll processing is another area where the methods diverge. Accrual accounting requires you to record payroll expense in the period employees worked, including accrued but unpaid wages at period end. Cash basis lets you record everything when you actually cut the checks. That end-of-period accrual for wages earned but not yet paid is where most beginners make mistakes. A two-week delay in recording that entry can materially distort your monthly P&L.
There's no universal best method. The right choice depends on your revenue recognition patterns, your reporting requirements, and how much operational overhead you want to absorb. Many businesses start on cash basis, switch to accrual when they need it for financing or compliance, and then never go back. The transition itself is usually the hardest part because you're essentially catching up several months of deferred recognition all at once.