Understanding the Process
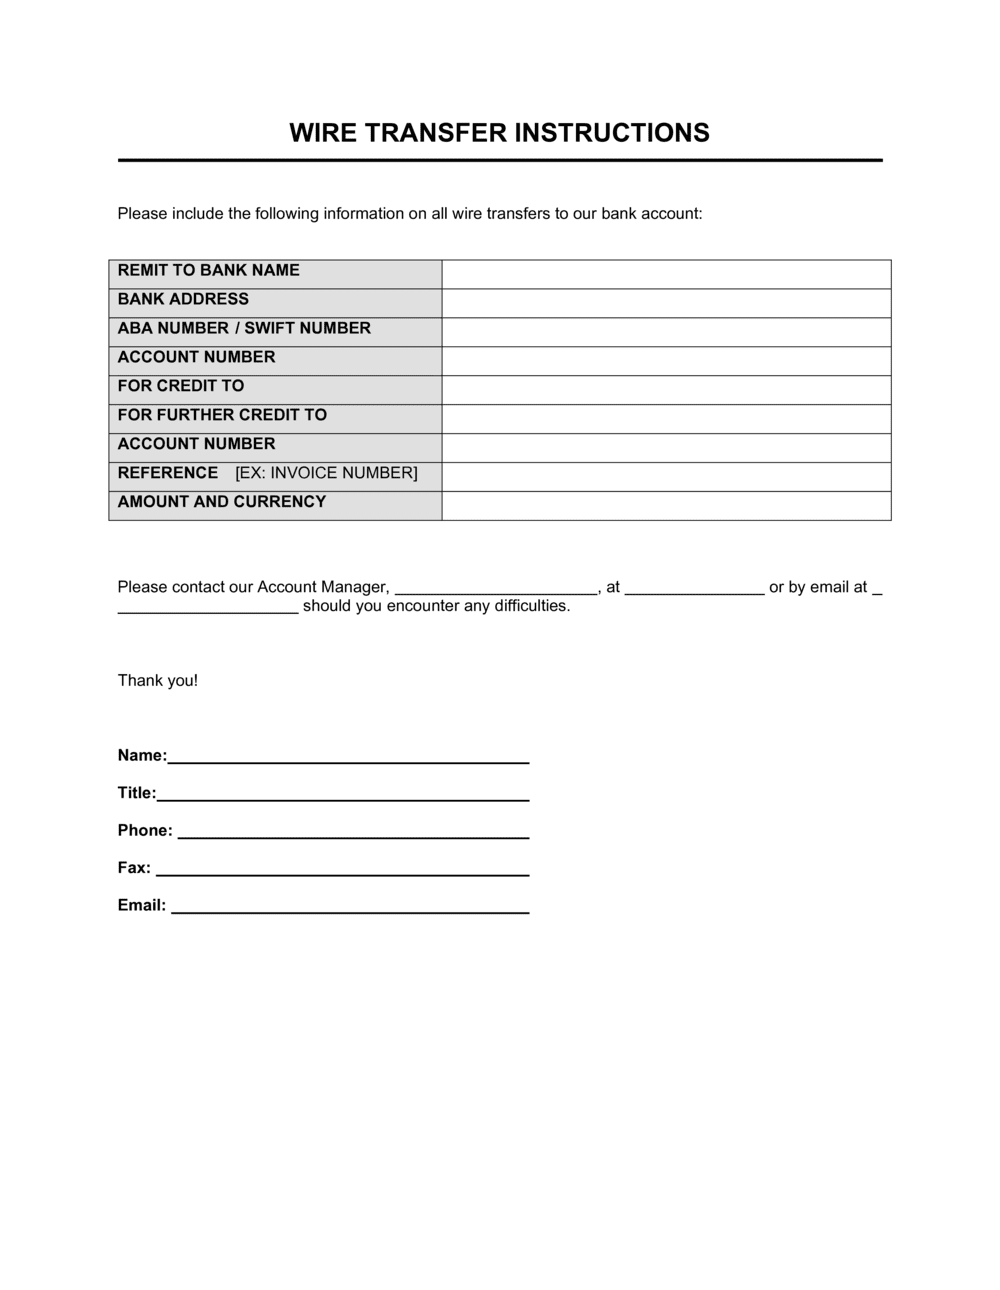
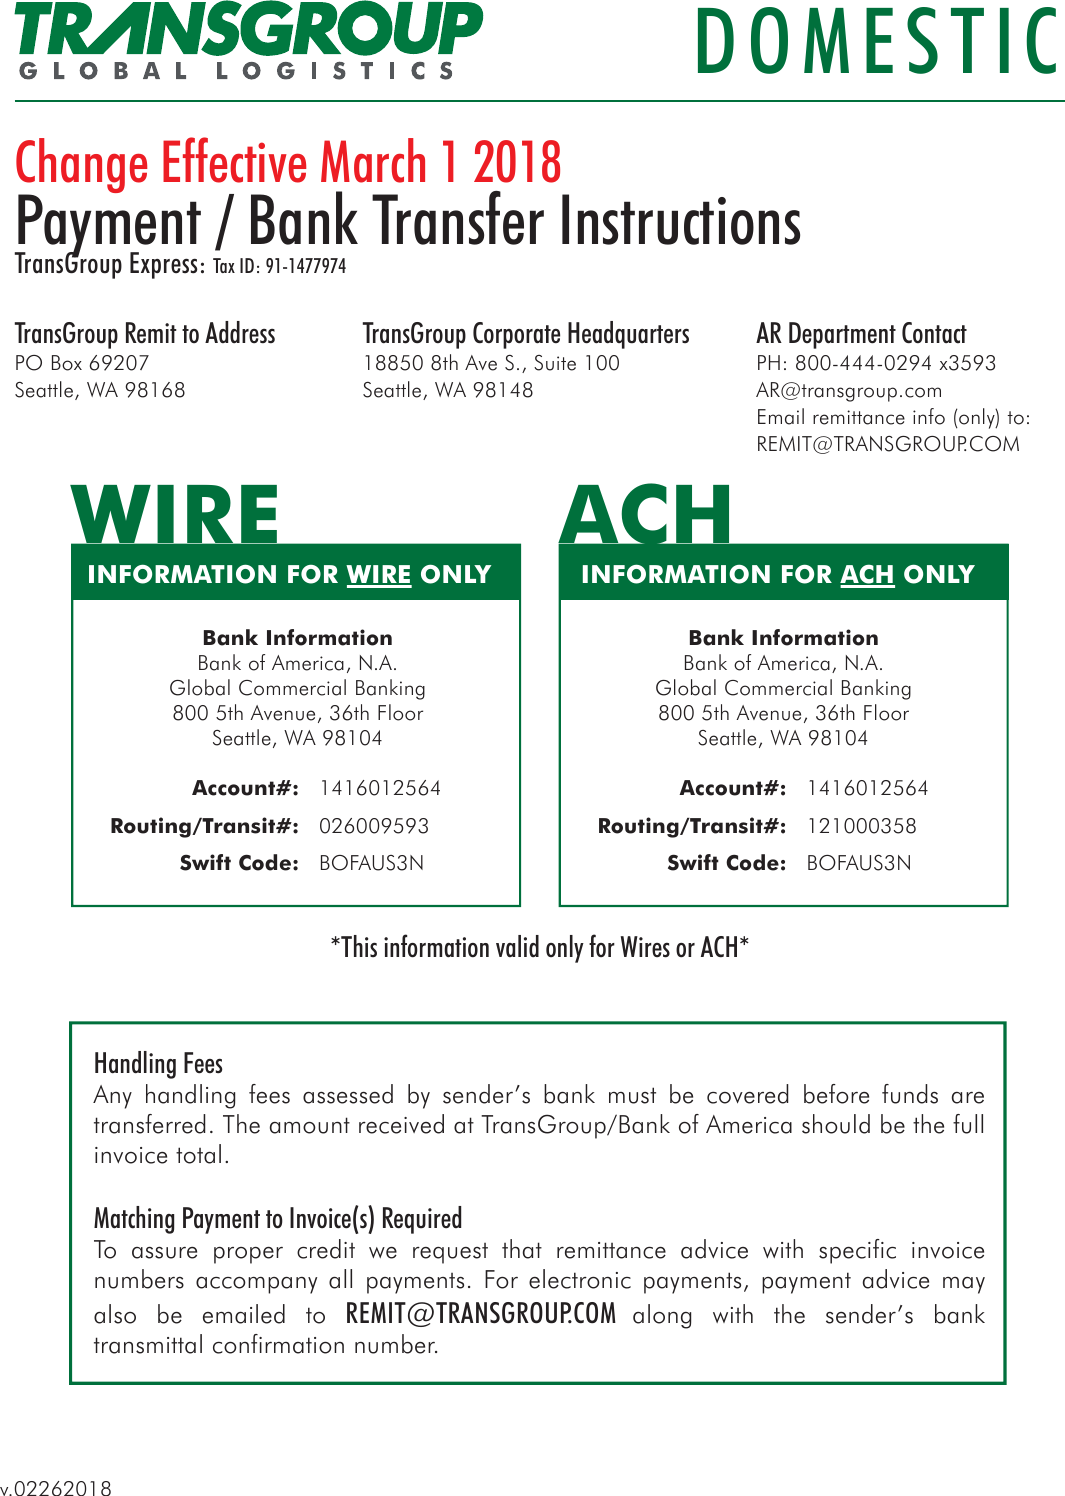
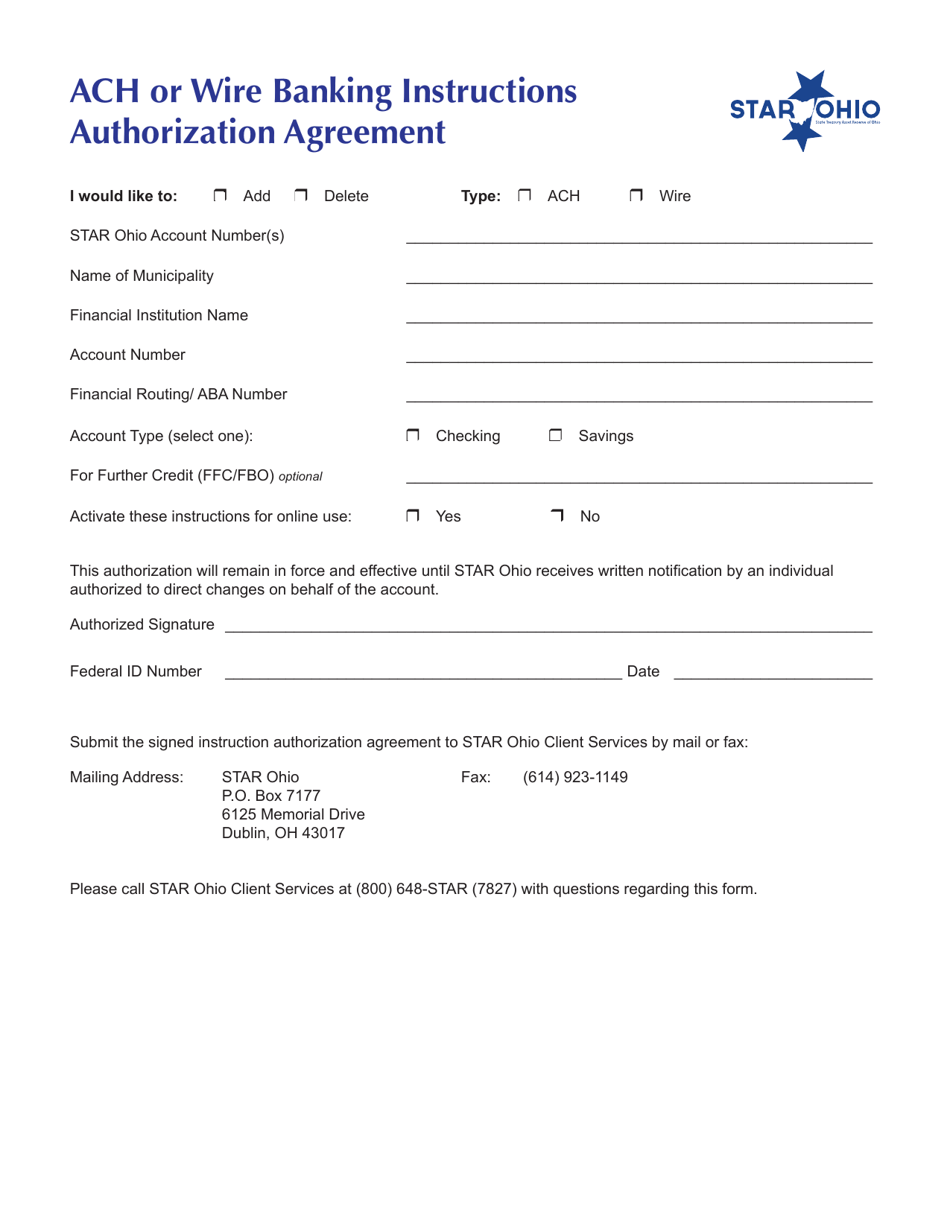
Ach wire transfer instructions are the set of details you need to move money between bank accounts using the Automated Clearing House network. It is not the same as a same-day wire through Fedwire. ACH transfers settle differently, and that difference matters if you are trying to understand timing or costs. You will need a routing number, an account number, the account type, the amount, and whether it is a one-time payment or a recurring setup. Most banking portals ask for all of that in a single form. The fields are usually straightforward unless you are dealing with international ACH, which adds SWIFT codes and extra compliance questions.
How to Use Ach Wire Transfer Instructions
I spent about an hour last month untangling a batch of vendor payments because one supplier had given me a routing number that looked right but belonged to a different bank branch. ACH routing numbers are nine digits, and the last two can indicate the specific institution location. If the number on your instruction sheet does not match the bank's primary routing number, the transfer will either fail or sit in limbo for a few days. Here is what I do now before submitting anything. I verify the routing number against the Federal Reserve's public lookup tool. Then I call the receiving bank's support line and confirm the account is active and accepting ACH credits. That call usually takes three minutes and saves me from chasing a rejected payment later. When you submit an ACH transfer, most banks give you a confirmation number immediately. You should screenshot or save that number. The processing timeline is typically one to three business days for standard ACH. Same-day ACH is available from most institutions now, but it usually requires the request to be submitted before a cutoff time, often around 2:00 p.m. local time depending on the bank.
The downside is that ACH is not instantaneous, and once you submit a credit, reversing it is difficult. You cannot just click undo. If you send money to the wrong account or the wrong amount, you have to file an ACH reversal request with your bank, and the receiving bank has to agree to return the funds. That process can take five to ten business days, and there is no guarantee it will be approved. For time-sensitive payments, I switch to wire transfer instead of ACH. The fees are higher, usually between fifteen and thirty dollars per transaction, but the money moves within hours and the reversal process is more straightforward because the funds are already settled. If you need payment certainty and speed, wire is the better option despite the cost. Most online banking platforms let you save ACH instructions for repeat payees. I recommend doing this only after the first transfer clears successfully. I learned that the hard way when a company saved an old routing number and kept sending payments there for two months before anyone noticed it was outdated. The transfers were being rejected silently by the receiving bank, and the vendor never received the money. By the time I caught it, we were behind on three separate invoices.
Get the Full Details

If you are setting up ACH for payroll or recurring bills, make sure your bank offers positive pay verification or a similar fraud check. Some institutions let you set a daily or per-transaction limit on ACH debits, which is useful if you are pulling payments from customer accounts. Without that guardrail, a single wrong entry can pull significantly more than intended. The instructions themselves are not complicated. You enter the routing number, account number, account type, and amount. You review everything once before confirming. You save the confirmation. That is basically it. The things that go wrong are usually human errors like transposed digits or using the wrong routing number for the specific branch.