What actually happens when two companies merge or one buys another
The Acquisition And Merger Process isn't one thing. It's a sequence of phases that overlap, loop back, and frequently derail because someone missed a detail three weeks ago. I've watched deals die in due diligence because a single lease had an assignment clause that required landlord consent, and that landlord was a municipal authority that took six months to respond. The process itself is straightforward on paper. Execution is where it falls apart. Here is how it works, not how the textbooks describe it.
Acquisition And Merger Process: the real sequence
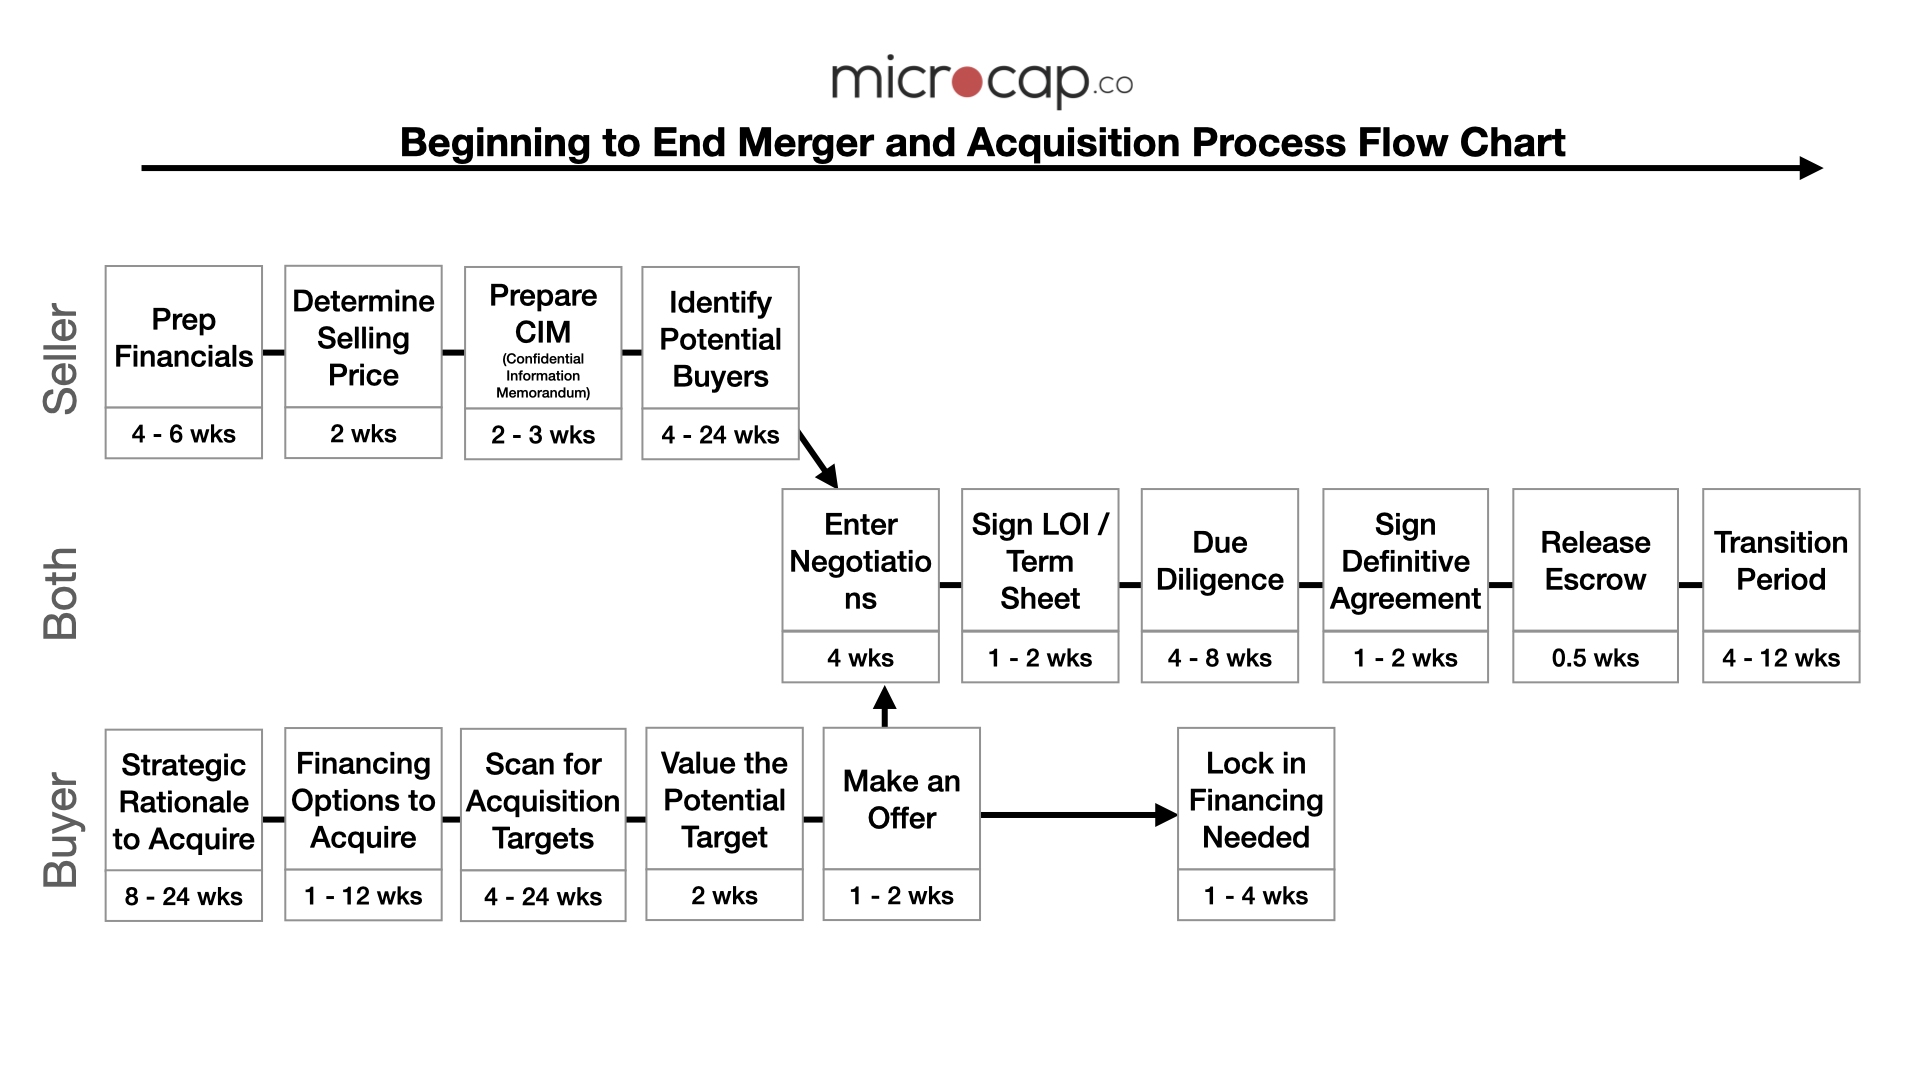
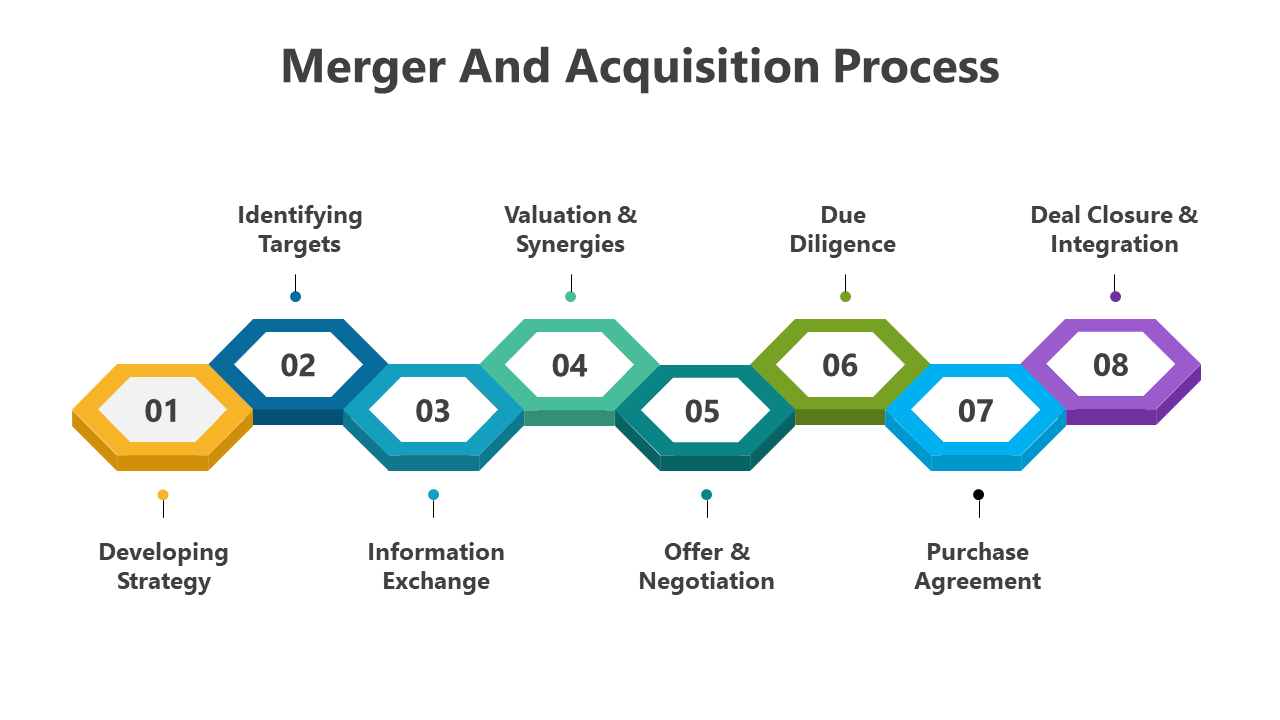
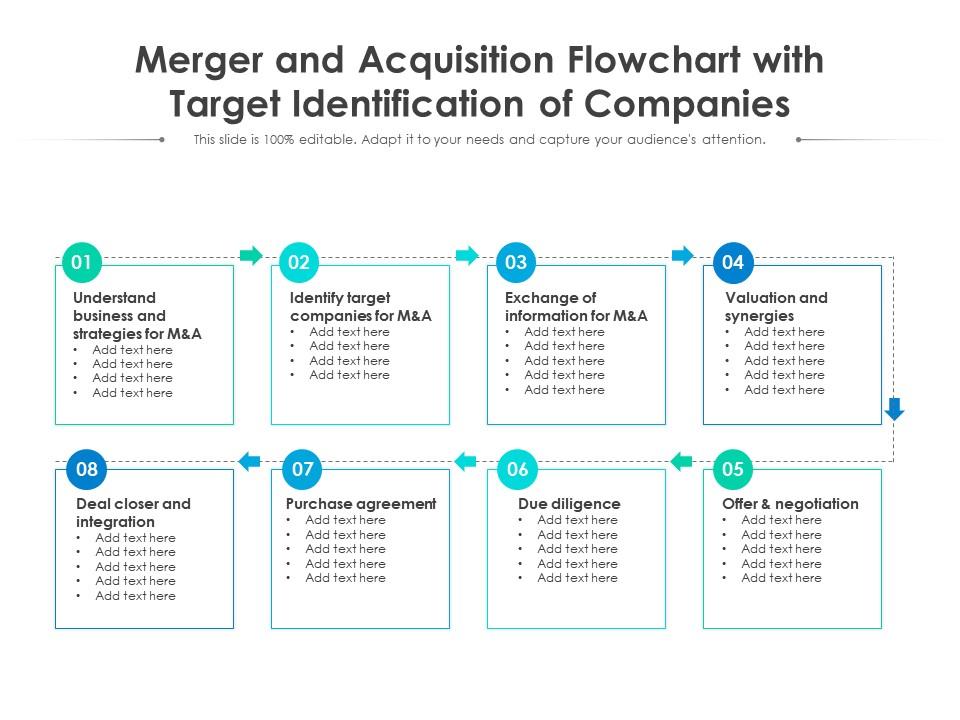
Phase one is strategy and target identification. This sounds easy until you realize most companies have no clear criteria for what they're looking for. They know they want growth. They don't know what kind of growth, at what multiple, in which geography, with which cultural fit. I worked on a deal where the acquirer wanted a company with recurring revenue above 70 percent, but the target's revenue was 62 percent recurring and growing. The board killed the deal because it didn't hit the threshold, even though the gap was seven percentage points and the trajectory was favorable. The criteria were set too rigidly without thinking about whether the underlying business was sound. Phase two is outreach and NDA. You send a confidential information request. The target's legal team sends back a 40-page NDA with provisions you haven't seen in years: mutual injunctive relief, broad definitions of confidential information that swallow public data, and a term that extends beyond the life of the deal itself. You negotiate it down. This usually takes two to four iterations. If you're the buyer, push for a one-way NDA that limits your obligations. If you're the seller, insist on mutuality or the buyer will walk away from competitors who do. Phase three is due diligence. This is where deals go to die. Financial, legal, operational, technical, commercial. Each workstream runs in parallel. Financial due diligence verifies the numbers. Legal checks contracts, litigation, IP ownership, employment matters. Operational looks at supply chains and key dependencies. Technical assesses the codebase or machinery. Commercial validates the market position and customer concentration.
I once spent three weeks on a technical DD that uncovered the target's core product ran on a proprietary database engine built by a single consultant who had left the company eighteen months earlier. No documentation. No source code backup. The license was perpetual but non-transferable. The acquisition was worth roughly zero from a technology standpoint. We flagged it. The deal was restructured around the customer relationships instead, at a 60 percent discount. That's the kind of thing that doesn't show up in any summary deck. Phase four is valuation and negotiation. You have three main methods: comparable company analysis, precedent transactions, and discounted cash flow. Each gives a different number. The art is in the blend. DCF is sensitive to assumptions about terminal value and discount rate. A one percent change in WACC can swing the valuation by twelve to fifteen percent on a typical mid-market deal. Comparable analysis depends on finding truly comparable companies, which is rare. Precedent transactions reflect past market conditions that may no longer apply. Phase five is definitive agreement. The SPA or merger agreement is where everything gets locked in. Representations and warranties, covenants, conditions precedent, indemnification, escrow. The reps and warranties section alone can be eighty to one hundred fifty pages. Indemnification caps typically run from ten to twenty percent of deal value. Escrow periods are six to twenty-four months. These are negotiation points, not boilerplate.
Get the Full Details

Phase six is closing and integration. Closing is usually a formality if the due diligence was thorough. Integration is where the value is created or destroyed. Employee retention, system migration, brand consolidation, customer communication. Studies consistently show that 70 to 90 percent of mergers fail to achieve their projected synergies. The failure is rarely strategic. It's operational. People leave. Systems break. Culture clashes erode productivity for quarters.
Common pitfalls and what to do about them
Overpaying because of competitive tension. When two buyers are in the room, the price inflates. Bid walls are real. I've seen a $40 million deal inflate to $58 million in a two-bidder auction, with the second buyer only marginally improving on the first offer. The winner pays a control premium that the target's performance never justifies. The workaround is setting a hard walk-away number before you enter the auction and sticking to it. Emotional attachment to a deal is the fastest path to value destruction. Underestimating integration complexity. Companies budget integration at two to five percent of deal value. The actual cost is often double that. ERP migrations alone can consume thirty to sixty percent of the integration budget on tech deals. The fix is to start integration planning during due diligence, not after signing. A dedicated integration team should be in place before the deal closes, not after. If you're waiting for closing to assemble the team, you've already lost months. Ignoring regulatory risk. Antitrust review has gotten stricter globally. The FTC and DOJ in the United States, the European Commission, and competition authorities in Asia are all more aggressive about blocking deals. A horizontal merger between two companies with combined market share above twenty-five percent in a concentrated market will face scrutiny. The workaround is a preliminary regulatory assessment before you commit serious resources. A basic Hart-Scott-Rodino filing analysis takes about a week and can save three to six months of wasted effort.
Not validating key person dependency. If the target's revenue depends on three salespeople who are likely to leave after the acquisition, you have a problem. The acquisition creates uncertainty that drives departure. The mitigation is retention agreements with clawback provisions, structured over two to three years. Budget for this. It typically costs ten to twenty percent of the key people's compensation package.
When the process breaks down completely
There are scenarios where acquisition and merger process simply cannot produce a good outcome. If the target's financials are unreliable — and I mean genuinely unreliable, not just aggressive — the deal should not proceed. I've seen companies attempt DD on targets with commingled personal and business accounts, missing tax filings for two years, and revenue recognition that violated basic accounting principles. No amount of diligence framework fixes that. Walk away. Similarly, if the cultural mismatch is severe and neither side is willing to adapt, the deal will create more friction than value. This doesn't show up in financial models. It shows up in the first ninety days post-close when key talent starts resigning and productivity drops. Cultural assessment during due diligence is often treated as a soft topic. It shouldn't be. It's one of the strongest predictors of post-merger performance. The process itself is a tool. It reduces uncertainty. It doesn't eliminate it. The best deals I've been involved in weren't the ones where everything went perfectly. They were the ones where the risks were identified early, priced into the deal, and managed deliberately. The worst deals were the ones where everyone assumed the standard process would catch the problems, and it didn't.