Acquisition Assessment Questions: A Practical Guide
I have sat through more acquisition assessments than I care to count. The process is usually messy, under-resourced, and done in a way that looks organized from the outside but is practically held together by spreadsheets and hope on the inside. The core problem is not that Acquisition Assessment Questions are missing. They are plentiful. The problem is that people ask the wrong ones, or they ask the right ones at the wrong time, and then they ignore the answers. Acquisition Assessment Questions are the structured set of inquiries a buyer or investor uses to evaluate the viability, risks, and strategic fit of a target company before committing capital. They span financial, operational, legal, technological, cultural, and market dimensions. That is the textbook definition. Here is what happens in reality. The financial questions are the easiest. Revenue quality, margin sustainability, working capital normalizations, debt structure, customer concentration, contract renewals, churn rates. These numbers are usually available if the target company is cooperative. The hard part is figuring out whether the numbers tell the whole story. I worked on a mid-market software acquisition where the target reported ARR of $18 million. On the surface, clean. When we pulled the actual revenue recognition details and traced it back to signed contracts, we found that roughly 30% of that ARR came from bundled services revenue that was being recognized upfront rather than amortized over the service period. That changed the EBITDA picture considerably. The assessment questions had asked about ARR quality. The answer they got was technically correct but practically misleading.
Where People Go Wrong With These Questions
Most assessment frameworks are built around questions that can be answered with a spreadsheet. That is a fundamental design flaw. The things that actually kill acquisitions are rarely in the revenue model. They are in the areas that do not fit neatly into a data room folder. Things like key-person dependency, undocumented technical debt, regulatory exposure that has not yet triggered enforcement, and cultural misalignment that only becomes visible after the deal closes. I once evaluated a logistics acquisition where the target had three regional distribution centers and claimed operations were run by standardized SOPs. The financials looked fine. The assessment question asked about operational scalability, and the answer was yes, easily. But when I walked through one of the smaller distribution sites with the shift supervisor, it turned out that the entire routing optimization logic lived in one person's head. That person had been there for twelve years and had never documented the methodology. He left two weeks after we signed. The acquisition lost approximately $4.2 million in the first quarter after close because the routing system collapsed. The Assessment Questions had covered operations thoroughly. They had just not asked the right version of the question. The workaround I use now is simple but unglamorous. For every standard assessment question, I add a corresponding verification step that requires evidence beyond a verbal or document-based answer. If the question is about operational scalability, the verification is a site visit with an unscripted conversation with frontline staff. If the question is about technology debt, the verification is not a review of the architecture diagram but a review of the last six months of incident reports and the actual cycle time between commit and deploy. Evidence trumps assertions every time.
A Practical Framework for Building Your Own Assessment
Start with the strategic rationale. Every assessment question should trace back to a specific reason the buyer believes this acquisition creates value. If you cannot state the value thesis in one clear sentence, you do not have enough discipline to design the assessment. Common value drivers include market expansion, capability acquisition, cost synergies, and talent acquisition. Each driver requires a different question set. For market expansion, your primary questions focus on customer overlap, channel conflicts, and regulatory barriers in the new geography. For capability acquisition, you ask about IP ownership, development velocity, and whether the capability is replicable or uniquely tied to the target team. For cost synergies, you dig into duplicate functions, real estate consolidation, and vendor contract portability. For talent acquisition, you assess retention risk, compensation band gaps, and cultural integration complexity. Here is a counter-intuitive point that most people miss. The most valuable Assessment Questions are the ones that could disqualify the deal. Most teams treat due diligence as a process to validate a decision that has already been made emotionally. The best assessors build in kill switches. These are specific criteria where a negative answer automatically stops the process unless there is a compelling mitigation plan. Examples include customer concentration above 25% of revenue from a single client, any material litigation that is pending or threatened, key technology that is built on a deprecated platform with no migration path, or a founding team that refuses to stay post-close.
Get the Full Details
I find that people resist kill switches because they feel like they are building a framework to fail. They are not. A kill switch saves you three months of work and six figures in advisory fees when the target turns out to be a bad fit. It is cheaper to disqualify in week two than in week twelve.
Technical and Legal Assessment Questions
The technical portion of an acquisition assessment is where most mid-market deals go off the rails. Standard questions cover technology stack, architecture documentation, data security practices, and IP ownership. These are necessary but insufficient. The question nobody asks is whether the technology can actually be maintained by the buyer's existing team after the acquisition. I have seen buyers acquire companies for their engineering talent and then realize six months later that the codebase was written in a framework their team could not read, with no documentation and no onboarding path. My recommendation for the technical assessment is to include a practical coding exercise or architecture walkthrough led by someone who will actually inherit the system. Not a senior architect doing a high-level review. Someone from the team that will maintain it. If they cannot understand the code structure after a two-hour session, you have a problem that no amount of documentation will fix. Legal questions are usually handled by counsel, which is appropriate. But the commercial terms in those legal answers often get ignored by the deal team. A restrictive non-compete clause, an exclusive licensing agreement that limits the target's ability to serve certain customers, or a change-of-control provision that triggers on acquisition. These are the clauses that quietly erode the value thesis. I always ask counsel to summarize the top five contractual restrictions in plain language before the legal review is complete. If the summary alone raises red flags, the full legal diligence will confirm them, and you save time by flagging early.
Cultural and Human Capital Assessment
This is the area most acquirers get wrong. The standard approach is a survey or a couple of interviews with leadership. The cultural reality of a target company cannot be assessed through a formal survey administered by HR. People will give you the answer they think you want to hear. The actual culture is visible in informal patterns: how decisions are made without a meeting, how conflict is handled, how information flows between departments. I spent a day embedded with a target team before an acquisition we ultimately walked away from. I did not conduct formal interviews. I sat in on their standup, ate lunch with the engineering team, and watched how they communicated with each other during a minor incident. The assessment revealed a culture of avoidance. Problems were escalated silently rather than discussed openly. Leadership was unaware of the scale of the issue. We declined the acquisition. Three months later, a major incident occurred that could have been prevented with earlier communication. The culture assessment worked as intended. For cultural assessment, consider including an unstructured observation component alongside traditional surveys and interviews. The observation does not need to be elaborate. A few hours of presence in the workplace, watching how people interact, is often more informative than a hundred survey responses.
Common Pitfalls and Limitations
The biggest limitation of any acquisition assessment framework is the time pressure. Deals are won and lost based on speed. Assessment teams are often asked to deliver comprehensive due diligence in four to six weeks. This compresses the process into a checklist exercise. Questions are asked but not thoroughly verified. Gaps are assumed to be minor because there is no time to investigate them. This is where deals go bad. Another pitfall is the over-reliance on the target's data room. Data rooms are curated. They contain the information the seller wants you to see and omit the information that would complicate the narrative. I have encountered targets that deliberately delayed producing certain documents until the final stage of due diligence, knowing that the buyer would not have time to verify them. The workaround is to request documents in sequential phases and treat any delays or resistance as a signal rather than an inconvenience. A third limitation is the assumption that the target's financial projections are baseless optimism. They usually are, but not always. The real question is whether the assumptions behind the projections are testable. If a target projects 40% growth based on a new product launch, the assessment should include a review of the product development timeline, the beta customer feedback, and the sales pipeline for the new product. If those pieces exist and are credible, the projection may be reasonable. If they do not exist, the projection is fiction. Distinguishing between the two is the entire point of the assessment.
What the Assessment Should Tell You to Walk Away
No assessment framework can predict every failure mode. The goal is not to eliminate risk. The goal is to make informed decisions about which risks are acceptable and which are not. Some risks are structural and cannot be mitigated. A target with a single customer representing 35% of revenue presents a structural risk that no amount of diligence can remove. A target whose core technology is three years behind the market standard presents a structural risk that synergies cannot fix. My rule is straightforward. If the assessment reveals a structural risk that undermines the primary value thesis, walk away. Do not renegotiate the price to compensate for a structural problem. Price adjustments fix financial gaps. They do not fix strategic mismatches. I have seen acquirers lower the purchase price by 20% to account for customer concentration risk and then spend the next two years trying to diversify the revenue base. The better outcome would have been to decline the deal in the assessment phase.
A Note on Tools and Templates
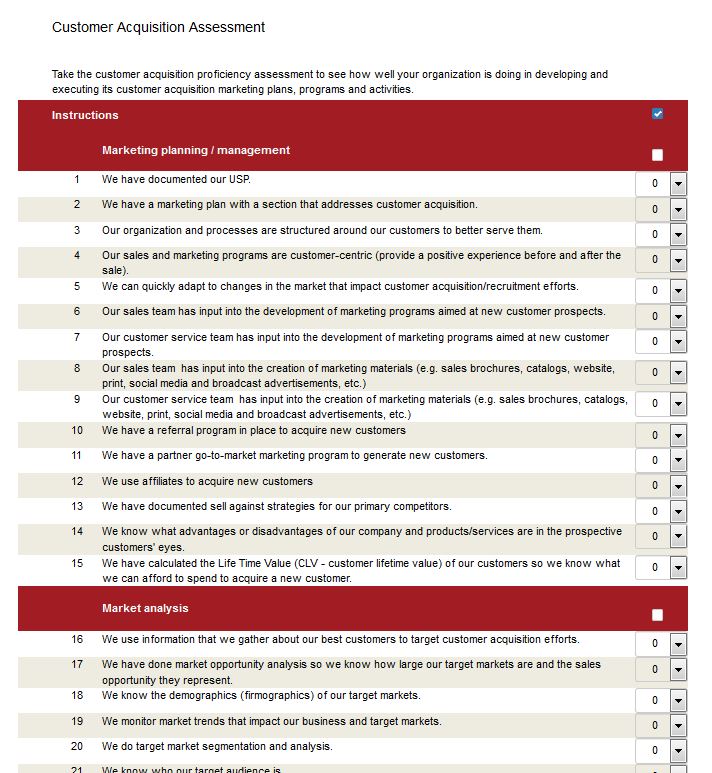
There are commercial templates available for acquisition assessment questions. They are useful as a starting point but inadequate as a complete framework. Most templates are generic and designed for broad applicability rather than specific deal contexts. A template will list questions about revenue, margins, and customer concentration. It will not ask about the undocumented routing logic in a logistics company or the silent escalation culture in a technology team. The value of an assessment framework is in the customization, not the template. If you are building your own framework, start with a standard template, strip out the questions that are irrelevant to your deal type, and replace them with questions derived from the specific value thesis and industry context. The process takes about two hours for a typical mid-market deal. The result is significantly more useful than any off-the-shelf template.
The Bottom Line
Acquisition Assessment Questions are only as good as the discipline with which they are asked and verified. The framework matters less than the willingness to follow evidence wherever it leads, even when that evidence points toward declining the deal. The most expensive acquisitions are not the ones that fail because of unexpected risks. They are the ones that proceed despite obvious risks because the assessment was treated as a formality rather than a genuine evaluation. Treat it like the latter and you will avoid the majority of post-close surprises.