What This Actually Does
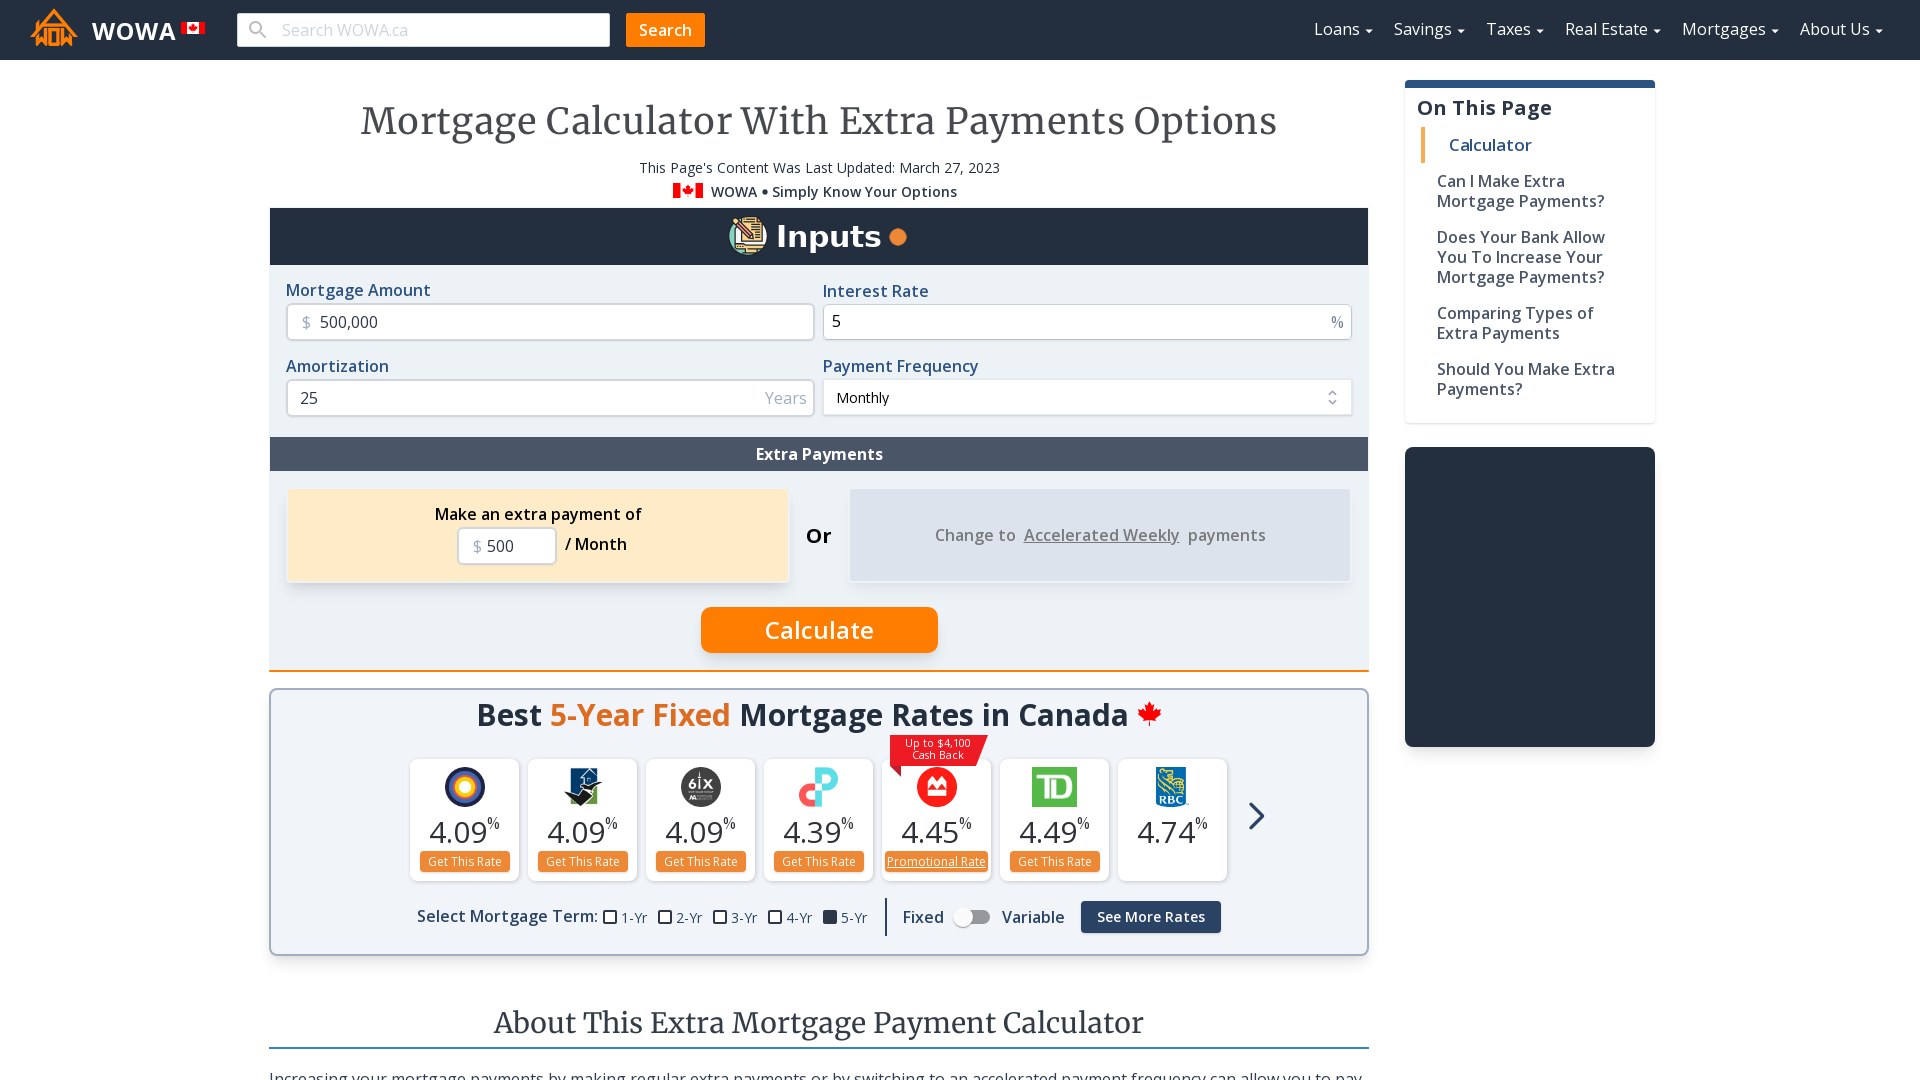
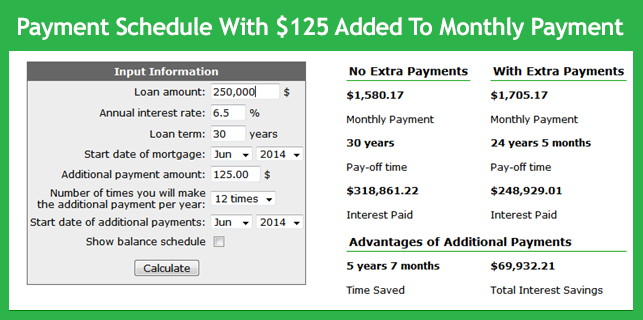
An Additional Mortgage Payment Calculator shows you what happens when you pay more than your required monthly amount. It takes your principal, interest rate, and remaining term, then calculates how much extra you'd need to throw at the loan to reach a specific goal. That goal is usually paying off the loan faster or shaving years off the term. Some people also use it to see how much they could save in total interest. You can build one yourself in a spreadsheet or use a free online tool. The inputs are straightforward: current balance, annual interest rate, remaining months, and the extra payment amount per month. The formula behind it is based on the amortization schedule. Each payment gets split between interest and principal. When you add extra money, it all goes toward principal immediately, which reduces the next interest calculation. That's the compounding effect that makes extra payments so powerful. I built mine in Google Sheets about eight years ago. Here's the practical breakdown of how to set it up if you want to do it yourself.
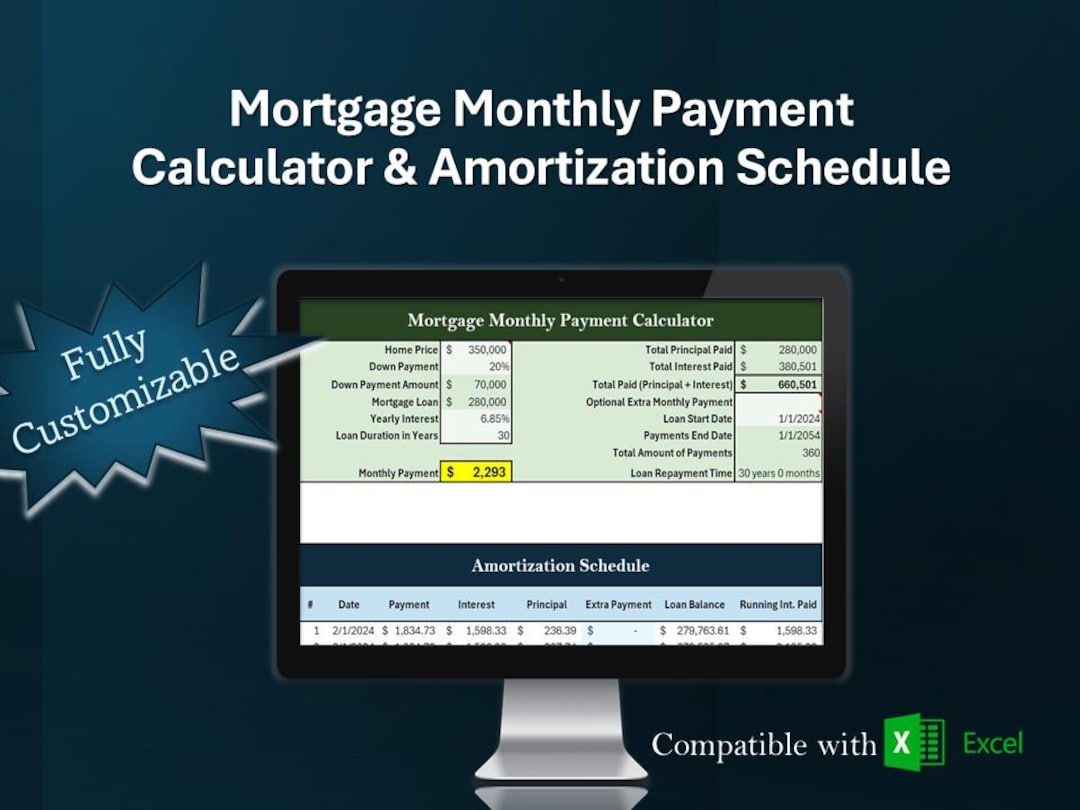
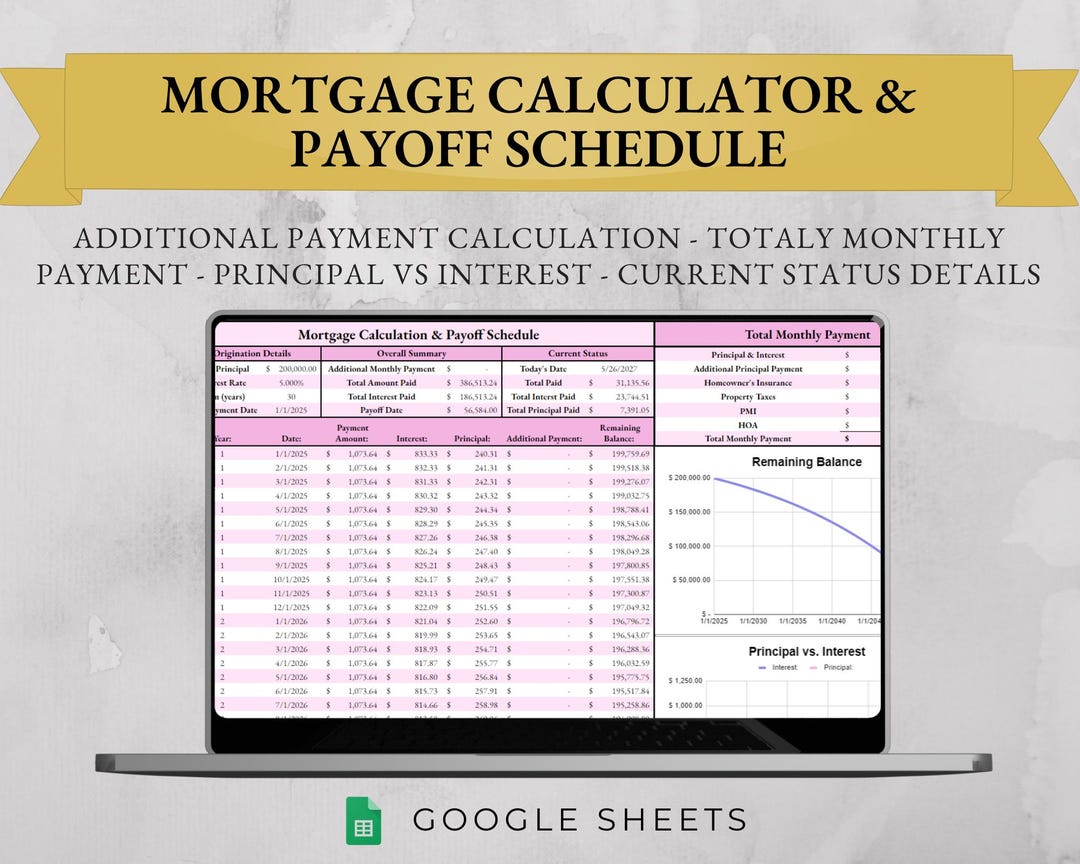
Start with these cells: B1 for current balance, B2 for annual rate, B3 for remaining term in months, B4 for extra monthly payment, B5 for regular monthly payment. The regular payment formula is =PMT(B2/12,B3,-B1). Then create a schedule. Column A gets the month number. Column B tracks the remaining balance. Column C is the interest portion: =B10*(B2/12) where B10 is the prior month's balance. Column D is the principal portion of the regular payment. Column E adds the extra payment to the principal column. Column F subtracts the total principal paid from the prior balance. Copy that row down for the full term. It's about ten minutes of work once you understand the structure. After that, you can adjust the extra payment cell and watch the payoff date shift in real time.
The Numbers Don't Lie But They Can Mislead
Here's the thing most calculators won't tell you. They assume every extra payment hits on day one of the month and never misses a month. In reality, some lenders apply overpayments differently. A few will sit in a suspense account and only get applied at the next payment due date. Others automatically reamortize your loan, which means instead of shortening the term, they just lower your monthly payment. That can be useful if you're cash-strapped, but it completely defeats the purpose if you're trying to get out of the loan faster. I ran into this exact problem in 2019. I was paying an extra $400 a month on a $280,000 balance at 4.2% with about 22 years left. The calculator said I'd shave off roughly 5.3 years and save around $47,000 in interest. Three months in, I noticed my payment hadn't changed and the payoff date on my statements wasn't moving. I called the servicer. Turns out they had reamortized the loan automatically. My extra payments were reducing the term slightly but not anywhere near the calculated amount. Their system was spreading the benefit across my monthly payment instead of compounding it forward. The workaround was simple enough but annoying. I sent a written request to have all overpayments applied directly to principal without reamortization. They processed it within two weeks. The payoff date jumped back to where the original calculation predicted. Make sure you do this in writing. Verbal requests get lost in servicing departments.
Get the Full Details
Things Most People Miss
The biggest blind spot is the difference between making one extra payment per year versus paying extra every month. A lot of calculators default to monthly extra payments, but some homeowners prefer to throw a lump sum at the loan once a year. The math works out almost the same either way. The annual approach might save you a few hundred dollars more over the life of the loan because the compounding happens slightly faster. But the monthly approach builds discipline and keeps your cash flow predictable. Another detail nobody emphasizes. If your interest rate is below 4%, the math behind extra mortgage payments starts looking less attractive compared to other investments. I've seen people aggressively pay down a 3.5% loan while sitting on stock portfolio returns averaging 7% or 8%. That's a choice, not a mistake. The calculator will still show you the savings on the mortgage side, but opportunity cost matters. I ran both scenarios side by side in my spreadsheet before committing. The mortgage payoff looked clean on paper. The investment comparison made me scale back my extra payments by half. Still worth it, just not as aggressively as the calculator suggested.
When This Tool Falls Apart
Additional Mortgage Payment Calculators assume a fixed-rate loan. If you have an adjustable-rate mortgage, the numbers become speculative after the initial fixed period ends. The calculator can't predict rate changes. It also assumes you'll maintain the same extra payment amount indefinitely. Life rarely works that way. Job loss, medical bills, or market downturns usually interrupt consistent overpayment strategies. Some calculators also don't account for tax implications. Mortgage interest deductions matter less now that the standard deduction is higher, but if you itemize and your loan balance is large, the tax impact of reducing principal faster is worth factoring in. A $400 monthly overpayment on a $500,000 loan saves roughly $1,600 in annual interest in the early years. At a 24% marginal tax bracket, that's about $384 in lost deductions. Small, but real. It doesn't change the decision for most people. It does matter if you're on the margin between two strategies. If your situation involves an ARM, significant tax considerations, or uncertain income, a flat calculator won't give you the full picture. You'd be better off running multiple scenarios in a spreadsheet and stress-testing against rate increases or income disruptions. A simple Additional Mortgage Payment Calculator gives you a baseline, not a guarantee.
Bottom Line
Use the calculator to get a sense of the timeline and interest savings. Don't treat the output as an exact promise. Verify how your servicer applies overpayments. Build a spreadsheet you can adjust. And remember that paying off a mortgage early is a financial decision, not necessarily the optimal one depending on your broader picture.