How Adjustable Rate Loans Actually Work
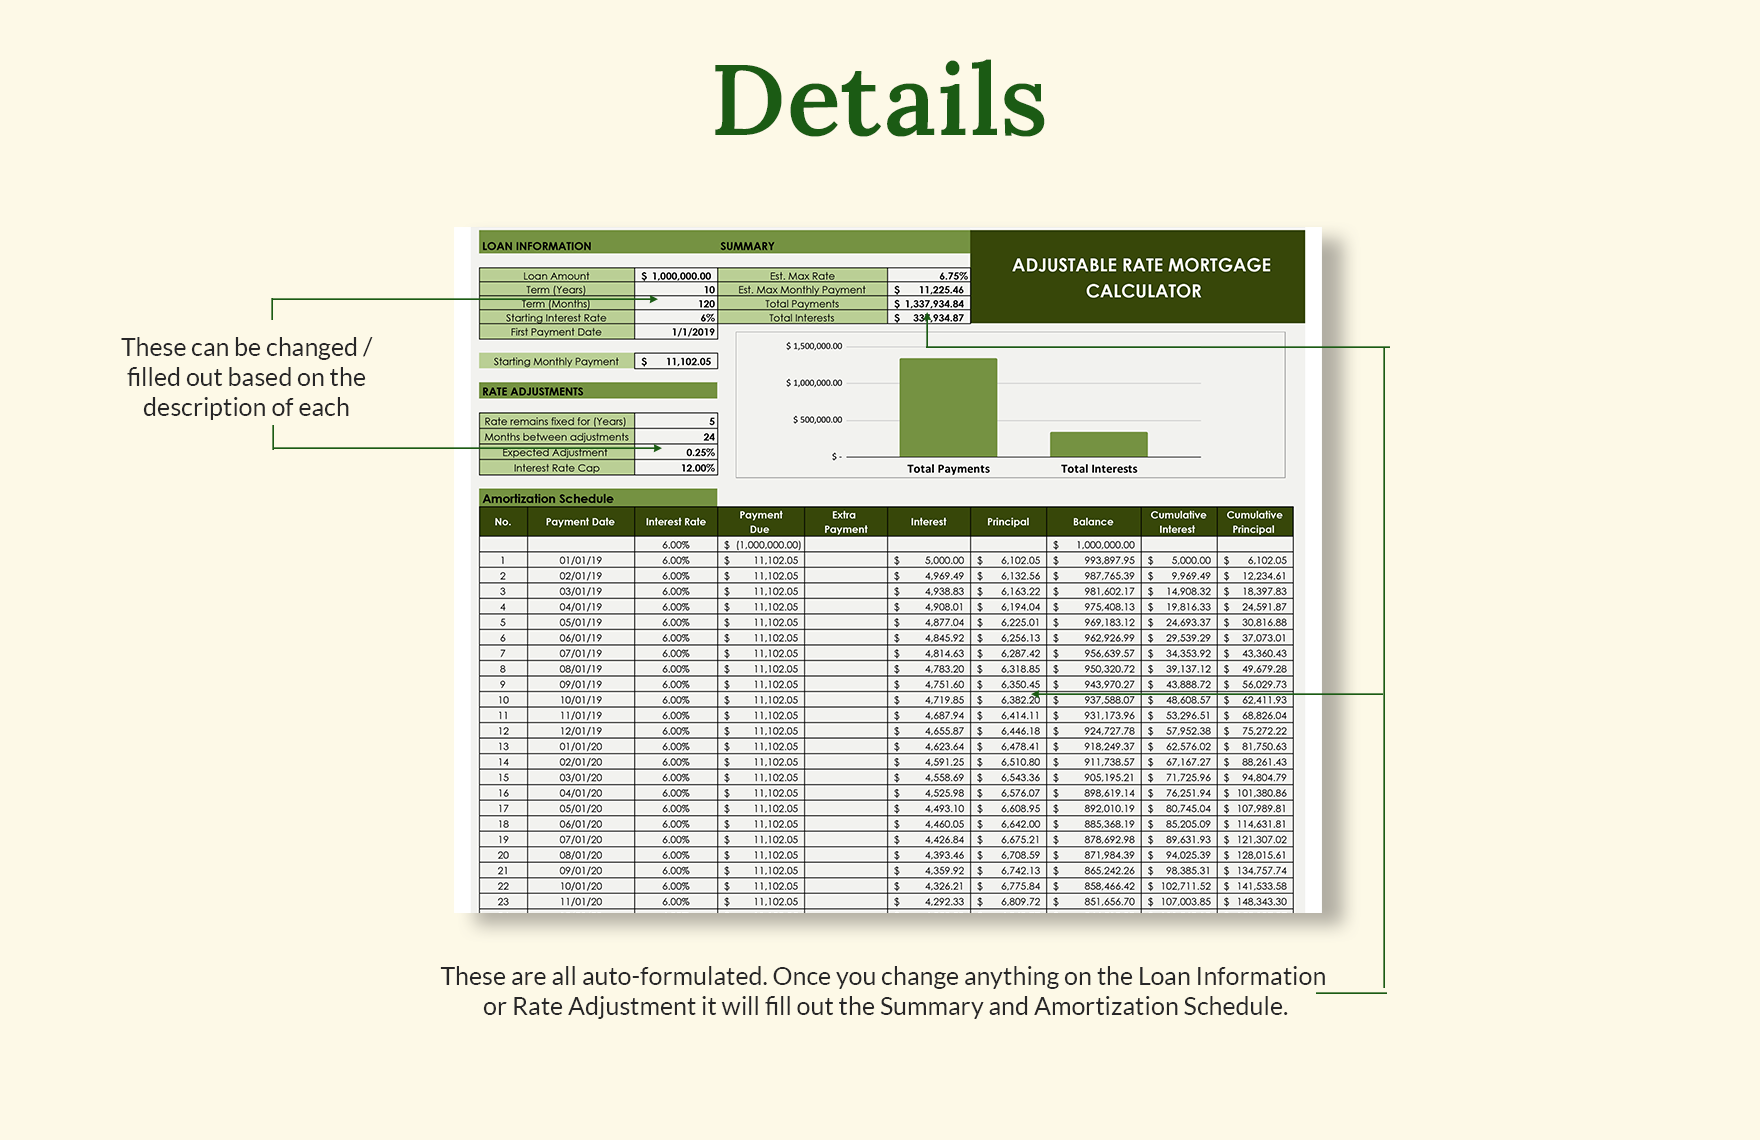
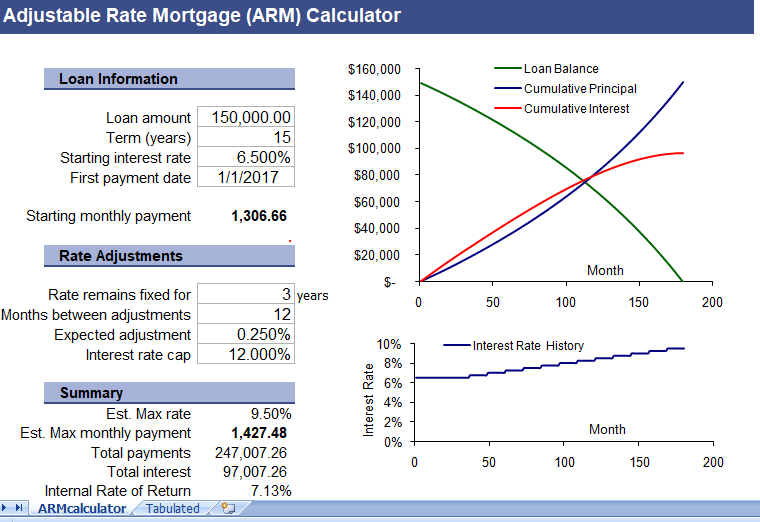
An adjustable rate loan changes its interest rate over time instead of staying locked at one number for the life of the loan. The rate adjusts based on a specific index plus a fixed margin. Most people encounter these with mortgages, though they show up in student loans and auto loans too. The basic idea is simple enough, but the mechanics beneath it are where things get messy. You put in your starting rate, the adjustment schedule, the index you're tied to, and the margin the lender added. The calculator then projects what your payments could look like over the loan term. This doesn't mean every output is accurate. It means it gives you a reasonable ballpark if you feed it decent inputs. I spent about three weeks building out the calculator I now use for work, and honestly, getting the compounding logic right took longer than anything else. The core formula isn't difficult, but edge cases around partial periods and payment dates trip up most off-the-shelf tools. The standard calculation starts with your remaining principal. You multiply that by the monthly interest rate, which is your annual rate divided by twelve. Then you add that interest to get the total owed for the period. Subtract your payment, and whatever is left becomes the new principal for the next cycle. When the rate adjusts, you redo the math with the new rate. That's it. The repetition is where the complexity creeps in.
I ran into a problem last year with a borrower who had a 5/1 ARM. The first five years were fine, straightforward. But in year six, when the rate adjusted, the lender's platform used a day-count convention of 30/360 while my calculator assumed actual/365. The payment came back nearly forty dollars higher than my projection. I had to go back and rebuild the day-count logic to match the lender's exact method. After that, the discrepancies dropped to under five dollars across most scenarios. That level of precision matters when you're dealing with six-figure balances and rates that can swing two or three points.
What the Calculator Won't Tell You
Most adjustable rate calculators focus on the payment, not the total cost. They'll show you month one through month sixty or however many years you're projecting, but they won't factor in your rate caps unless you enter them manually. Every ARM has three kinds of caps. The periodic cap limits how much the rate can change at each adjustment. The lifetime cap sets the maximum rate you'll ever pay. And the initial cap controls the first adjustment, which is often different from the periodic cap. Without entering these correctly, your projection could be wildly off. Another thing people miss is negative amortization. If your payment cap is lower than the interest that accrues, the unpaid interest gets added to your principal. Your balance grows instead of shrinks. Some ARMs have payment caps that trigger this, especially in high-rate environments. A calculator that doesn't model this will give you a comfortable number that turns out to be wrong. You need one that tracks principal separately and flags when the payment falls short of the accrued interest. Index selection matters more than most borrowers realize. The most common indexes are the SOFR rate, the one-year Treasury yield, and the COFI rate. They don't move in perfect sync. Over a ten-year period, SOFR and the Treasury have tracked relatively closely, but COFI has historically lagged because it includes bank funding costs that change more slowly. If your loan is tied to COFI, your adjustments will feel delayed but also less volatile. The calculator should let you pick the index and pull in historical data so you can see how your specific loan would have performed under past rate cycles.
Get the Full Details
Building Your Own vs. Using an Existing Tool
If you're just trying to get a rough sense of your payments, a free online Adjustable Rate Calculator will do. They're usually fine for standard 5/1 or 7/1 ARMs with typical margins. You get answers in thirty seconds. If you're working with an unusual structure — a hybrid ARM, a balloon payment tied to an adjustable rate, or a loan with multiple adjustment periods that don't follow a clean schedule — you'll need something more specific. That's when building your own spreadsheet or using a dedicated tool makes sense. I built a simple spreadsheet version that takes about five minutes to set up. Column A is the period number. Column B is the date. Column C is the starting principal for that period. Column D pulls the index value from that month. Column E adds the margin. Column F applies the cap rules. Column G calculates the monthly payment based on the remaining term and the new rate. Column H is the interest portion. Column I is the principal portion. Column J updates the ending principal. You drag it down for however many years you're tracking. It's not glamorous. It works reliably. One thing I'd caution against is relying solely on the payment projection. The payment tells you your monthly cash flow, but it doesn't tell you your total interest cost over the life of the loan. An ARM that starts at a lower rate might save you money, or it might not, depending on where rates go. You need to run scenarios at different rate levels. Try three percent, five percent, and seven percent and see what happens to your total cost. That's the only way to actually assess whether the adjustable rate is worth the risk.
Where the Calculator Breaks Down
Adjustable Rate Calculator tools assume your payment stays constant between adjustments. They don't handle loans with optional extra payments or lump sum principal reductions well. If you plan to pay down the balance early, which most people in a rising rate environment will try to do, the projected numbers become less useful. The calculator doesn't know you paid extra. You need to adjust the principal manually at each period or build that into your spreadsheet. There's also the issue of teaser rates. Some ARMs launch with a temporary rate that's lower than the fully indexed rate. The calculator might not account for this, or it might assume the teaser lasts for the full initial fixed period when it actually expires sooner. Always verify what rate the tool is using for the first period. A two percentage point difference in year one throws off the entire projection. Forex exposure is another blind spot. If your index is tied to a foreign benchmark or a rate that doesn't move predictably, the historical data you're basing your assumptions on may not be relevant. This shows up more often with investment property loans and commercial ARMs. Residential borrowers rarely deal with this, but it's worth knowing if you're analyzing a non-standard loan.
What to Look For in a Good Tool
The best calculators let you input your specific index, margin, and all three cap types. They show you a full amortization schedule, not just the payment amount. They flag negative amortization before it happens. They let you layer in extra payments. They give you a summary of total interest and total cost across different rate scenarios. If a tool does four of those five things, it's decent. If it does all five, it's rare and you should keep using it. My preferred approach is a combination. I use a detailed spreadsheet for my own analysis because I need the flexibility to adjust inputs on the fly and run scenario comparisons. For quick client estimates, I hand them a web-based Adjustable Rate Calculator and walk them through the key assumptions. The spreadsheet is where I verify the details. The web tool is where I get a fast answer. Neither replaces understanding how the loan actually works, but both are useful in their lane. If you're serious about comparing ARMs, don't stop at the monthly payment. Look at the breakeven point. Calculate how many months of lower payments it would take to offset the closing costs and points if you refinance later. Add in the transaction costs of moving to a fixed-rate loan if rates spike. That's the real decision framework, not just which option has the lowest starting rate.

A Note on Current Conditions
Rate environments matter more than people give them credit for. In a low and stable rate period, an ARM looks attractive because the initial discount is meaningful and there's less fear of sharp increases. In a rising rate environment, like we've seen recently, the math changes quickly. Your payment can jump significantly at the first adjustment, and the impact compounds every time the rate resets. A calculator that only shows your starting payment is doing you a disservice. Push it to show year five and year ten at worst-case scenarios, even if those scenarios feel uncomfortable to look at. Bottom line is that the Adjustable Rate Calculator is a planning tool, not a crystal ball. It works best when you treat it as one of several inputs, not the final word on a decision. Run the numbers. Check your caps. Verify the index. Adjust for your own behavior, like extra payments or planned refinancing. The more realistic your assumptions, the more useful the output will be.