Why People Mess Up the Adjusted Trial Balance
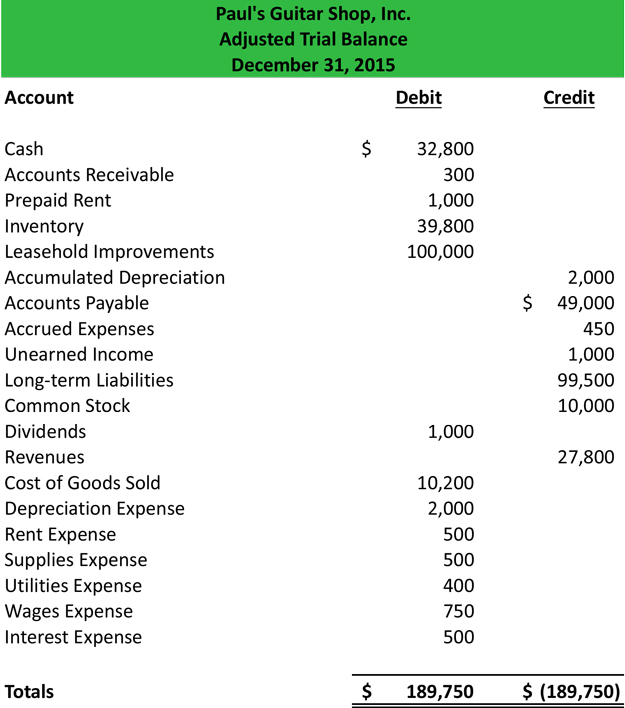
The adjusted trial balance is the step right before you actually prepare financial statements. It's where you take your unadjusted trial balance, layer in all the adjusting entries you made during the period, and verify that debits still equal credits after everything gets moved around. Most people understand the concept in theory. They don't understand how fragile it actually is in practice. Here's how you build one. You start with your general ledger accounts sorted by account number, pulling the unadjusted balances from your accounting software or worksheet. Then you go through each adjusting entry—depreciation, accrued revenues, prepaid expense allocations, bad debt estimates—and post them to their respective T-accounts or sub-ledger lines. Once those adjustments are recorded, you recalculate every account balance. The final column becomes your adjusted trial balance. You total the debit column and the credit column. If they match, you proceed to the income statement and balance sheet. If they don't, you spend however many hours it takes to find the error. I learned the hard way that posting adjustments in the wrong period is the most common source of phantom imbalances. Early in my career I was working on a quarterly close for a mid-market manufacturing client. We had about forty-five adjusting entries to process. I posted a six-month insurance amortization adjustment to the wrong month because I misread the policy effective date. The trial balance still balanced—it always balances if you posted correctly even to the wrong account. The real problem showed up three weeks later when the CFO asked why our insurance expense line item was double what it should have been. By then I'd already closed the books for that quarter. We had to go back and restate. The lesson wasn't about the math. It was about verifying the dates and amounts of source documents before you touch the adjustments column.
How to Build an Adjusted Trial Balance Worksheet
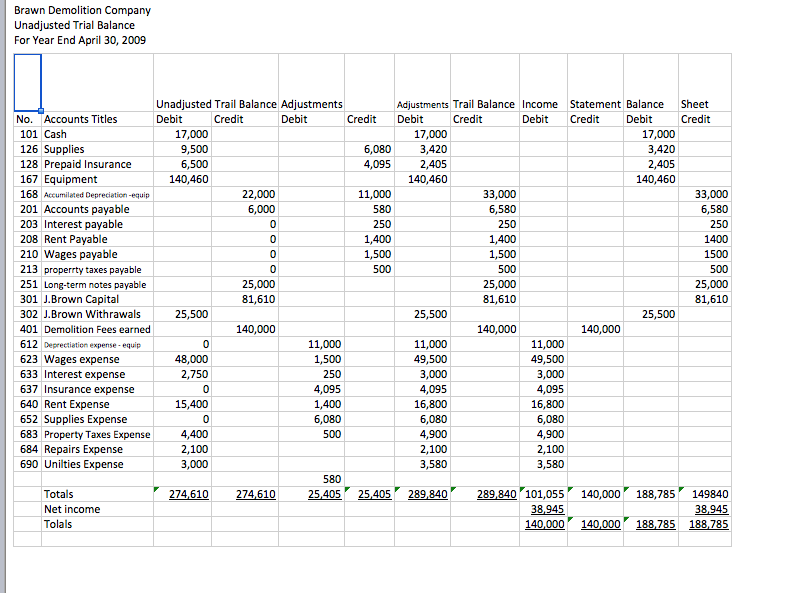
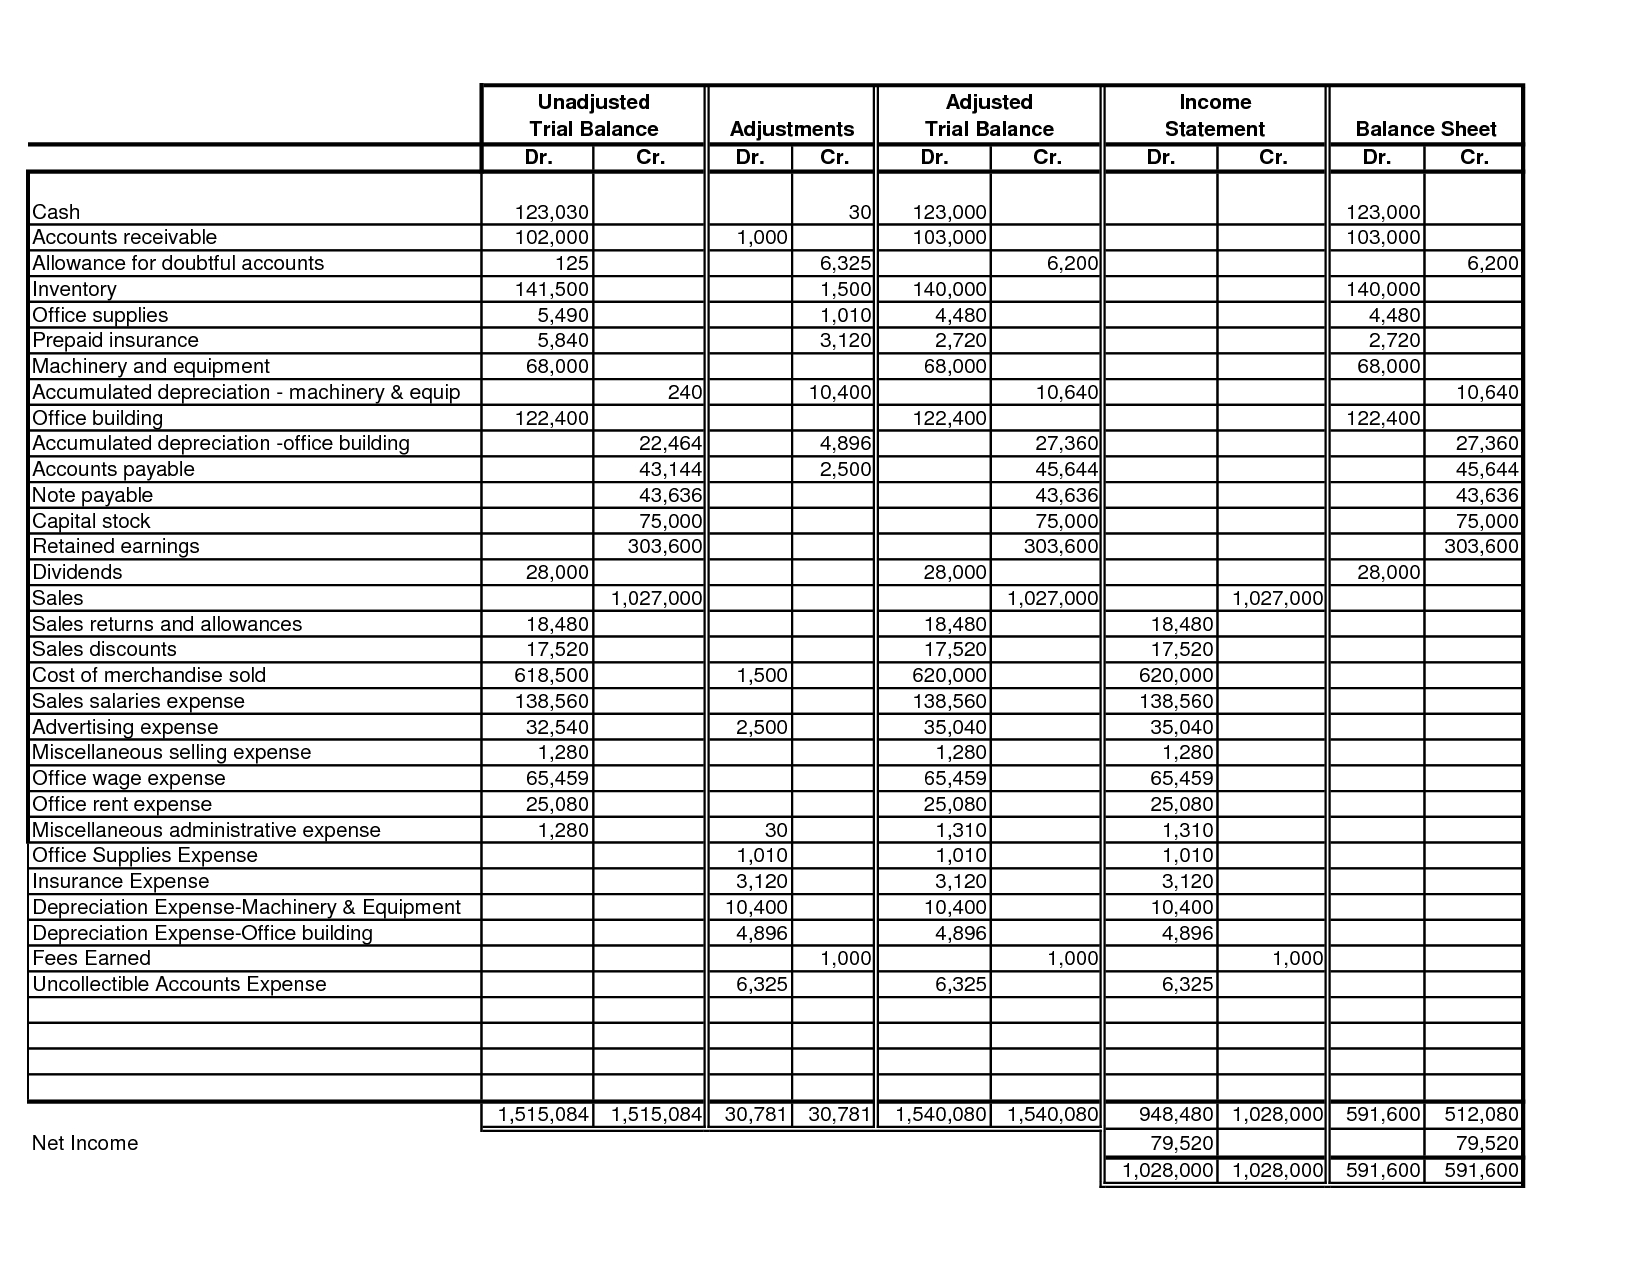
Start with a spreadsheet that has five columns. Label them Trial Balance, Adjustments, Adjusted Trial Balance, Income Statement, and Balance Sheet. The fifth and sixth columns aren't strictly necessary for the worksheet itself but they save you a step when you transfer numbers to the actual financial statements. I keep them because pulling adjusted balances directly into the statement columns cuts the process down from maybe twenty minutes of manual copying to about three minutes of dragging formulas. Row one is your account list. Cash, accounts receivable, inventory, prepaid expenses, equipment, accumulated depreciation, accounts payable, accrued liabilities, common stock, retained earnings, revenue accounts, cost of goods sold, operating expense accounts, depreciation expense, interest expense, and so on. Every account that exists in your general ledger needs a row. Missing an account here means your worksheet won't represent reality. The Trial Balance column holds the pre-adjustment balances. These come directly from your ledger or from your accounting system's unadjusted trial balance report. Do not manually type these unless you have a very good reason. Copy-paste or use a data connection. Human fingers introduce transcription errors at a rate of roughly one per hundred rows, which sounds small until you're three hours into a reconciliation looking for a dollar that's not actually missing.
The Adjustments column is where the work happens. You list each adjusting entry as a debit and credit pair. Common adjustments include accruals for revenue earned but not yet invoiced, accruals for expenses incurred but not yet paid, depreciation on fixed assets, amortization of prepaid items, and reserve adjustments like allowance for doubtful accounts. Each adjustment should have a reference number and a brief description. When your controller or auditor comes looking for support, that reference is the first thing they'll ask for. The Adjusted Trial Balance column is calculated by combining the Trial Balance and Adjustments columns for each row. A debit balance plus a debit adjustment stays a debit. A debit balance minus a credit adjustment reduces the debit. The math is straightforward. The discipline is not. Once the adjusted column balances, you extend the debit and credit balances to the Income Statement or Balance Sheet columns depending on the account type. Revenue and expense accounts go to the income statement column. Asset, liability, and equity accounts go to the balance sheet column. This extension step is mechanical but easy to mess up if you're rushing. Put a revenue account in the balance sheet column by mistake and your net income figure will be wrong even though the worksheet still balances.
Get the Full Details

Things Nobody Tells You About Trial Balance Worksheets
One counter-intuitive thing about the adjusted trial balance is that it can balance and still be completely wrong. The fundamental accounting equation guarantees that debits equal credits, so a balanced worksheet only proves mathematical consistency, not accuracy. You could have recorded a revenue entry twice and a corresponding expense entry twice, and the trial balance would still show equal totals. This is why the reconciliation process before you even think about the adjusted trial balance matters. Bank reconciliations, sub-ledger to general ledger tie-outs, and intercompany eliminations all need to clear before you start adjusting. Garbage in, garbage out, but garbage in gives you a balanced garbage out which is worse because it looks trustworthy. Another thing that trips people up is the treatment of contra-accounts. Accumulated depreciation, allowance for doubtful accounts, and treasury stock are credit balances that reduce asset accounts. When you post adjustments to these accounts, you need to track them separately in your worksheet. If you net them against their related asset accounts in the trial balance column, you'll lose visibility into what changed and why. Keep them on separate lines. It takes two extra rows and saves two hours of explanation later. Timing differences between when an adjustment is recorded and when it takes effect are another quiet source of errors. Say you record a December 31 adjusting entry for accrued salaries on January 2. The entry is dated correctly in your system, but if your trial balance report pulls from a date-based view that doesn't include posts after the close date, the adjustment won't show up. You'll run an adjusted trial balance that looks complete and realize two days later that payroll accrual is missing. The workaround is to run your trial balance with a cutoff that includes the full posting window, not just the period end date.
Here's a specific edge case I ran into last year with a client using a cloud-based ERP. They had intercompany transactions between two subsidiaries that were eliminated at the consolidated level but hadn't been properly allocated back to the individual entity trial balances. The adjusted trial balance for each entity balanced on its own. The consolidated worksheet didn't. The problem was invisible unless you built the consolidated worksheet in the same file as the individual entity worksheets and cross-referenced the elimination entries. What took me about forty-five minutes to diagnose was caused by a missing consolidation adjustment row that nobody had populated because the finance team assumed the system handled it automatically. Systems don't handle it automatically unless you configure them to. That's not a systems problem. That's a process problem.
When the Adjusted Trial Balance Worksheet Fails You
Spreadsheet-based worksheets have real limitations at scale. If you're working with more than fifty accounts and more than twenty adjusting entries per period, the manual approach becomes fragile. Formula errors propagate silently. Version control becomes a nightmare. Multiple people editing the same file simultaneously is a recipe for overwritten cells and lost adjustments. At that point you're better off using your accounting system's built-in trial balance and adjustment posting features, or moving to dedicated financial close software that maintains an audit trail and enforces sequencing. Even with software, the conceptual workflow is the same. The worksheet is a tool for verification, not a substitute for understanding what each adjustment represents. I've seen controllers treat the adjusted trial balance as a black box they feed numbers into and expect clean financial statements to come out. That doesn't work. You need to understand why each adjustment exists, what it's affecting, and whether it's recurring or one-time. A one-time adjustment that gets repeated every period without review will slowly drift your financials away from reality. I once reviewed a company where someone had recorded a one-time restructuring charge as a recurring monthly expense for eight quarters. The adjusted trial balance balanced every single month. The income statement was quietly understating operating income by a material amount. The fix required pulling the original board authorization document and tracing it through every period's adjustments. The bottom line is that the Adjusted Trial Balance Worksheet is a checkpoint, not a destination. It confirms that your ledger is internally consistent after adjustments. It doesn't confirm that the adjustments are correct, that the accounts are complete, or that the financial statements will be accurate. Those things require separate verification steps. Treat the worksheet as part of a process, not the process itself, and you'll avoid most of the problems that show up during audits and month-end reviews.