Understanding how ADP Funds Control Management actually works
Most people coming from smaller systems hit a wall when they first try to set up funding controls in ADP. The interface assumes you already know where certain settings live, and it will let you move forward even when your configuration is incomplete. I spent three weeks dealing with a payroll run that stalled because of this exact issue.
The core function is straightforward: ADP needs to know which bank account to pull payroll funds from, when to pull them, and what approval limits should apply before money leaves your account. It also handles the reconciliation side so your general ledger matches what actually went out. The complexity comes from the many moving parts — multiple funding sources, daily versus weekly schedules, employee-elected direct deposit preferences, tax withholding timing, and state-specific requirements.
Getting started with Adp Funds Control Management
You need to have an active ADP client site first. That is handled during your onboarding, but if you are migrating from another provider, do not assume your existing bank details carry over automatically. They do not.
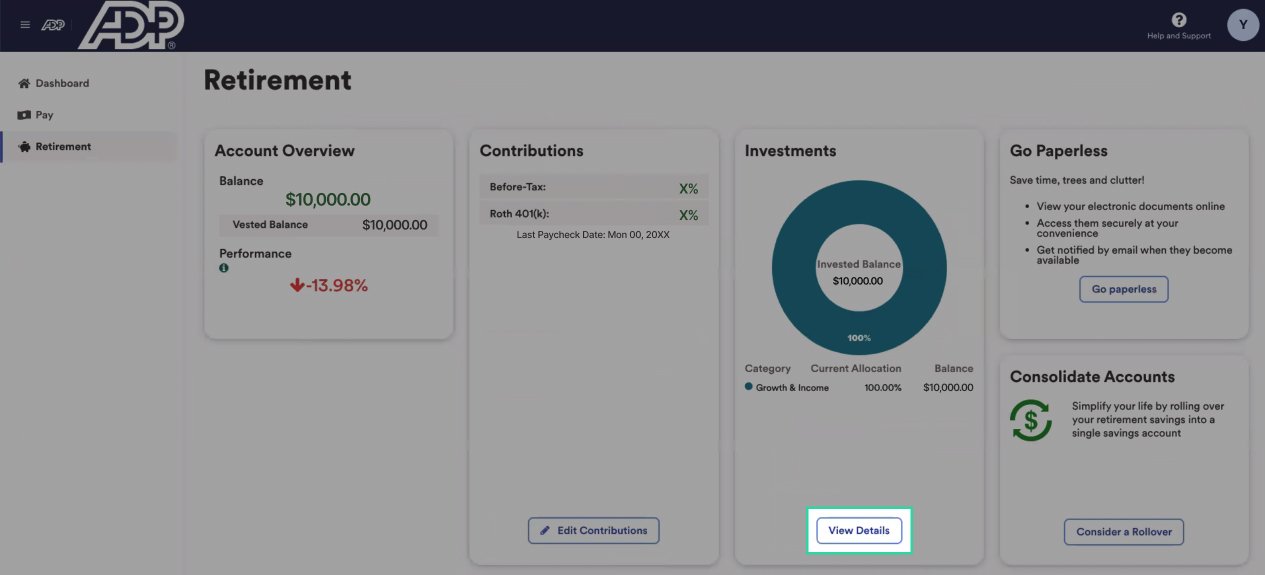
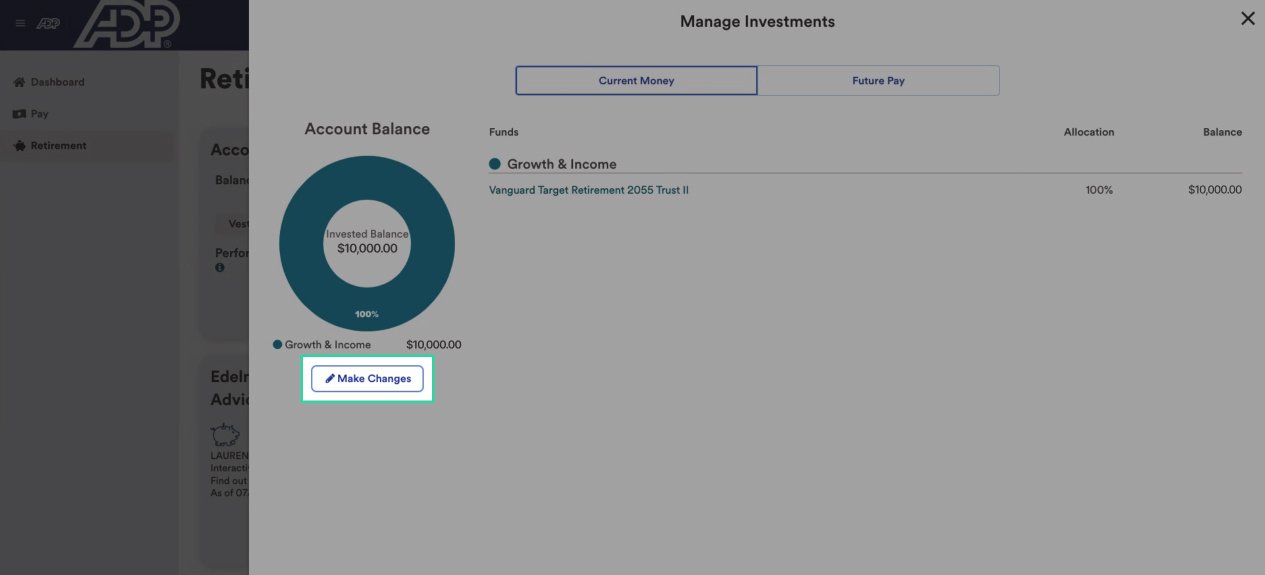
Once logged in, navigate to the Payroll Funding section under Company settings. You will see options for setting up your primary funding account and any secondary accounts. The system allows up to two bank accounts per location, and if you are running multi-state operations, each state entity may need its own funding setup. Here is where most people waste time — they set up one account and assume it covers everything. It does not. If your entities are separated legally, each one needs its own funding source configured.
When entering bank information, ADP uses micro-deposit verification rather than the old routing number validation method. Plan for two business days minimum for that process to complete. Do not schedule a payroll run while the verification is pending. The system will allow it, and then you will be scrambling when the ACH fails.
For the funding schedule, you have several options. Same-day funding is available but carries a fee that adds up quickly if you run payroll daily or weekly. Most mid-size companies settle on a next-business-day default with manual overrides when necessary. This gives you a buffer without the constant premium charges.
Approval workflows and control limits
This is the part people misunderstand. Funds Control Management in ADP is not just about which bank account gets tapped. It is about who can authorize what amount before the system processes the transaction.
You can set up multi-level approvals where any single payment above a certain threshold requires a second sign-off. The default threshold is often set too low for organizations that process frequent inter-company transfers or bonus payments. I once worked with a company where the default was set to $1, and every routine payroll adjustment triggered a secondary approval workflow. It took eight hours to process a standard biweekly run instead of the usual forty minutes.
To configure this properly, go to Approval Settings under the same Company section. Set your thresholds based on actual transaction sizes in your business. If you process payroll at around $50,000 per cycle and your largest non-payroll disbursement is $5,000, a secondary approval threshold of $10,000 makes sense. Anything below that is routine. Anything above that warrants a second pair of eyes.
There is also a hold mechanism. You can place a temporary hold on funding for a specific run without cancelling it entirely. This is useful when you need to verify a balance before committing funds but do not want to reschedule the entire payroll cycle. The hold stays in effect until you release it or the funding date passes, at which point the system automatically cancels the scheduled transfer.
The reconciliation process most people skip
ADP generates a funding report after each payroll run. It shows the exact amount withdrawn, the timestamp, the receiving account, and the breakdown by pay period. This report should be matched against your general ledger entries within forty-eight hours. Most companies do not do this consistently, which creates reconciliation gaps that compound over quarters.
I discovered this the hard way when an audit flagged a $12,000 discrepancy that traced back to a single misfunded week six months earlier. The original funding had gone through without issue, but a subsequent adjustment run pulled from the wrong secondary account because the primary account had insufficient balance at the time. ADP did not flag this as an error because both accounts were valid. It only showed up when someone actually compared the bank statements line by line against the GL.
The workaround I use now is a simple spreadsheet that pulls the weekly funding report data and cross-references it with the GL posting dates. It takes about twenty minutes per pay cycle and catches mismatches before they become problems. You can export the funding report directly from ADP as a CSV file, then use basic VLOOKUP functions to match entries.
Edge cases and limitations
ADP Funds Control Management has real constraints that the documentation does not always make obvious. First, if you change your primary funding account mid-cycle, any scheduled runs tied to that account will not automatically reroute. You have to manually update each pending run, and there is no bulk edit option for this. Second, the system does not support partial funding from multiple accounts in a single payroll run unless you set up separate sub-runs, which is cumbersome for anything beyond simple test scenarios.
Third, and probably most important, ADP does not integrate directly with most accounting platforms for automated reconciliation. You are still exporting reports and matching them manually, even with the premium tiers. If your team expects real-time sync between ADP funding and your ERP, you will need a middleware solution or a custom integration through ADP's API.
I switched to using a dedicated payroll reconciliation tool for our multi-entity operation because the manual process was consuming roughly four hours per pay cycle across three different company codes. The tool costs about three hundred dollars monthly but saves us approximately sixteen hours of staff time. For smaller operations with a single entity, the native export process is adequate if you stay disciplined about doing it on schedule.