How to Actually Use the ADP Payroll Tax Guide for 2013
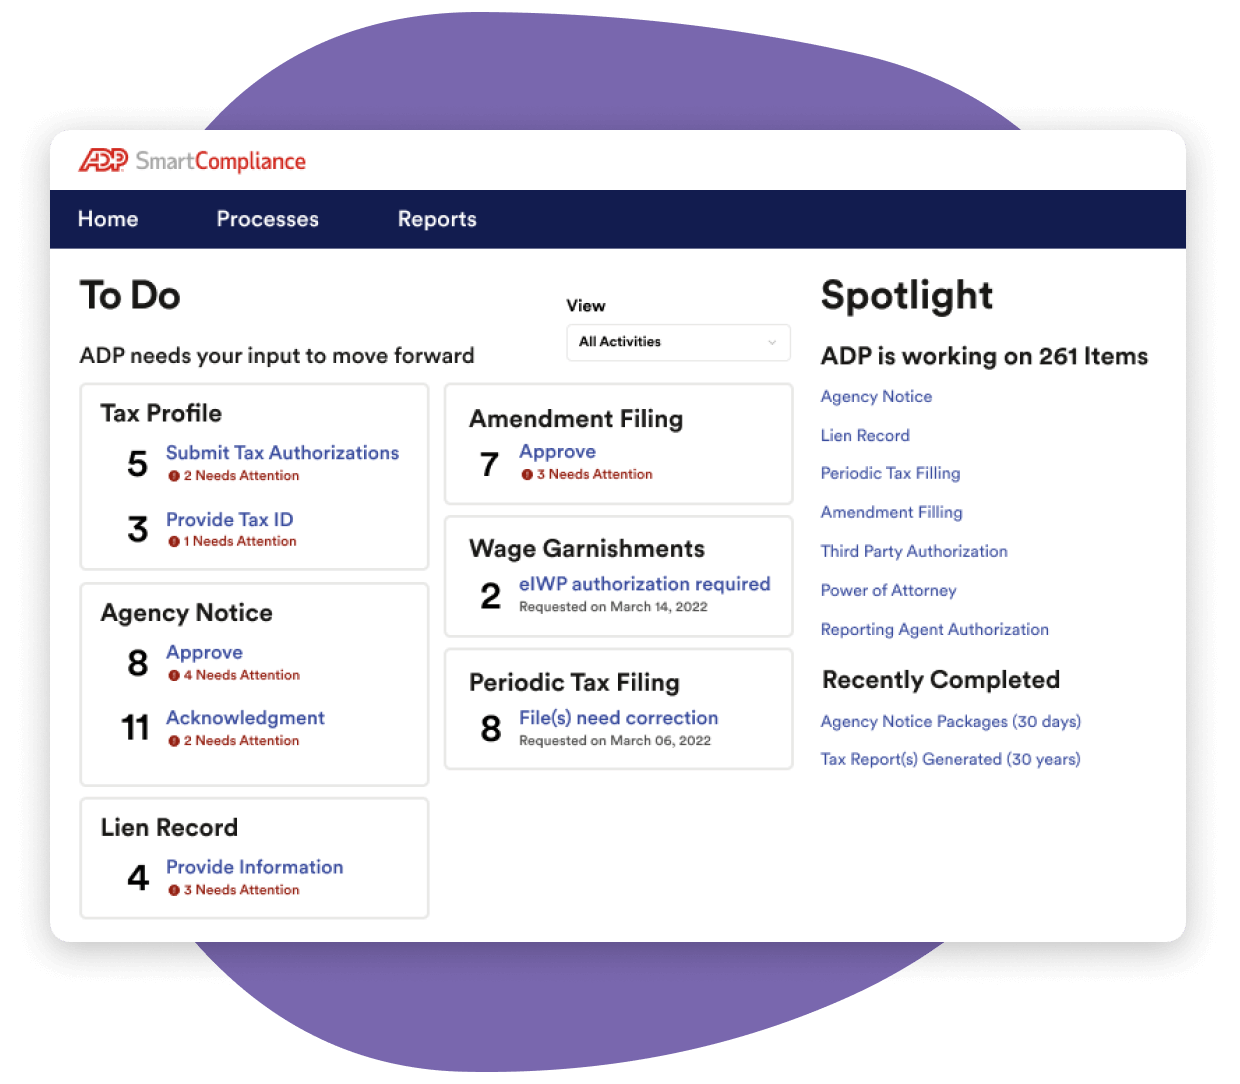
The ADP Payroll Tax Guide for 2013 is not a single downloadable document you can just open and start using. It is a combination of federal tax tables, state withholding schedules, local tax supplements, and ADP-specific configuration notes that get pushed out when you update your payroll system for the new year. If you are looking for a PDF you can print and staple, you will be disappointed. What you actually get is a set of tax rate tables embedded in your ADP account or a web-based reference tool called ADP Tax Tables, depending on which version of the platform you run. I ran a mid-size manufacturing client through a 2013 year-end close and hit a wall with their Colorado withholding. The guide listed the flat rate as 4.55 percent, which was correct for most of the year, but Colorado had passed a temporary tax change in early 2013 that created a two-tier structure for a brief window. ADP had not updated their published guide yet. I ended up calling the ADP support line at 1-800-225-5237, got put on hold for twenty minutes, and eventually found the correction in the ADP Knowledge Base under a notice number I will not bore you with. The workaround was to manually adjust the withholding table override in the client's setup and document the change with a screenshot and a note in the payroll journal. That took me about forty-five minutes instead of the usual five.
Adp Payroll Tax Guide 2013
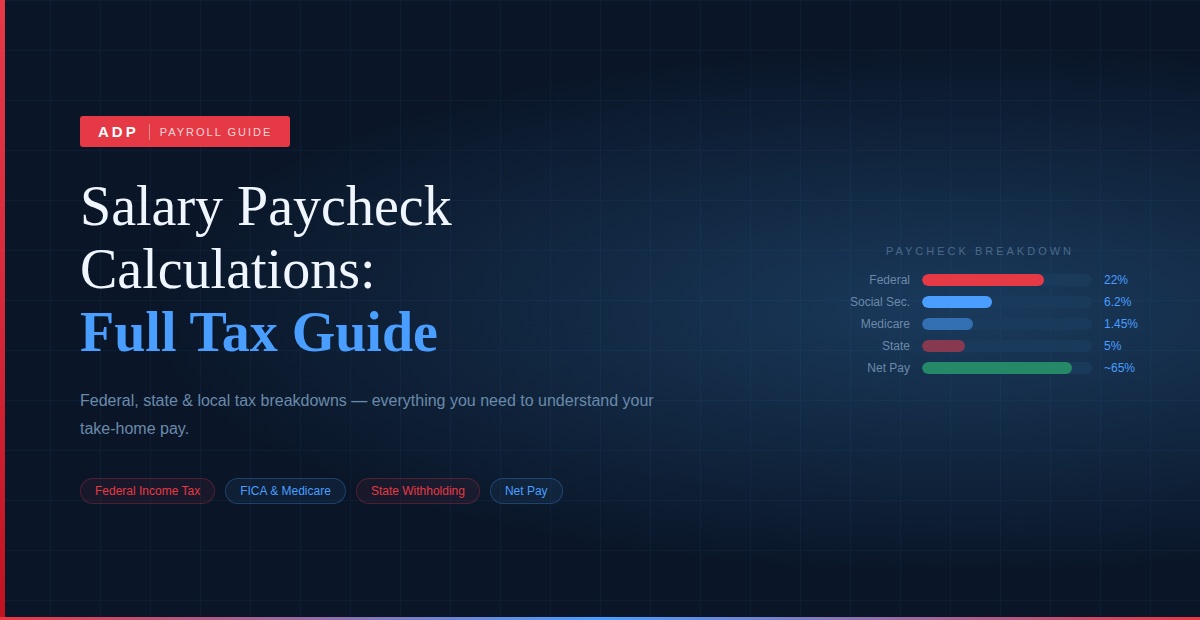
Here is the practical part. If you are setting up or verifying your 2013 payroll taxes, here is what you actually need to do and where things typically go wrong. Federal income tax withholding. The 2013 guide uses the percentage method and wage bracket tables from IRS Publication 15-T. ADP maps these directly into your employee withholding profiles. The catch is that 2013 was the first year after the fiscal cliff legislation took effect, and the exemption amounts shifted slightly from 2012. If you are rolling over employee setups from 2012 without running the annual withholding allowance update, your employees will either be over-withheld or under-withheld by a few dollars per paycheck. That sounds small until you are reconciling Form 941 at the end of the quarter and the numbers do not balance. FICA taxes. Social Security and Medicare in 2013 had a notable quirk. The Social Security wage base increased to $113,700, and the Medicare rate stayed at 1.45 percent for employees. But the employer-side Social Security rate dropped to 6.2 percent from 6.2 percent plus an additional 0.9 percent—that extra 0.9 percent was suspended for 2013 only. This is easy to miss if you are relying on memory from 2012. ADP handles the employer rate automatically when you update your tax table files, but if you are doing anything manual or running custom reports, you need to make sure the employer SS rate is coded correctly. I have seen two clients accidentally apply the old rate and overpay their employer share by about $2,400 on a fifty-person payroll before anyone noticed.
State withholding. This is where most people run into trouble. Not every state uses the federal withholding tables as a base. California, New Jersey, and Utah have their own calculation methods. Iowa recalculates every quarter. If you operate in multiple states, the 2013 guide will have separate sections for each, and they are not always internally consistent because different states update on different schedules. I had a client with employees in Nebraska and Kansas who got hit with a late update to the Kansas tax tables mid-quarter. ADP sent a notification, but the payroll had already been processed. The fix was to run a correction batch in the next cycle and file an amended Kansas withholding return. It added roughly three hours of work and a lot of unnecessary stress. Local taxes. Only a handful of local jurisdictions require withholding—cities in Ohio, New York, Pennsylvania, and Indiana come to mind most often. If your employees live in one of these areas and you skip the local tax setup, you will get penalties. ADP covers most of the major ones, but they do not cover every municipality. You need to check your specific employee locations against the ADP local tax coverage list, not assume it is there by default. Social Security number verification. The 2013 guide mentions SSA Name Match, which became more important that year due to increased IRS enforcement. If an employee's name and SSN do not match what the Social Security Administration has on file, ADP will flag it during payroll processing. I have seen this cause payment holds on quarterly filings for small clients who had not verified their employee data in years. The fix is straightforward—you ask the employee to bring a W-2 or a Social Security card to the office and update the record. But if you are running payroll weekly, you do not want to discover this in March when you are trying to file Form 941 for the first quarter.
Get the Full Details

One thing the guide does not make clear is how to handle employees who are subject to both federal and state backup withholding. ADP allows both to be applied simultaneously, but the interaction between them is not intuitive in the interface. If you set backup withholding at 28 percent for federal and then also enable state backup withholding, some versions of the system will apply both rates to the same wages, which doubles the withholding incorrectly. I learned this the hard way with a contractor who had a pending IRS notice. The workaround is to enter backup withholding at the federal level only and let the state withholding table handle its own backup rate through the standard withholding setup. It is not documented well in the guide. Another thing nobody tells you: the ADP tax table updates are not always immediate. When the IRS or a state revenue department releases a new table, ADP typically pushes the update within one to three business days. During that window, your payroll runs on outdated rates. If you have a major payroll in progress when an update is pending, you should either delay the run or manually verify the current rates against the government source. I keep a spreadsheet with the effective dates for every state I work with and check it before each quarter-end payroll. If you want the actual 2013 guide content, you access it through your ADP account under Reports and Forms, then select Tax Tables. You can also download the individual state supplements as PDFs from the ADP resource library. There is no single master document. The IRS also publishes their own 2013 withholding tables in Publication 15-T, which you can cross-reference if ADP's version seems off. I always do that for the first payroll run of the year after an update. It takes about ten minutes and has saved me from making mistakes more than once.
The biggest limitation of the ADP Payroll Tax Guide 2013 is that it assumes you are using ADP's standard payroll setup. If you have custom wage types, union agreements, or multi-state apportionment rules, the guide does not cover those scenarios. You will need to configure those manually or work with an ADP specialist. For most small to mid-size businesses with straightforward payrolls, the guide is adequate. For everyone else, it is a starting point, not a complete solution.